Part I, lines 1 to 3: modified AGI
Line 1 takes line 11a of the return. Lines 2a to 2c add excluded Puerto Rico income, Form 2555 lines 45 and 50, and Form 4563 line 15. The instructions call line 3 your modified AGI.
1040
Credits for Qualifying Children and Other Dependents
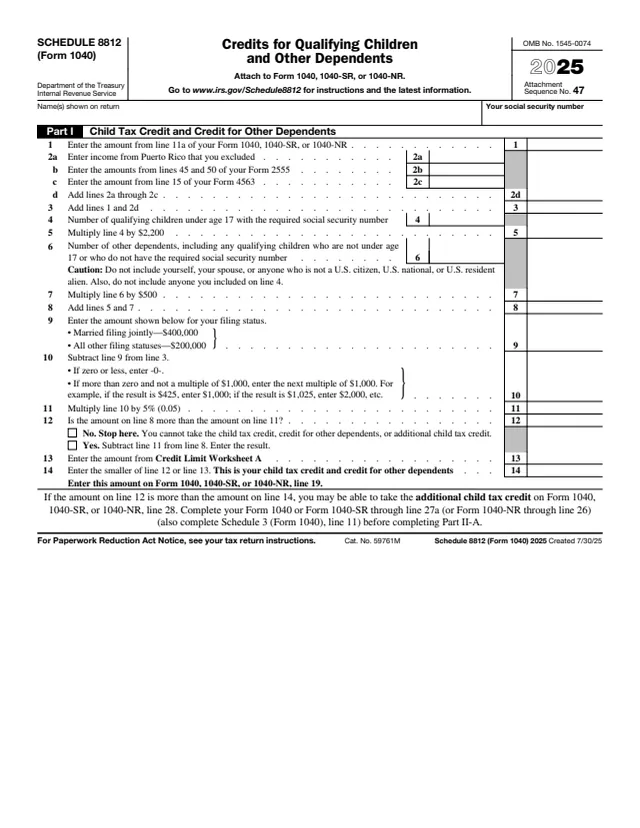
Schedule 8812 (Form 1040) is the IRS schedule used to figure the child tax credit (CTC), the credit for other dependents (ODC) and the additional child tax credit (ACTC). The 2025 form says to attach it to Form 1040, 1040-SR or 1040-NR.
Part I starts from line 11a of the return, multiplies the number of qualifying children under age 17 with the required social security number by $2,200 and the number of other dependents by $500, then reduces the total when the amount on line 3 is more than $400,000 for married filing jointly or $200,000 for all other filing statuses. The credit on line 14 goes to line 19 of the return. Part II figures the refundable ACTC, which the 2025 instructions put at up to $1,700 for each qualifying child, and line 27 goes to line 28 of the return.
The instructions say that beginning in tax year 2025 a valid SSN is needed to claim the CTC or ACTC, and that on a joint return only one spouse needs one, while the other has an SSN or ITIN issued by the due date of the return. You can fill out the schedule free in your browser on this page and download it without an account.
Line 1 takes line 11a of the return. Lines 2a to 2c add excluded Puerto Rico income, Form 2555 lines 45 and 50, and Form 4563 line 15. The instructions call line 3 your modified AGI.
Line 4 counts qualifying children under age 17 with the required SSN, multiplied by $2,200 on line 5. Line 6 counts other dependents, multiplied by $500 on line 7. Line 8 adds them.
Line 9 is $400,000 for married filing jointly and $200,000 for others. Line 10 rounds any excess up to a multiple of $1,000 and line 11 takes 5% of it. Line 13 comes from Credit Limit Worksheet A, and line 14 is the CTC and ODC.
Line 16b multiplies the qualifying children by $1,700. Lines 18a and 18b take earned income and nontaxable combat pay, line 19 the earned income over $2,500, and line 20 15% of that amount.
Lines 21 to 26 use withheld social security and Medicare taxes from Form W-2, boxes 4 and 6, plus amounts from Schedules 1 and 2, less the amounts on line 24.
Line 27 is the additional child tax credit. The form says to enter it on Form 1040, 1040-SR or 1040-NR, line 28.
The instructions say line 4 counts the Child tax credit boxes and line 6 counts the Credit for other dependents boxes checked in the Dependents section of the return. One person can't have both boxes checked.
Enter line 11a of the return, then any excluded Puerto Rico income and the Form 2555 and Form 4563 amounts the lines name. Add them on line 3.
Work through lines 9 to 12. The form says that if line 8 is not more than line 11, stop: the CTC, ODC and ACTC can't be taken.
Figure line 13 on the worksheet in the instructions. Worksheet B is used only with the mortgage interest, adoption, residential clean energy or D.C. first-time homebuyer credit, no Form 2555, and line 4 above zero.
If line 12 is more than line 14, the form says to complete Form 1040 or 1040-SR through line 27a, or Form 1040-NR through line 26, and Schedule 3 line 11, before Part II-A.
Use the Earned Income Chart, or the Earned Income Worksheet with an optional self-employment method, for line 18a. Enter nontaxable combat pay on line 18b, then carry line 27 to line 28 of the return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach Schedule 8812 to Form 1040, 1040-SR or 1040-NR. It is filed with that return and has no separate deadline.
The IRS page lists an update to the 2025 Instructions for Schedule 8812 (Form 1040) dated 10-FEB-2026.
The instructions say the IRS can't issue refunds before mid-February 2026 for returns that properly claim the ACTC, and that this applies to the entire refund.
If the CTC, ACTC or ODC for a year after 2015 was denied or reduced for a reason other than a math or clerical error, the instructions point to Form 8862 unless an exception applies.
The instructions say an error due to reckless or intentional disregard of the rules bars these credits for 2 years, and fraud bars them for 10 years. Penalties may also apply.
The instructions say an ACTC refund can't be counted as income for federal programs, or programs financed in part with federal funds, and not as a resource for at least 12 months.

1040
199 fields, 2 pages
1040-SR
200 fields, 4 pages
1040-NR
171 fields, 2 pages
1040
37 fields, 1 page
8862
109 fields, 3 pages
1040-SS
132 fields, 3 pages
No tool matches that search.
Line 5 multiplies qualifying children under age 17 with the required SSN by $2,200, and line 7 multiplies other dependents by $500. The instructions say the maximum ACTC is $1,700 for each qualifying child.
For the CTC and ACTC, the instructions say the child needs a valid SSN, valid for employment and issued before the due date of the 2025 return, including extensions. A child with another TIN issued by that date may count for the ODC.
Line 9 is $400,000 for married filing jointly and $200,000 for all other filing statuses. The amount above it is rounded up to a multiple of $1,000, and 5% of it on line 11 reduces the credit.
No. Part II-A of the form says that if you file Form 2555, you cannot claim the additional child tax credit.
Line 14 goes to line 19 of Form 1040, 1040-SR or 1040-NR, and line 27 goes to line 28.
The instructions say to attach a copy of the child's birth certificate, death certificate or hospital records, and the document has to show the child was born alive.
Yes. The instructions say Parts II-A and II-B can be used for the ACTC, or Part II of Form 1040-SS instead when Form 1040 or 1040-SR isn't required.