Header, items A to F
The year of RIC status election, the date the fund was established, the EIN, total assets, return type boxes and a personal holding company check box.
1120-RIC
U.S. Income Tax Return for Regulated Investment Companies
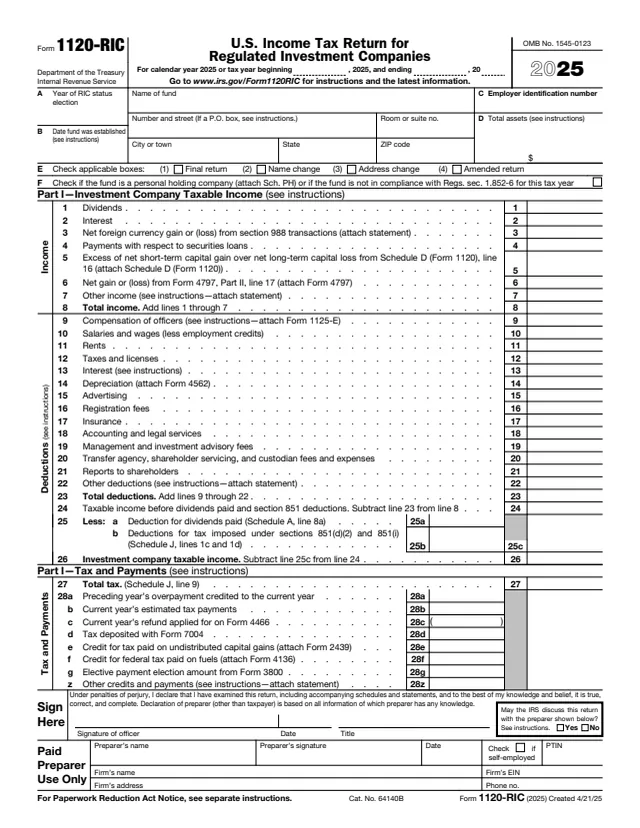
Form 1120-RIC is the U.S. income tax return for regulated investment companies. The IRS says regulated investment companies (RIC) file this form to report their income, gains, losses, deductions, credits, and to figure their income tax liability. This page covers the 2025 form, which the instructions say is filed for calendar year 2025 and fiscal years that begin in 2025 and end in 2026.
The instructions say a domestic corporation that meets certain conditions files Form 1120-RIC if it elects to be treated as a RIC for the tax year, and that the election is made by computing taxable income as a RIC on this form. The return is four pages: investment company taxable income, tax and payments, the tax on undistributed net capital gain, and Schedules A, B, J, K, L, M-1 and M-2.
The return is signed by a corporate officer. You can fill out Form 1120-RIC free in your browser on this page and download the result without an account.
The year of RIC status election, the date the fund was established, the EIN, total assets, return type boxes and a personal holding company check box.
Income on lines 1 to 8, deductions on lines 9 to 23, the deduction for dividends paid on line 25 and investment company taxable income on line 26.
Total tax, estimated tax payments, credits such as the Form 2439 credit, the estimated tax penalty, the amount owed or overpaid and direct deposit fields.
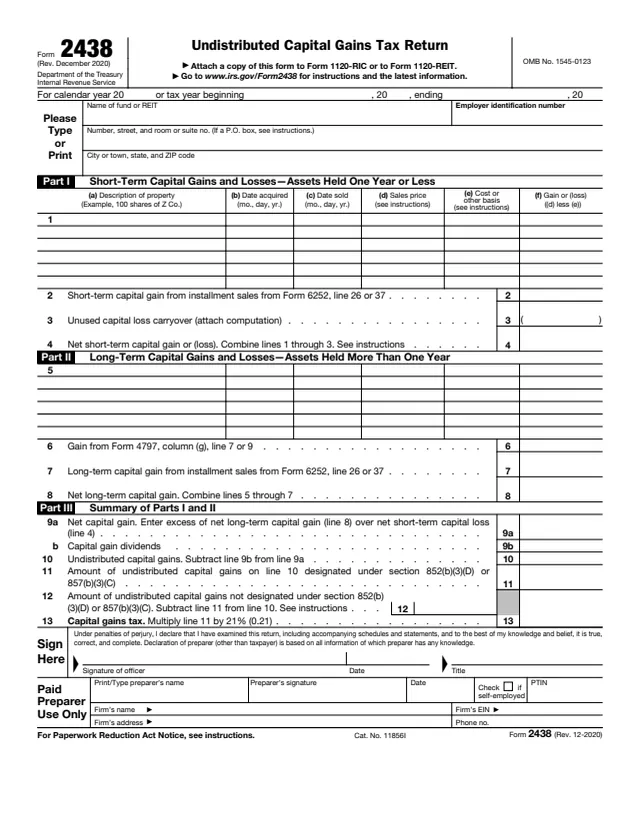
Tax on undistributed net capital gain not designated under section 852(b)(3)(D). The form multiplies line 3 by 21% (0.21) and carries the tax to Schedule J, line 1b.
Schedule A figures the deduction for dividends paid, Schedule B covers income from tax-exempt obligations, Schedule J computes the tax and Schedule K asks other information questions.
The balance sheets per books, the reconciliation of book income with income per return, and the analysis of unappropriated retained earnings.
The instructions say to enter the RIC's true name as set forth in its charter, the address of its principal office or place of business and the EIN, not the registered agent's address.
Report dividends, interest and other income on lines 1 to 7, then the fund's deductions, such as advisory fees and custodian fees, on lines 9 to 22.
Complete Schedule A for ordinary and capital gain dividends paid. Line 8a goes to Part I, line 25a, and line 26 shows investment company taxable income.
Figure any tax on undistributed net capital gain in Part II, then complete Schedule J. Schedule J, line 9, is the total tax entered on line 27.
Enter payments and credits on lines 28a to 28z. For an overpayment, line 33 splits it between 2026 estimated tax and a refund, with direct deposit details on lines 33c to 33e.
Answer the Schedule K questions, complete Schedules L, M-1 and M-2, and have an authorized officer sign. The form notes M-1 and M-2 are not required when Schedule L, line 13, column (d) is less than $25,000.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say generally by the 15th day of the 4th month after the end of the tax year. A RIC with a fiscal tax year ending June 30 files by the 15th day of the 3rd month after the end of its tax year.
The instructions say to file Form 7004 to request an extension of time to file, generally by the regular due date of the return.
The address depends on the state of the principal business, office or agency and on total assets: Kansas City, MO 64999-0012 or Ogden, UT 84201-0012, per the chart in the instructions.
The instructions say RICs will be able to file electronically beginning in mid-February 2026. The About page lists a notice of no penalty for not electronically filing Form 1120-RIC for 2025, dated 20-FEB-2026.
The president, vice president, treasurer, assistant treasurer, chief accounting officer or any other corporate officer authorized to sign. A receiver, trustee or assignee signs instead when filing for the RIC.
The instructions list a penalty of 5% of the unpaid tax for each month or part of a month late, up to 25%. For a return required to be filed in 2026 that is over 60 days late, the minimum is the smaller of the tax due or $525.
2438
101 fields, 3 pages
2439
64 fields, 8 pages
8613
40 fields, 1 page
1099-DIV
140 fields, 6 pages

7004
26 fields, 1 page
1120-REIT
346 fields, 5 pages
Form 1120-RIC is filed by investment funds organized as domestic corporations, not by individual investors. The instructions say the term regulated investment company applies to any domestic corporation that falls into one of the groups below and also meets the income, asset, distribution and earnings and profits rules they describe.
No tool matches that search.
The instructions say a domestic corporation that meets certain conditions files it if it elects to be treated as a RIC for the tax year, or made the election for a prior year that has not been terminated or revoked.
The instructions say the election is made by computing taxable income as a RIC on Form 1120-RIC.
The instructions say the 2025 return is filed for calendar year 2025 and fiscal years that begin in 2025 and end in 2026, with limited use for a short 2026 tax year if the 2026 form is not yet available.
The instructions say RICs will be able to e-file beginning in mid-February 2026, and that a RIC filing 10 or more returns of any type during the calendar year is required to e-file unless it gets a waiver.
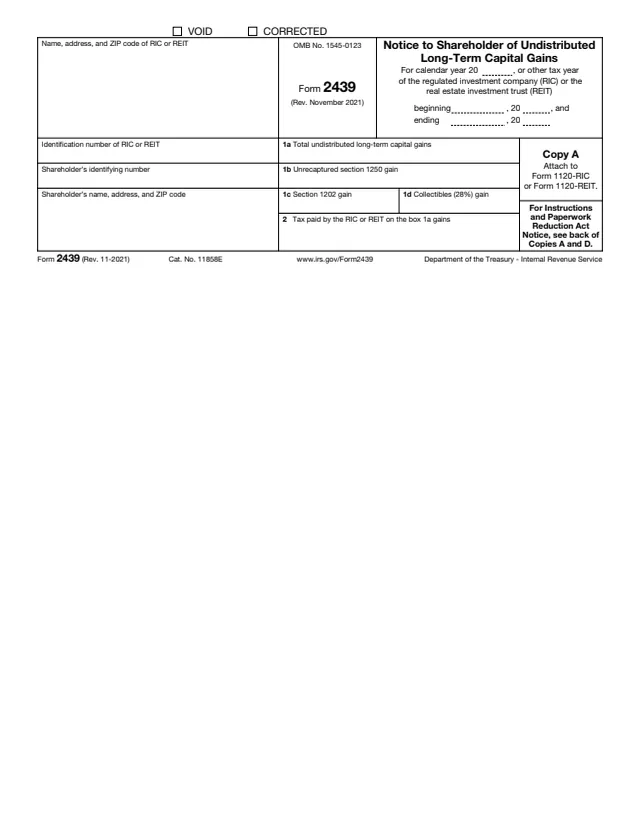
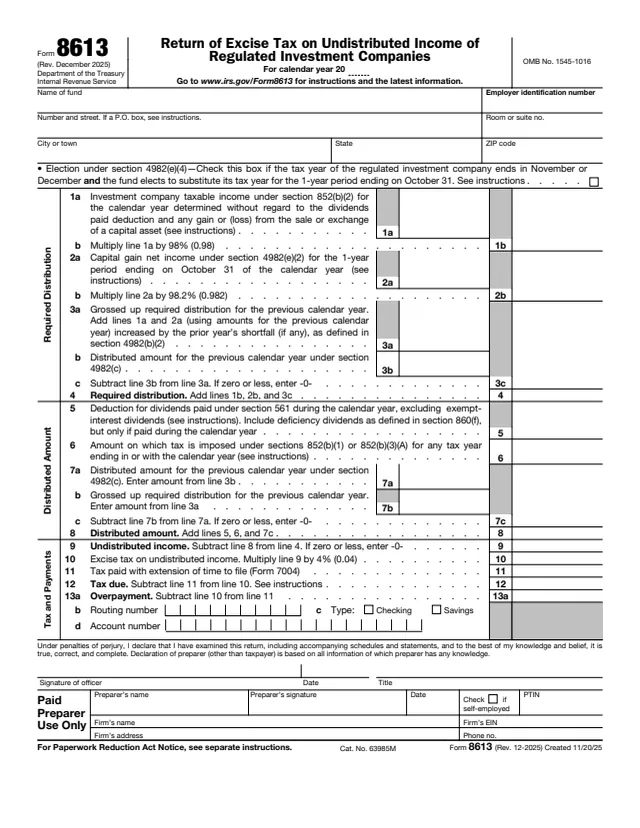
The instructions list, among others, Form 2438 when undistributed long-term capital gains are designated, Form 2439 for shareholders, Form 8613 for the excise tax on undistributed income and Form 1099-DIV.
The instructions say a RIC that does not satisfy the distribution requirements will be subject to taxation as a C corporation.