Header
The calendar year, the fund's name, EIN and address, the administrator's name and address, and boxes for a final return, name change, address change or amended return.
1120-SF
U.S. Income Tax Return for Settlement Funds (Under Section 468B)
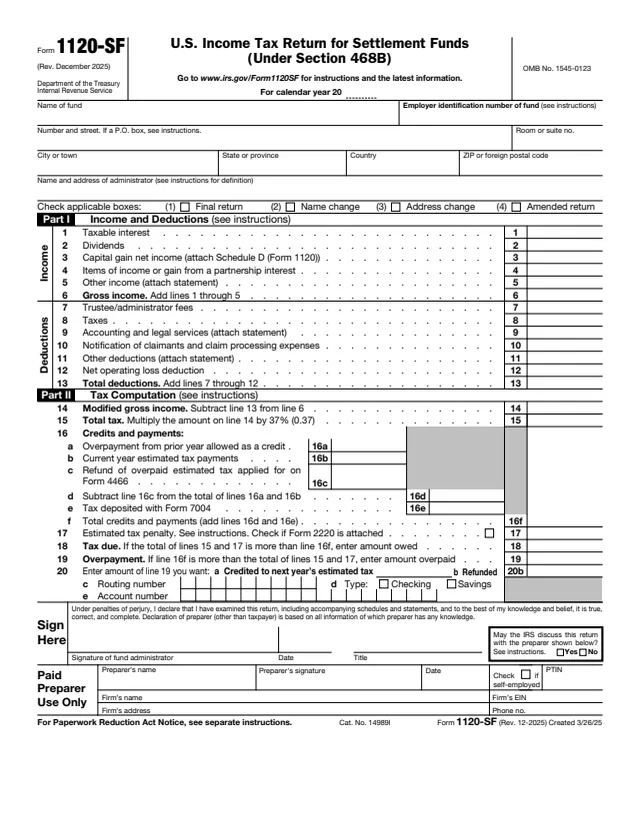
Form 1120-SF, U.S. Income Tax Return for Settlement Funds (Under Section 468B), is the annual income tax return of a designated or qualified settlement fund. The instructions say it reports transfers received, income earned, deductions claimed and distributions made, and figures the fund's income tax liability.
The instructions define a qualified settlement fund as a fund, account or trust that meets three requirements: a governmental order or approval, a purpose of resolving or satisfying claims, and segregated assets. The return is filed for the fund and signed by its administrator. This is the December 2025 revision, which the instructions say is used for 2025 and later years until a superseding revision is issued.
You can fill out Form 1120-SF free in your browser on this page and download the result without an account.
The calendar year, the fund's name, EIN and address, the administrator's name and address, and boxes for a final return, name change, address change or amended return.
Taxable interest, dividends, capital gain net income, items of income or gain from a partnership interest, and other income, added up as gross income on line 6.
Trustee and administrator fees, taxes, accounting and legal services, notification of claimants and claim processing expenses, other deductions and the net operating loss deduction.
Modified gross income, total tax at 37% (0.37), credits and payments, the estimated tax penalty, tax due or overpayment, and direct deposit details.
Cash, government obligations, other investments and other assets, then liabilities and fund balance, each at the beginning and end of the year.
Transfers to the fund, tax-exempt interest, distributions to claimants and to transferors or related parties, the type of liability the fund was set up for, and any court order number.
Enter the fund's true name from its charter or other creating document, its principal office address and its EIN. If no EIN has arrived by the due date, the instructions say to write "Applied For" and the date applied.
Report taxable interest on line 1 and tax-exempt interest on line 2 of Additional Information. Capital gains are detailed on Schedule D (Form 1120). Other income is listed on an attached schedule.
The instructions say not to deduct expenses allocable to tax-exempt income, payments of claims made by the fund, or expenses incurred by or on behalf of claimants or transferors.
Subtract line 13 from line 6 for modified gross income on line 14, then multiply line 14 by 37% (0.37) for total tax on line 15, as the form prints.
Enter credits, estimated tax payments and tax deposited with Form 7004. Check line 17 if Form 2220 is attached. On line 20, credit an overpayment to next year's estimated tax or have it refunded by direct deposit.
Complete Schedule L and Additional Information, attach the qualified appraisals and transferor statements the form asks for, and have the administrator sign and date the return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say generally by the 15th day of the 4th month after the end of the tax year. A fund with a fiscal year ending June 30 files by the 15th day of the 3rd month.
Form 7004 requests an extension of time to file. The instructions say it is generally filed by the regular due date of the return.
A fund in the United States files with the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0012. A fund in a foreign country or U.S. territory uses Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions say settlement funds use electronic funds transfer, such as EFTPS or the fund's IRS business tax account, for federal tax deposits, and pay tax due electronically.
The instructions say a fund that expects its total tax for the year to be $500 or more makes installments by the 15th day of the 4th, 6th, 9th and 12th months of the tax year.
For a return more than 60 days late, the instructions give a minimum penalty of the lesser of the tax due or $525 (adjusted for inflation).

1120
481 fields, 6 pages

7004
26 fields, 1 page
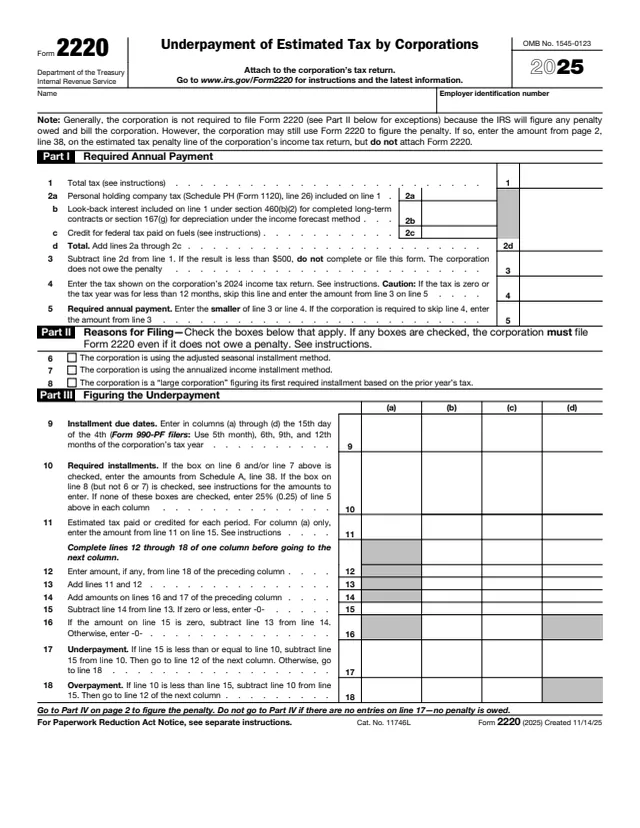
2220
322 fields, 4 pages
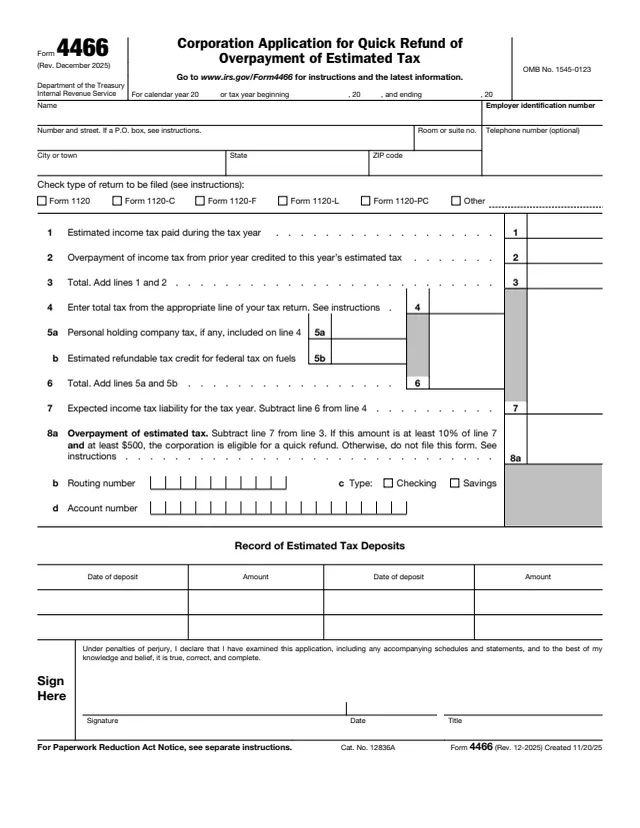
4466
43 fields, 1 page
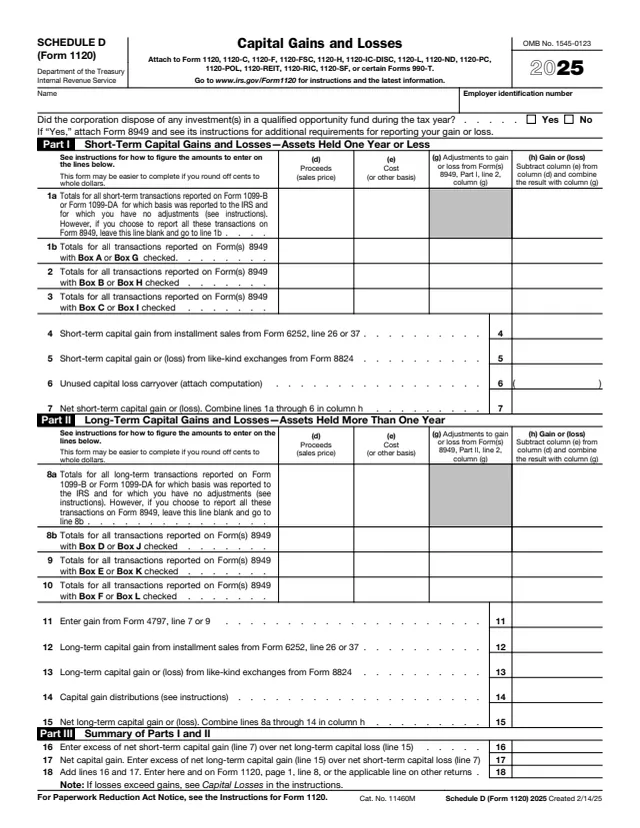
1120
48 fields, 1 page
SS-4
89 fields, 2 pages
The instructions say all section 468B designated and qualified settlement funds file an annual income tax return on Form 1120-SF.
No tool matches that search.
The instructions say the return is signed and dated by the administrator of the fund. A paid preparer also signs the paid preparer section.
Line 15 of the form says to multiply modified gross income on line 14 by 37% (0.37).
The instructions say a designated or qualified settlement fund uses the accrual method of accounting.
The instructions say amounts transferred to the fund by or on behalf of a transferor are generally excluded from income.
Yes. The instructions point to Form 7004, generally filed by the regular due date of the return.
The instructions say settlement funds created after May 17, 2006, to resolve or satisfy liabilities under CERCLA are exempt from tax, citing section 468B(g)(2).