Header and original return
Tax year ending month and year, name, EIN and address, the name and address used on the original return, and the IRS service center where it was filed.
1120-X
Amended U.S. Corporation Income Tax Return
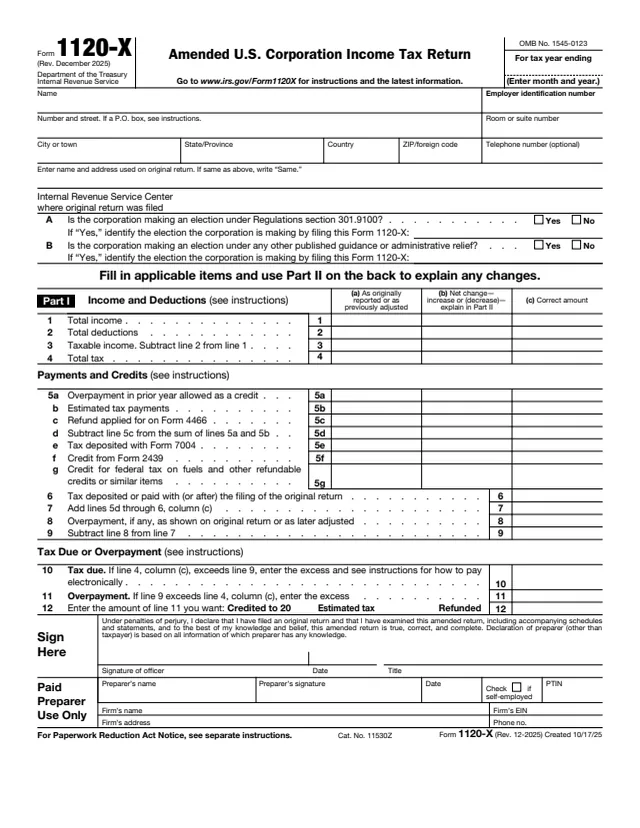
Form 1120-X is the Amended U.S. Corporation Income Tax Return. The IRS says corporations use it to correct a Form 1120 (or Form 1120-A, if applicable) as originally filed, or as later adjusted by an amended return, a claim for refund, or an examination, and to make certain elections after the prescribed deadline.
Part I compares income, deductions, tax and payments in three columns: as originally reported, the net change, and the correct amount. It then figures any tax due or overpayment. Part II on the back explains each change.
The instructions point to other forms for some cases: Form 4466 for a quick refund of overpaid estimated tax, Form 1139 for certain tentative refunds from carrybacks, and Form 3115 for a change in accounting method. You can fill out Form 1120-X free in your browser on this page and download the result without an account.
Tax year ending month and year, name, EIN and address, the name and address used on the original return, and the IRS service center where it was filed.
Yes or No questions on elections under Regulations section 301.9100 or other published guidance, with space to identify the election being made.
Total income, total deductions, taxable income and total tax, each shown as originally reported, as a net change, and as the correct amount.
Prior year overpayment credit, estimated tax payments, refund applied for on Form 4466, tax deposited with Form 7004, credit from Form 2439, other refundable credits and tax paid with the original return.
Tax due or overpayment, and how much of an overpayment is credited to estimated tax or refunded.
The line number and reason for each changed item, any computation in detail, and a box to check for net operating loss, capital loss or general business credit carrybacks.
Enter the ending month and year of the tax year being amended. If the original return used a different name or address, enter it, or write Same.
Enter amounts from the return as originally filed or as later amended. If the IRS changed or audited the return, the instructions say to enter the adjusted amounts.
Enter the net increase or decrease for each line being changed, with decreases in parentheses, and explain each one in Part II.
Add or subtract column (b) from column (a). Figure the new tax on line 4 from line 3, column (c), using Form 1120, Schedule J of the original return.
Enter the overpayment from the original return, even if it was credited to the next year's estimated tax. The instructions say an original refund is paid separately from any added refund.
Enter tax due or overpayment and the credit or refund choice on line 12, then an authorized officer signs. The instructions say the line 12 election is irrevocable.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file Form 1120-X at the Internal Revenue Service Center where the corporation filed its original return.
Generally within 3 years after the original return was filed or within 2 years after the tax was paid (for a refund claim), whichever is later. Carryback, bad debt and worthless security claims have other periods in the instructions.
The instructions say it often takes 3 to 4 months to process Form 1120-X.
Any schedule, statement or form that supports a corrected item, with the corporation's name and EIN on each. Form 8886 is attached for a year with a reportable transaction.
Attach copies of Form 1120, page 1, and the tax computation page for the year the loss or credit arose and the carryback year, with Copy Only, Do Not Process written at the top.
The instructions describe paying electronically through EFTPS, IRS Direct Pay or the IRS business tax account, or by check payable to the United States Treasury.

1120
481 fields, 6 pages
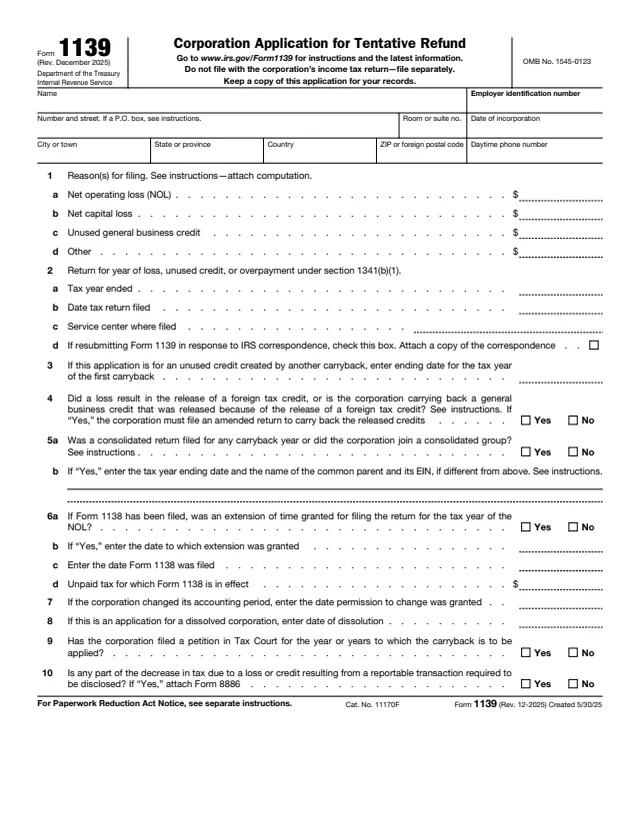
1139
162 fields, 2 pages
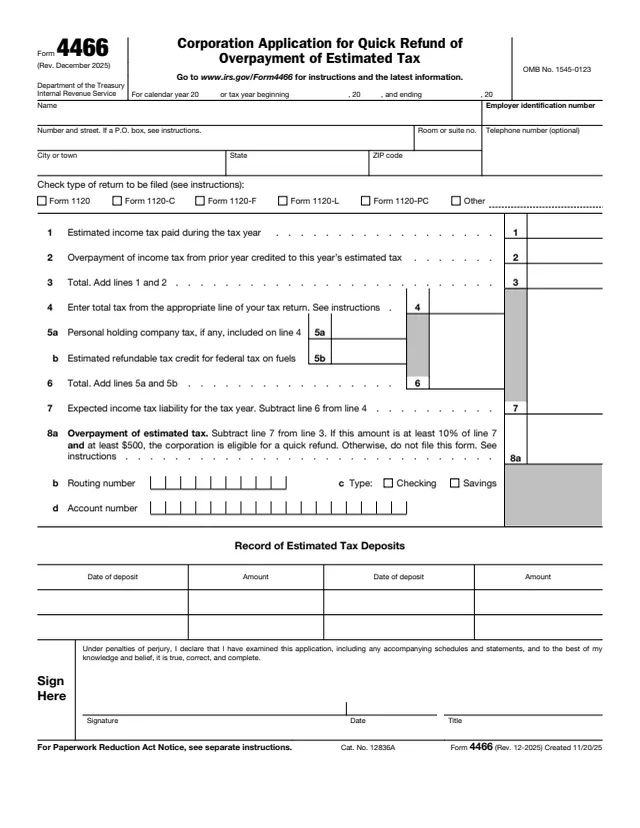
4466
43 fields, 1 page
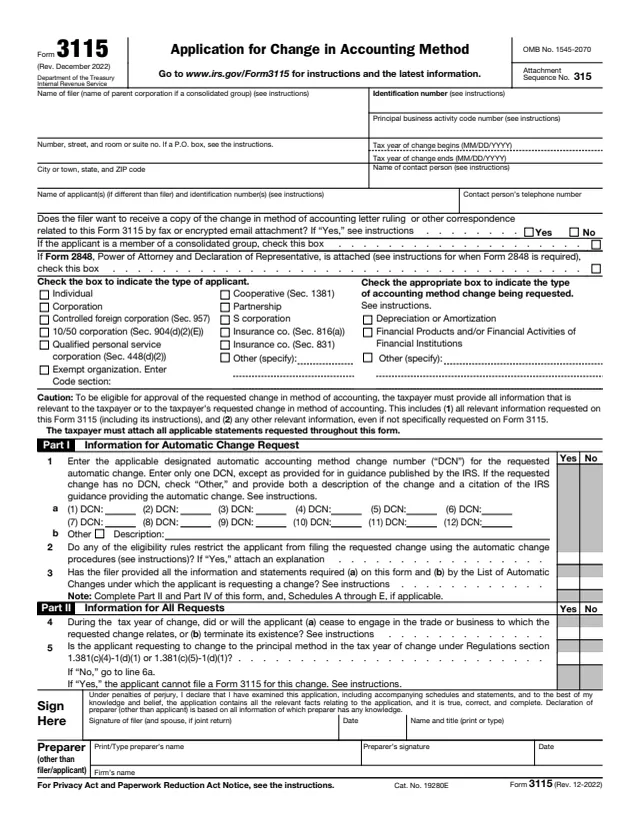
3115
294 fields, 8 pages
8886
98 fields, 2 pages

7004
26 fields, 1 page
A corporation files it after it has filed its original Form 1120. A corporate officer signs it, and a paid preparer also signs when one is paid to prepare it.
No tool matches that search.
The instructions say it corrects a Form 1120 (or Form 1120-A) as originally filed or as later adjusted, or makes certain elections after the prescribed deadline.
No. The instructions say to file Form 1120-X only after the corporation has filed its original return.
The instructions say it often takes 3 to 4 months to process Form 1120-X.
To the Internal Revenue Service Center where the corporation filed its original return, according to the instructions.
The instructions say Form 1139 is used for certain tentative refunds only if 1 year or less has passed since the tax year in which the carryback or adjustment occurred. Otherwise, Form 1120-X is used.
An authorized corporate officer, such as the president, treasurer or chief accounting officer. A receiver, trustee or assignee filing for the corporation signs instead.
The instructions say no interest is paid on the amount applied to the next period's estimated tax, and that election is irrevocable.