Items 1 to 5: the employer (borrower)
Name as used on the employment tax return, employer identification number, trade name, date the quarter ended and address.
4219
Statement of Liability of Lender, Surety, or Other Person for Withholding Taxes
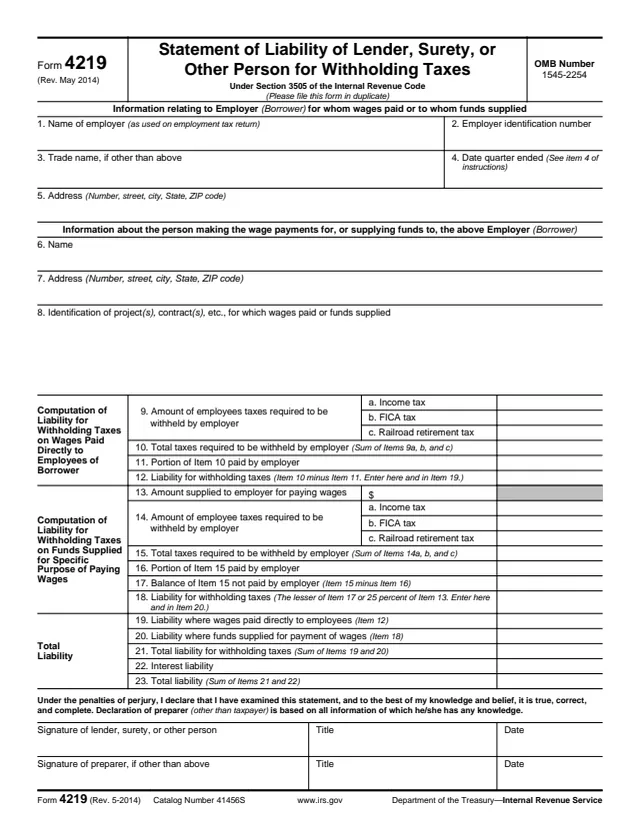
Form 4219, Statement of Liability of Lender, Surety, or Other Person for Withholding Taxes, is filed under section 3505 of the Internal Revenue Code. It is not an employer's own return. The form says it is filed by a lender, surety or other person who, by paying wages directly to employees of another employer, or by supplying funds for paying those wages, has incurred liability for taxes required to be withheld.
The statement covers income tax, FICA tax and railroad retirement tax required to be withheld from those wages, plus interest. Where funds were supplied for paying wages, the form says the liability cannot exceed 25% of the amount supplied for that purpose, and section 3505(b) does not apply to ordinary working capital loans. The employer remains liable for withholding taxes the lender, surety or other person does not pay.
A separate Form 4219 is filed, in duplicate, for each employer and each calendar quarter, with payment of the amount in item 23. You can fill out Form 4219 free in your browser on this page and download the result without an account.
Name as used on the employment tax return, employer identification number, trade name, date the quarter ended and address.
Name and address of the person who paid the wages or supplied the funds, and the projects or contracts for which they did so.
Income tax, FICA tax and railroad retirement tax required to be withheld, the portion the employer paid, and the resulting liability.
The amount supplied, the taxes required to be withheld, the portion the employer paid, and a liability equal to the lesser of the unpaid balance or 25 percent of item 13.
The two liabilities added together, interest liability and the total liability.
Signature, title and date of the lender, surety or other person under penalties of perjury, and of a preparer if other than above.
Enter the last day of the calendar quarter during which the wages were actually paid. If funds were supplied, use the quarter in which the employer actually paid the wages.
Enter in 9a, 9b and 9c the employee taxes required to be withheld as if the wages were paid by the employer.
Enter the gross amount, without reduction for withholding taxes, supplied to the employer for paying wages that were actually paid during the quarter.
Enter in 14a, 14b and 14c the employee taxes required to be withheld by the employer from wages paid during the quarter with the funds supplied.
Carry item 12 to item 19. For item 18, enter the lesser of item 17 or 25 percent of item 13 and carry it to item 20.
The form says interest is charged if the liability is paid after the due dates of the employer's federal employment tax return, at the annual rate set under section 6621(a), subject to section 6621(b).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file Form 4219 with the IRS office where the employer for whom wages were paid or funds were supplied files federal employment tax returns.
Include a check or money order for the amount in item 23, payable to the United States Treasury. Payment by either the employer or the lender, surety or other person satisfies the liability.
The form says that to avoid the accumulation of interest, payment is made on or before the due date of the employer's (borrower's) federal employment tax return.
File it in duplicate, with a separate Form 4219 for each employer and each calendar quarter for which liability under section 3505 is incurred.
If neither the employer nor the lender, surety or other person pays these taxes, the form says the U.S. Government may collect the unpaid amount by appropriate civil action.
941
116 fields, 3 pages
944
114 fields, 3 pages
943
109 fields, 3 pages
CT-1
80 fields, 3 pages
W-2
568 fields, 11 pages
The form is completed by a third party that paid or financed another employer's payroll, not by the employer or its employees.
No tool matches that search.
A lender, surety or other person who paid wages directly to another employer's employees, or supplied funds for paying them, and incurred liability under section 3505 of the Internal Revenue Code.
No. The form says an employer within the meaning of section 3401(d)(1) or (d)(2) does not use it to report income tax withholding. The employer stays liable for taxes not paid and files its employment tax return.
For funds supplied for paying wages, the form says the liability under section 3505(b) cannot exceed 25% of the amount supplied for that purpose.
No. The form says the liability does not extend to the employer's taxes under the Federal Insurance Contributions Act or the Railroad Retirement Tax Act.
The form says section 3505(b) does not apply to ordinary working capital loans to employers, even when it is known that part of the funds will be used to pay wages.
A separate Form 4219, in duplicate, for each employer and each calendar quarter in which liability is incurred.