Header
Schedule number, estate of, date of death and name of donee.
4808
Computation of Credit for Gift Tax
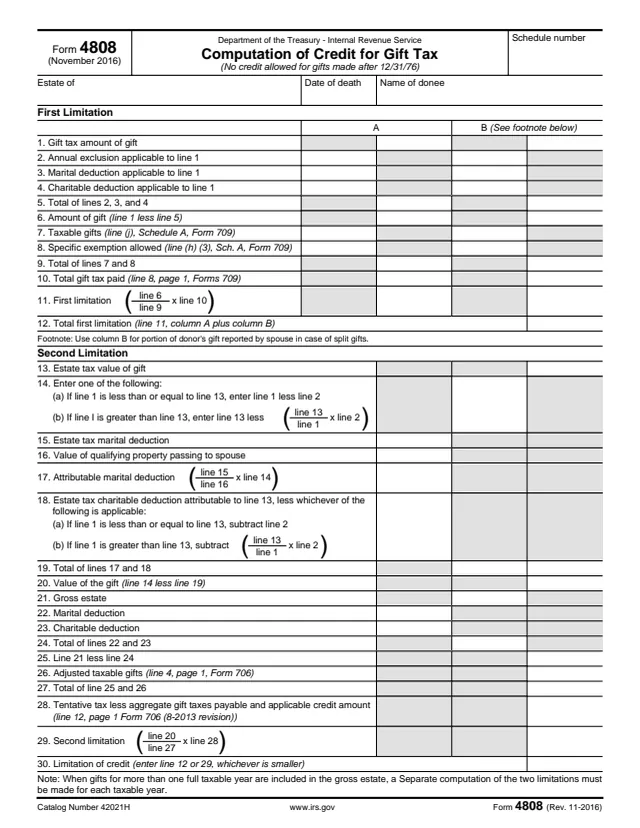
Form 4808, Computation of Credit for Gift Tax, is a one-page IRS form that works out a limitation of credit for gift tax for a decedent's estate. Its header asks for a schedule number, the name of the estate, the date of death and the name of the donee. A line under the title says no credit is allowed for gifts made after 12/31/76.
The form figures two limitations. The first works from gift tax figures: the gift, its annual exclusion and deductions, taxable gifts and total gift tax paid, with line references to Form 709. The second works from estate tax figures: the estate tax value of the gift, marital and charitable deductions, gross estate, adjusted taxable gifts and tentative tax, with line references to Form 706. Line 30 takes the smaller of the two.
The PDF prints no instructions, no OMB number and no filing address, and it does not say who completes it or where it goes. You can fill out the PDF free in your browser on this page and download it without an account.
Schedule number, estate of, date of death and name of donee.
The gift tax amount of the gift, the annual exclusion, marital and charitable deductions applicable to line 1, their total, and the amount of the gift, in columns A and B.
Taxable gifts and the specific exemption from Schedule A of Form 709, total gift tax paid from Forms 709, the line 11 formula and the total first limitation on line 12.
Estate tax value of the gift, the annual exclusion adjustment, the attributable estate tax marital and charitable deductions, and the value of the gift on line 20.
Gross estate, marital and charitable deductions, adjusted taxable gifts and tentative tax from page 1 of Form 706, and the second limitation on line 29.
Line 12 or line 29, whichever is smaller.
Enter the schedule number, the name of the estate, the date of death and the name of the donee.
Enter the gift and its exclusion and deductions on lines 1 to 5 and subtract on line 6. Lines 7, 8 and 10 take taxable gifts, the specific exemption and total gift tax paid from Form 709.
Line 11 is line 6 divided by line 9, times line 10. Use column B for the part of the donor's gift reported by the spouse, then add column A and column B on line 12.
Enter the estate tax value of the gift on line 13. Lines 14 and 18 each give two choices, depending on whether line 1 is less than or equal to line 13, or greater than line 13.
Enter the gross estate and deductions, adjusted taxable gifts from line 4, page 1, Form 706, and tentative tax from line 12, page 1, Form 706 (8-2013 revision). Line 29 is line 20 divided by line 27, times line 28.
Enter line 12 or line 29, whichever is smaller. If gifts from more than one full taxable year are in the gross estate, the note says to compute both limitations separately for each year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The PDF prints no filing address and does not say to attach it to a return. It carries a schedule number field at the top right.
The IRS PDF has no instructions and no OMB number. The only guidance printed on it is the footnote on split gifts and the note on gifts from more than one taxable year.
The form says no credit is allowed for gifts made after 12/31/76.
Line 28 points to line 12, page 1 of Form 706 in its 8-2013 revision. The form itself is Rev. 11-2016.
The form does not name who completes it or who receives it. It has no instructions, and nothing on the PDF says to attach it to a return. What the form does show is the situation it applies to.
No tool matches that search.
A limitation of credit for gift tax for an estate. Line 30 is the smaller of the first limitation on line 12 and the second limitation on line 29.
No. The form says no credit is allowed for gifts made after 12/31/76.
The PDF does not say. It has no instructions, no filing address and no OMB number, so this page does not state who completes it or who receives it.
The footnote says to use column B for the portion of the donor's gift reported by the spouse in case of split gifts.
Its line references point to Form 709 for taxable gifts, the specific exemption and gift tax paid, and to Form 706 for adjusted taxable gifts and tentative tax.