5471 Sch. J

Accumulated Earnings & Profits (E&P) of Controlled Foreign Corporation

Agency
IRS
Revision
Rev. December 2020
Fillable fields
282
Pages
3
Official source
IRS form page
Checked
October 21, 2026
Fill 5471 Sch. J online
Page 1 of form 5471 Sch. J

Schedule J (Form 5471): Accumulated E&P of Controlled Foreign Corporation

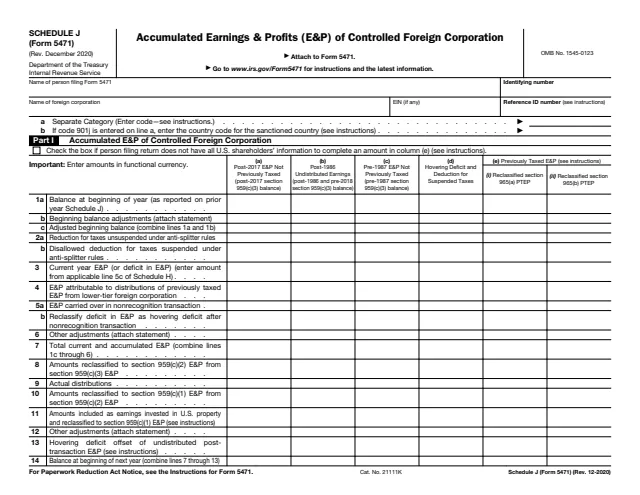
Schedule J (Form 5471) is titled Accumulated Earnings & Profits (E&P) of Controlled Foreign Corporation. The Instructions for Form 5471 say to use it to report a CFC's accumulated E&P in its functional currency, computed under sections 964(a) and 986(b), and also the E&P of specified foreign corporations that are only treated as CFCs for limited purposes under section 965(e)(2).

The schedule is not filed on its own. The form says "Attach to Form 5471." The IRS describes Form 5471 as the return that certain U.S. citizens and residents who are officers, directors, or shareholders in certain foreign corporations file to satisfy the reporting requirements of sections 6038 and 6046.

Part I follows the corporation's E&P from the opening balance through the year's changes to the closing balance, in columns for E&P not previously taxed, hovering deficits and suspended taxes, ten groups of previously taxed E&P (PTEP) and a total. Part II follows E&P subject to recapture as subpart F income. You can fill out this schedule free in your browser on this page and download the result without an account.

What's on Schedule J (Form 5471)

Heading and lines a and b

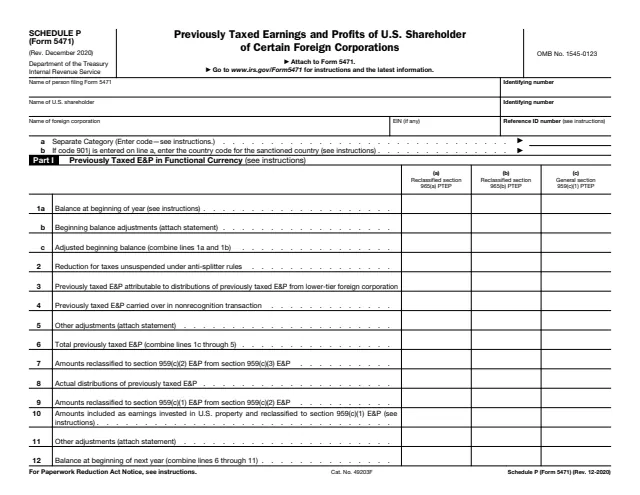
Name and identifying number of the person filing Form 5471, the foreign corporation's name, EIN and reference ID number, the separate category code on line a, and on line b a sanctioned country's code when line a shows 901j.

Part I, columns (a) to (d)

Post-2017 E&P not previously taxed, post-1986 undistributed earnings, pre-1987 E&P not previously taxed, and hovering deficit and deduction for suspended taxes.

Part I, columns (e) and (f)

Column (e) splits previously taxed E&P into ten groups, (i) through (x), such as section 965(a) PTEP and section 951A PTEP. Column (f) is total section 964(a) E&P.

Part I, lines 1a to 14

Beginning balance, adjustments, current year E&P from Schedule H, distributions, reclassifications between PTEP groups, other adjustments and the balance at the beginning of next year on line 14.

Part II

Nonpreviously taxed E&P subject to recapture as subpart F income under section 952(c)(2): beginning balance, additions, subtractions and balance at end of year on lines 1 through 4.

How to fill out Schedule J (Form 5471)

  1. 1

    Heading and line a

    Enter the person filing Form 5471 and, if applicable, the reference ID number shown on Form 5471, page 1, item 1b(2). On line a enter the separate category code. The instructions say to complete a separate Schedule J for each applicable separate category, using the categories listed in the Instructions for Form 1118.

  2. 2

    The TOTAL schedule

    The instructions say that a filer with more than one category of income also completes a separate Schedule J with the code TOTAL on line a, aggregating every line and column of Part I from all the other Schedules J. No separate Schedule J is completed for the section 951A category.

  3. 3

    Currency and the Part I box

    Enter amounts in the foreign corporation's functional currency as reported on Form 5471, page 1, item 1h. Check the box at the top of Part I if you do not have all U.S. shareholders' information needed for an amount in column (e).

  4. 4

    Lines 1a through 7

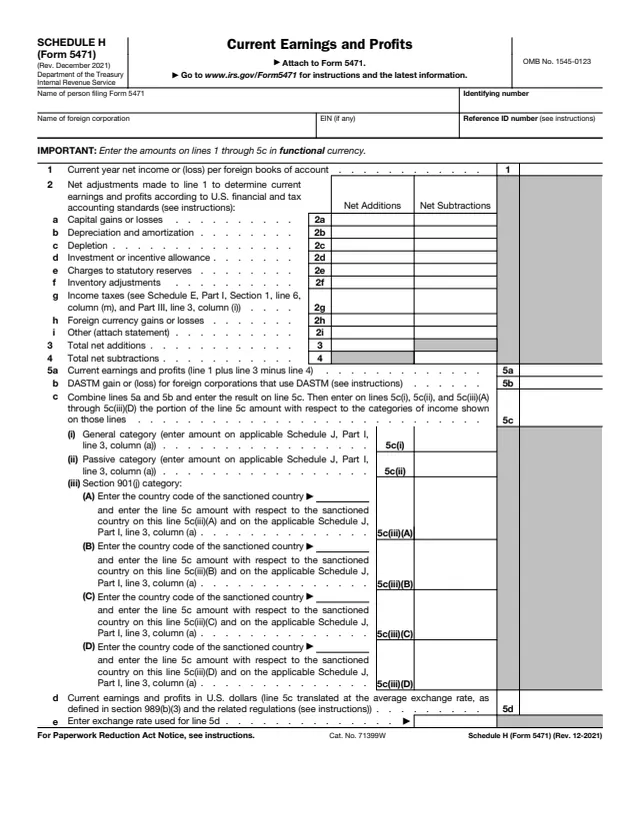
    Line 1a matches the ending balances on the prior year Schedule J. Line 1b holds differences, with an attached explanation. Line 3 comes from the applicable line 5c of Schedule H (Form 5471) and never has an amount in column (e). Line 7 combines lines 1c through 6.

  5. 5

    Lines 8 through 13

    Line 8 shows inclusions as negative amounts in columns (a) to (c) and positive amounts in columns (e)(vi) to (e)(x). Line 9 shows actual distributions as negative numbers. Lines 10 and 11 show reclassifications to section 959(c)(1) PTEP. Line 12 needs an attached statement.

  6. 6

    Line 14 and Part II

    Combine lines 7 through 13 for the balance at the beginning of next year. In Part II, enter the beginning balance, additions, subtractions and the balance at end of year.

Why fill Form 5471 Sch. J on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

Where it goes, matching amounts and penalties

Where it goes

Schedule J is attached to Form 5471. The instructions say to attach Form 5471 to your income tax return (or, if applicable, partnership or exempt organization return) and file both by the due date, including extensions, for that return.

Zero amounts

The instructions say a required schedule with all zero amounts is still filed with one or more zero amounts. For schedules completed by category, including Schedule J, one instance for any separate category meets the requirement.

Matching Schedule R

The instructions say the total of column (d) of Schedule R (Form 5471) equals line 9, column (f), of Schedule J, or of the Schedule J with code TOTAL when more than one is filed.

Penalties

The instructions note that a person required to file Form 5471 and Schedule J, M, or O who agrees to have another person file them may be subject to the listed penalties if the other person does not file a correct and proper form and schedule.

Who completes Schedule J (Form 5471)?

  • Form 5471 filers

    The IRS says certain U.S. citizens and residents who are officers, directors, or shareholders in certain foreign corporations file Form 5471 and its schedules. The Categories of Filers chart in the instructions shows which categories include Schedule J.

  • Sole owners of a CFC

    The instructions give the example of a sole owner of a CFC, described in Categories 4 and 5a, who completes all six pages of Form 5471 and separate Schedules E, G-1, H, H-1, I-1, J, M, P, Q, and R.

  • Consolidated groups

    The name of the person filing is generally the U.S. person in the applicable filer category. For a consolidated return, the instructions say to enter the name of the U.S. parent.

  • Filers who skip Schedule J

    The instructions say Categories 1b, 1c, 5b, and 5c filers are not required to file Schedule J for foreign-controlled section 965 SFCs or foreign-controlled CFCs.

The person filing Form 5471 for the foreign corporation completes Schedule J as part of that Form 5471. The instructions say to complete a separate Form 5471 and all applicable schedules for each applicable foreign corporation.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 5471 Sch. J

What is Schedule J (Form 5471) used for?

The instructions say it reports a CFC's accumulated E&P in its functional currency, computed under sections 964(a) and 986(b), and the E&P of specified foreign corporations treated as CFCs only for limited purposes under section 965(e)(2).

Is Schedule J filed separately?

No. The form says to attach it to Form 5471, and the instructions say Form 5471 is attached to the filer's income tax return and filed by that return's due date, including extensions.

What currency goes on Schedule J?

The functional currency of the foreign corporation as reported on Form 5471, page 1, item 1h. E&P of a qualified business unit with a different functional currency is translated into the foreign corporation's functional currency.

How many Schedules J are filed?

One for each applicable separate category of income, plus one with the code TOTAL when there is more than one category. The section 951A category does not get its own Schedule J.

Where does the amount on line 3 come from?

From the applicable line 5c of Schedule H (Form 5471). For example, the instructions say a passive category Schedule J uses Schedule H, line 5c(ii).

What if I do not know the other shareholders' amounts?

Check the box at the top of Part I. The instructions say amounts that cannot be determined as PTEP go in column (a), post-2017 E&P not previously taxed.