Part I: Identification
Plan year dates and boxes for a first, amended, final or short plan year return, extensions, a foreign plan, the Late Filer Penalty Relief Program and SECURE Act retroactive adoption.
5500-EZ
Annual Return of A One-Participant (Owners/Partners and Their Spouses) Retirement Plan or A Foreign Plan
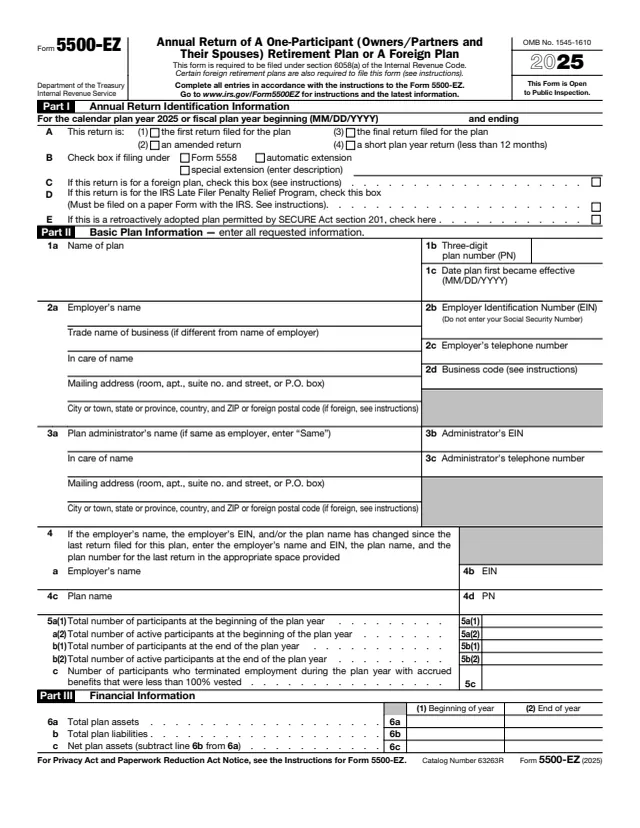
Form 5500-EZ is the Annual Return of A One-Participant (Owners/Partners and Their Spouses) Retirement Plan or A Foreign Plan. The IRS says it is used by one-participant plans and certain foreign plans that are not subject to the requirements of section 104(a) of ERISA, to satisfy annual reporting and filing obligations under Internal Revenue Code section 6058(a).
The instructions describe a one-participant plan as a retirement plan, other than an ESOP, that covers only the owner (or the owner and spouse) who owns the entire business, or only one or more partners (or partners and their spouses). A foreign plan is a pension plan maintained outside the United States primarily for nonresident aliens.
This page hosts the 2025 form, for plan years that started in 2025. It is filed on paper with the IRS or electronically through the EFAST2 filing system. You can fill out Form 5500-EZ free in your browser on this page and download the result without an account.
Plan year dates and boxes for a first, amended, final or short plan year return, extensions, a foreign plan, the Late Filer Penalty Relief Program and SECURE Act retroactive adoption.
Plan name, three-digit plan number and effective date, employer and administrator names, EINs, addresses and phone numbers, the business code, and any prior names on line 4.
Total and active participants at the beginning and end of the plan year, and participants who left during the year with accrued benefits less than 100% vested.
Total plan assets, liabilities and net assets at the beginning and end of the year, and contributions from employers, participants and others, including rollovers.
Two-character feature codes from the List of Plan Characteristics Codes in the instructions.
Participant loans, minimum funding questions for defined benefit and defined contribution plans, the pre-approved plan Opinion Letter date and serial number, and the signature.
Enter the calendar or fiscal plan year dates as MM/DD/YYYY and check the line A boxes that apply, such as first, amended, final or short plan year return.
Enter the plan's formal name, its three-digit plan number (numbered starting with 001) and the employer's EIN. The instructions say not to enter a social security number.
If the administrator is the employer on line 2a, the instructions say to enter Same on line 3a and leave the rest of line 3a and lines 3b and 3c blank.
Count participants on lines 5a to 5c. Report assets in whole dollars, with beginning of year amounts the same as the end of year amounts on the prior year's return.
Enter plan characteristic codes on line 8, which the instructions say not to leave blank, then answer the loan and funding questions on lines 9 to 12.
The plan administrator or employer (owner) signs and dates the paper form and types or prints the name of the person signing.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 5500-EZ is filed by the last day of the 7th calendar month after the end of the plan year. If that falls on a Saturday, Sunday, or legal holiday, it may be filed on the next day that is not.
Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0020. Private delivery services use Internal Revenue Submission Processing Center, 1973 Rulon White Blvd., Ogden, UT 84201.
The form can be filed through EFAST2. The instructions say a filer required to file at least 10 returns of any type with the IRS during the calendar year files Form 5500-EZ electronically.
Form 5558 filed by the normal due date gives a one-time extension of up to 2½ months. An automatic extension to the employer's extended income tax due date applies when the instructions' conditions are met.
The instructions say Code section 6652(e) imposes a penalty of $250 a day, up to a maximum of $150,000 per plan year, for not filing by the required due date.
The instructions list the IRS Help Desk at 877-829-5500 and the EFAST2 Help Desk at 1-866-GO-EFAST (1-866-463-3278).
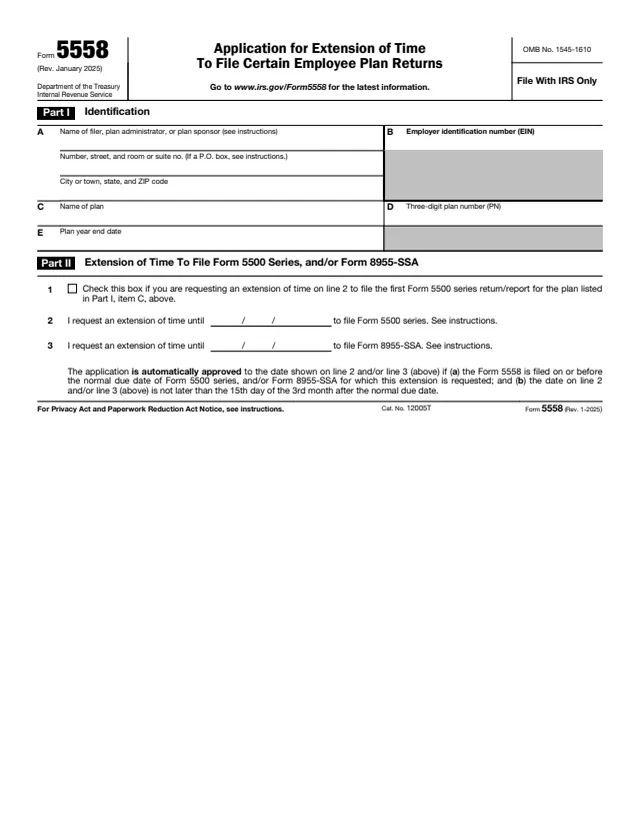
5558
13 fields, 3 pages
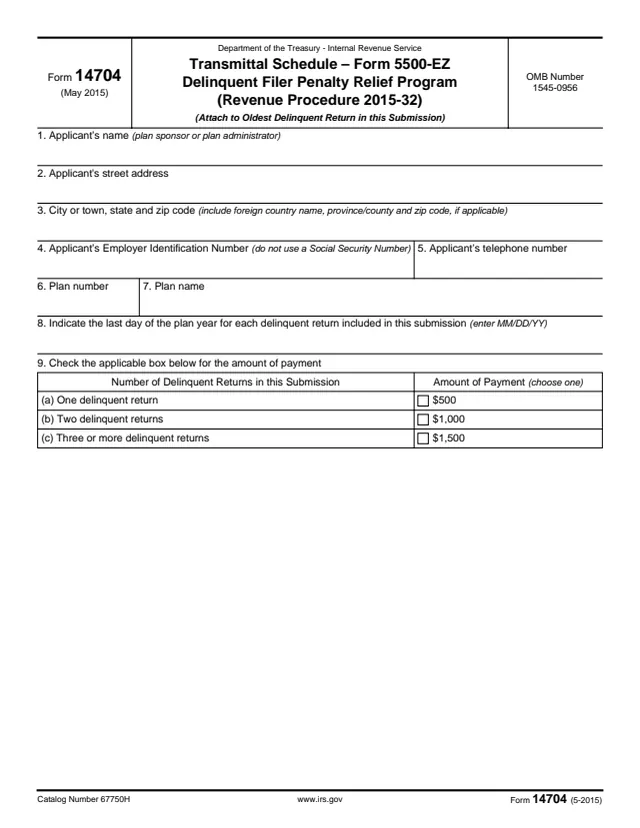
14704
11 fields, 1 page
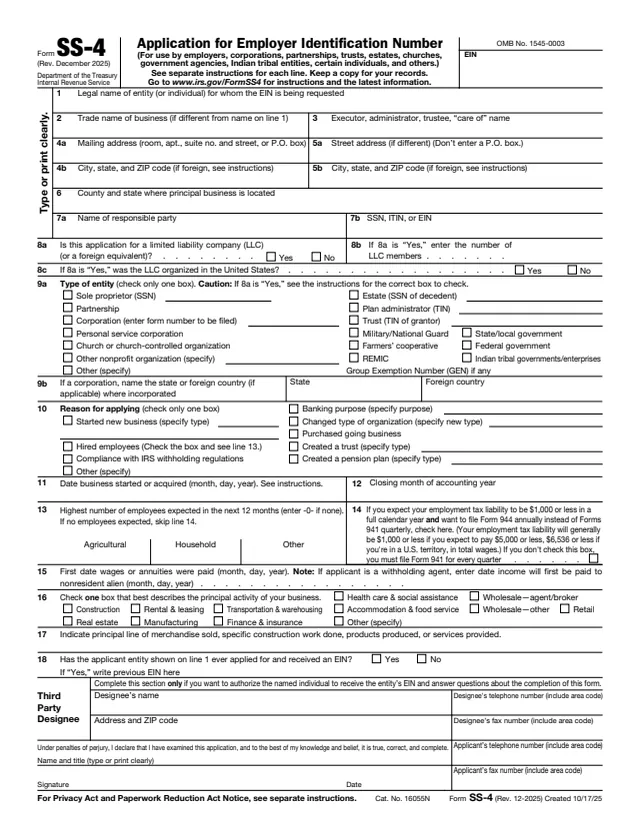
SS-4
89 fields, 2 pages
8822-B
22 fields, 2 pages
The employer or plan administrator of a one-participant plan or foreign plan files it, and the plan administrator or employer (owner) signs the paper form.
No tool matches that search.
The IRS says one-participant plans and certain foreign plans that are not subject to section 104(a) of ERISA use it to meet annual reporting obligations under section 6058(a).
The instructions say a one-participant plan does not have to file for 2025 if the total assets of all the employer's one-participant plans do not exceed $250,000 at the end of the plan year, unless 2025 is the final plan year.
By the last day of the 7th calendar month after the end of the plan year, according to the instructions. Form 5558 can extend it once by up to 2½ months.
Yes, through the EFAST2 filing system. The instructions say filers required to file at least 10 returns of any type with the IRS during the calendar year file it electronically.
The instructions say they are not filed with Form 5500-EZ, but completed schedules that apply are kept with the plan's records.
The instructions say Form 5500-EZ information is required to be made available to the public, but information for a one-participant or foreign plan will not be published on the internet.
The instructions cite $250 a day, up to a maximum of $150,000 per plan year, under Code section 6652(e).