Organization details
Name of organization, employer identification number, street address or P.O. box, room or suite, and city, state and ZIP + 4.
5768
Election/Revocation of Election by an Eligible Section 501(c)(3) Organization To Make Expenditures To Influence Legislation
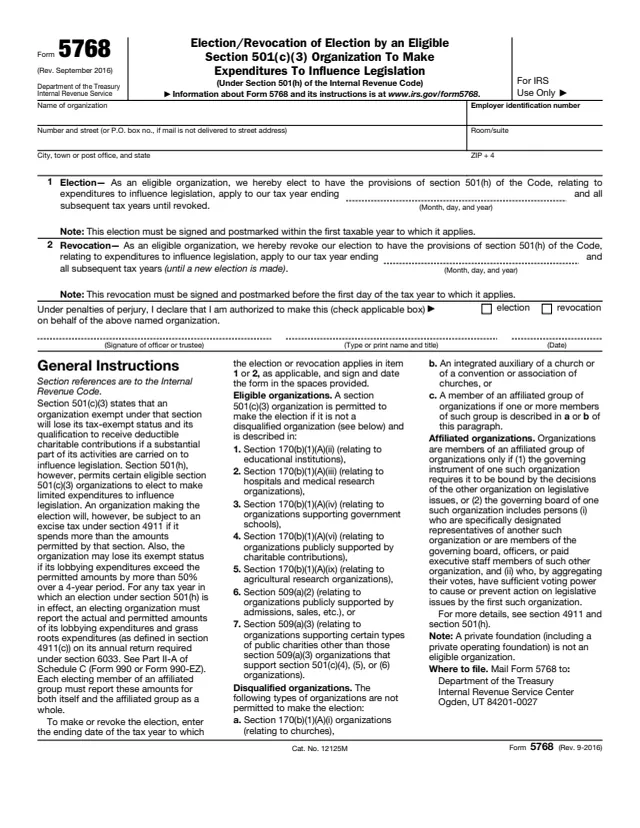
Form 5768 is the one-page form an eligible section 501(c)(3) organization uses to elect, or to revoke its election, to have section 501(h) of the Internal Revenue Code apply to its expenditures to influence legislation. The IRS About page says it is used by eligible organizations who either elect to use or revoke their election to use those provisions.
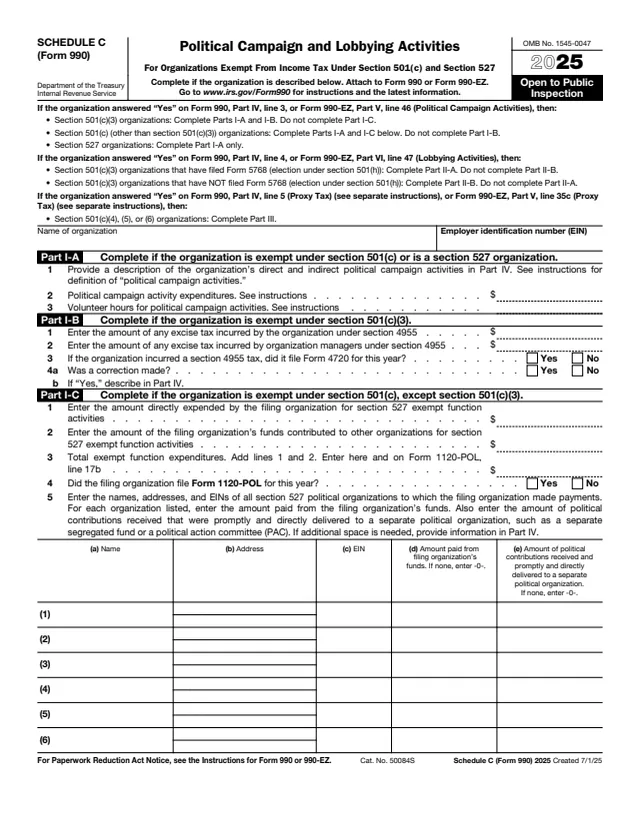
The form explains the background. Section 501(c)(3) says an organization loses its exemption if a substantial part of its activities is carried on to influence legislation, while section 501(h) permits certain eligible organizations to elect to make limited expenditures to influence legislation. The form says an electing organization is subject to an excise tax under section 4911 if it spends more than the permitted amounts, and reports its lobbying and grass roots expenditures in Part II-A of Schedule C (Form 990 or Form 990-EZ).
The filer is the organization, and an officer or trustee signs. The general instructions are printed on the form itself. You can fill out the PDF free in your browser on this page and download it without an account.
Name of organization, employer identification number, street address or P.O. box, room or suite, and city, state and ZIP + 4.
A statement electing to have section 501(h) apply to the tax year ending on the date entered and all later tax years until revoked.
A statement revoking the election for the tax year ending on the date entered and all later tax years, until a new election is made.
A check box for election or revocation, the signature of an officer or trustee, the printed name and title, and the date.
Printed below the form: eligible and disqualified organizations, affiliated organizations, the reporting on Schedule C, and where to file.
Fill in the organization's name, employer identification number and mailing address at the top of the form.
The form says to enter the ending date of the tax year to which the election or revocation applies in item 1 or 2, as applicable.
In the signature declaration, check the box that matches the line completed: election or revocation.
An officer or trustee signs, types or prints their name and title, and dates the form.
Mail the form to the IRS address printed in the instructions, keeping the postmark timing in the notes on lines 1 and 2 in mind.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to mail Form 5768 to Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0027.
The note on line 1 says the election must be signed and postmarked within the first taxable year to which it applies.
The note on line 2 says the revocation must be signed and postmarked before the first day of the tax year to which it applies.
The form says that for any tax year in which the election is in effect, the organization reports the actual and permitted amounts of its lobbying and grass roots expenditures on its annual return, in Part II-A of Schedule C (Form 990 or Form 990-EZ).
The form says each electing member of an affiliated group reports these amounts for both itself and the affiliated group as a whole. It refers to section 4911 and section 501(h) for details.
The form is completed by the organization, not by an individual. The signature line is for an officer or trustee, who declares under penalties of perjury that they are authorized to make the election or revocation on the organization's behalf.
No tool matches that search.
It records an eligible section 501(c)(3) organization's election to have section 501(h) apply to its expenditures to influence legislation, or its revocation of that election.
The form says a private foundation, including a private operating foundation, is not an eligible organization.
The form lists section 170(b)(1)(A)(i) organizations, which relate to churches, among the disqualified organizations that are not permitted to make the election.
Line 1 says the election applies to the tax year ending on the date entered and all subsequent tax years until revoked.
The form says an electing organization is subject to an excise tax under section 4911 if it spends more than the permitted amounts, and may lose its exempt status if its lobbying expenditures exceed the permitted amounts by more than 50% over a 4-year period.
On the organization's annual return, in Part II-A of Schedule C (Form 990 or Form 990-EZ), according to the form.