Employer details
Name of employer and employer identification number at the top of the census.
6088
Distributable Benefits From Employee Pension Benefit Plans
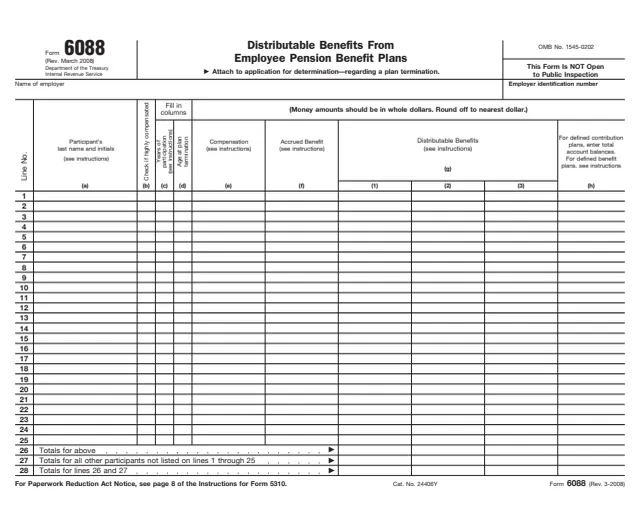
Form 6088, Distributable Benefits From Employee Pension Benefit Plans, is a participant census that goes with an application for an IRS determination letter about a plan termination. The IRS says it uses the information on this form to analyze an application for a determination letter on the qualification of the plan upon termination.
The form says it is attached to Form 5310, Application for Determination for Terminating Plans, or Form 5300, Application for Determination for Employee Benefit Plan, whichever applies. It lists participants with their years of participation, age, compensation, accrued benefit, distributable benefits and account balances or present value of benefit liabilities.
The form says it is NOT open to public inspection. This page has the Rev. March 2008 edition, with its instructions printed on page 2. You can fill it out free in your browser on this page and download the result without an account.
Name of employer and employer identification number at the top of the census.
Participant's last name and initials, and a check box for a participant who is highly compensated.
Years of participation, age at plan termination, compensation and accrued benefit. The instructions mark columns (c), (d) and (f) as defined benefit plans only.
Distributable benefits split into (g)(1), (g)(2) and (g)(3), allocated differently for defined contribution plans and underfunded defined benefit plans.
For defined contribution plans, total account balances. For defined benefit plans, the present value of the participant's total benefit liabilities.
Twenty-five participant lines, totals for them on line 26, totals for all other participants not listed on line 27, and combined totals on line 28.
Prepare the participant census as of the date of plan termination or proposed date of plan termination. The form says money amounts are in whole dollars, rounded to the nearest dollar.
First list anyone who, during the 5-year period before termination, owned directly or indirectly 5% or more of the voting stock or of the business. Then list the rest by current compensation, highest-paid first.
Underfunded defined benefit plans complete columns (a) through (h) for all participants. Other defined benefit plans complete all columns except (g)(1), (g)(2) and (g)(3). Underfunded defined contribution plans complete only (a), (b), (e), (g)(1), (g)(3) and (h).
Check (b) for a highly compensated employee under section 414(q), or enter NA. For compensation, use the current 12-month period for a defined contribution plan, or average compensation for the high 3 years for a defined benefit plan.
Split distributable benefits as the instructions describe for each plan type. Attach an explanation if the sum of column (g) or column (h) does not equal line 20(I) of Form 5310, and a statement of how present values were determined.
Where all participants are required, attach additional sheets in the same format as Form 6088. For other defined benefit plans, submit only the first 25 under the column (a) priorities.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to the application for determination regarding a plan termination: Form 5310 or Form 5300, whichever applies.
The form says that under section 6104(a)(1)(C) it will not be made available to the public, plan participants or other employees of the employer who established the plan.
A separate Form 6088 is filed for each employer in a section 413(c) multiple employer plan, and for each employer with noncollectively bargained employees in a collectively bargained underfunded plan that is required to file it.
The instructions ask for separate schedules when the accrued benefit is based on credited service or compensation that differs from what the columns ask for, and a detailed calculation when top-heaviness, section 415 limitations or offsets change it.
The form says a plan sponsor or administrator completes it. Plan participants are listed on it but do not file it.
No tool matches that search.
No. The form says a plan sponsor or administrator attaches it to Form 5310 or Form 5300 when applying for a determination letter on a plan termination.
No. The form says it will not be made available to the public, plan participants or other employees of the employer who established the plan.
The form says compensation for columns (a) and (e) means section 415 compensation as defined in Regulations section 1.415(c)-2.
When information is required for all participants, the form says to attach additional sheets in the same format. For other defined benefit plans, only the first 25 under the column (a) priorities are submitted.
The form says it is generally a defined contribution plan in which the sum of the account balances exceeds the plan's assets available to provide the benefits.
The form says to see page 8 of the Instructions for Form 5310.