Part I, lines 1 to 5: decedent
The decedent's name, Social Security number, country of citizenship and country of legal residence (domicile) at death, date of death and last address.
706-CE
Certificate of Payment of Foreign Death Tax
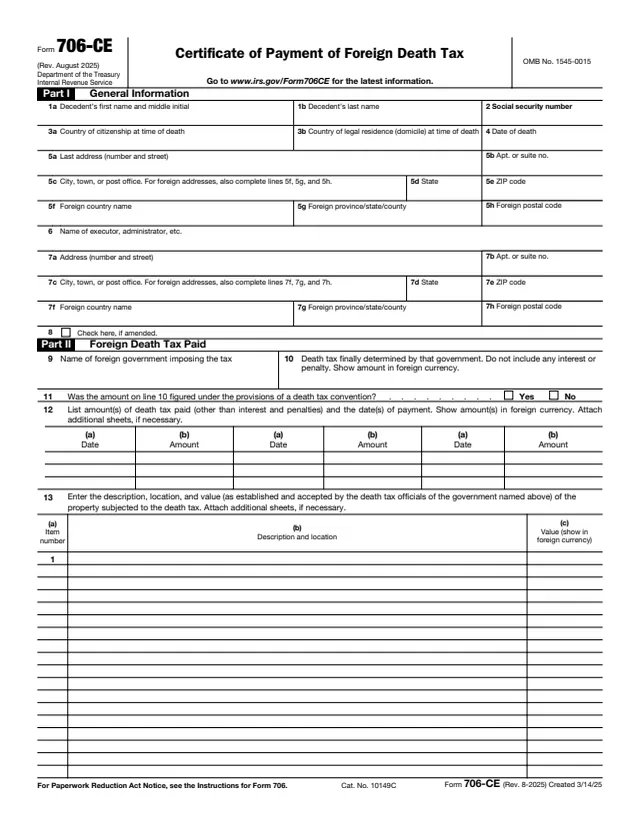
Form 706-CE, Certificate of Payment of Foreign Death Tax, documents death tax that a foreign government imposed on a decedent's property. The form says "The executor of the decedent's estate must file Form 706-CE before the IRS can allow a credit for foreign death taxes claimed on Form 706, United States Estate (and Generation-Skipping Transfer) Tax Return." It points to the instructions for Schedule P (Form 706) for how the credit is figured.
The executor fills in Parts I and II with details about the decedent, the foreign tax, the payments and the taxed property, and signs under penalties of perjury. Part III is for an authorized tax official of the foreign government, who certifies the information so a certified copy reaches the IRS.
You can fill out Form 706-CE free in your browser on this page and download the result without an account.
The decedent's name, Social Security number, country of citizenship and country of legal residence (domicile) at death, date of death and last address.
The name and address of the executor, administrator, etc., with foreign address fields, and a box to check if the certificate is amended.
The foreign government imposing the tax, the death tax finally determined in foreign currency without interest or penalty, whether a death tax convention applied, and each payment date and amount.
Item number, description and location, and value in foreign currency of the property subjected to the death tax, as established and accepted by the foreign death tax officials.
Whether a refund was claimed or allowed, an explanation of pending credits, multiple rates or multiple inheritances, and whether a further refund or credit will be claimed.
Signature, title, government and date of the authorized foreign tax official, certifying the information on lines 9 through 15 without exception or except as indicated.
Enter the decedent's details on lines 1 to 5 and the executor's name and address on lines 6 and 7. For foreign addresses, also complete lines 5f to 5h and 7f to 7h. Check line 8 only for an amended certificate.
Name the foreign government, enter the death tax finally determined in foreign currency without interest or penalty, and answer whether it was figured under a death tax convention.
List each payment date and amount, then describe each taxed property item with its location and value, all in foreign currency. Attach additional sheets if needed.
Answer the refund question on line 14 and check the statement that applies, explain any pending credit, multiple rates or multiple inheritances on line 15, and answer line 16.
The executor, administrator, etc. signs and dates under penalties of perjury.
The form says to send the original and one copy to the foreign government to which the tax was paid, ask that office to certify it and send it to the IRS, and keep the third copy.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form lists Internal Revenue Service Center, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915 for Form 706-CE and amended Form 706-CE.
The foreign government office is asked to certify the form and send it to the IRS. If that government refuses, the form says the executor files it directly with the IRS center.
The form says to complete everything except Part III and attach a statement under penalties of perjury explaining why, a copy of the foreign death tax return and the receipt or canceled check for the payment.
The form says a private delivery service can send Form 706-CE to the address above. The current list of designated services is at www.irs.gov/PDS.
The form says the person receiving a refund notifies the IRS service center within 30 days and pays any additional federal estate tax due. Regulations section 20.2016-1 describes the notice.
Of the three copies prepared for each country, the form says to keep the third copy for your records.

706
316 fields, 5 pages
706 Sch. P
26 fields, 1 page
706-NA
259 fields, 3 pages
706-A
464 fields, 5 pages
The executor fills in and signs Parts I and II. An authorized tax official of the foreign government signs Part III.
No tool matches that search.
The form says the executor of the decedent's estate files it before the IRS can allow a credit for foreign death taxes claimed on Form 706.
An authorized tax official of the foreign government imposing the death tax. That official certifies the information on lines 9 through 15.
The form says to prepare three copies for each foreign country's death tax for which credit is claimed. The original and one copy go to the foreign government, and the third copy is kept for your records.
The form says the executor files it directly with the IRS center, completes everything except Part III, and attaches a statement, a copy of the foreign death tax return and proof of payment.
The form asks for the death tax on line 10, the payments on line 12 and the property values on line 13 in foreign currency.
The form points to the instructions for Schedule P (Form 706), section 2014 and the related regulations for the credit for foreign death taxes, including how to figure it.