Part I: Passive Activity Credits
Lines 1 to 4 total current and prior year unallowed credits from Worksheets 1 to 4 by type. Line 6 holds the tax attributable to net passive income, and line 7 subtracts it from the line 5 total.
8582-CR
Passive Activity Credit Limitations
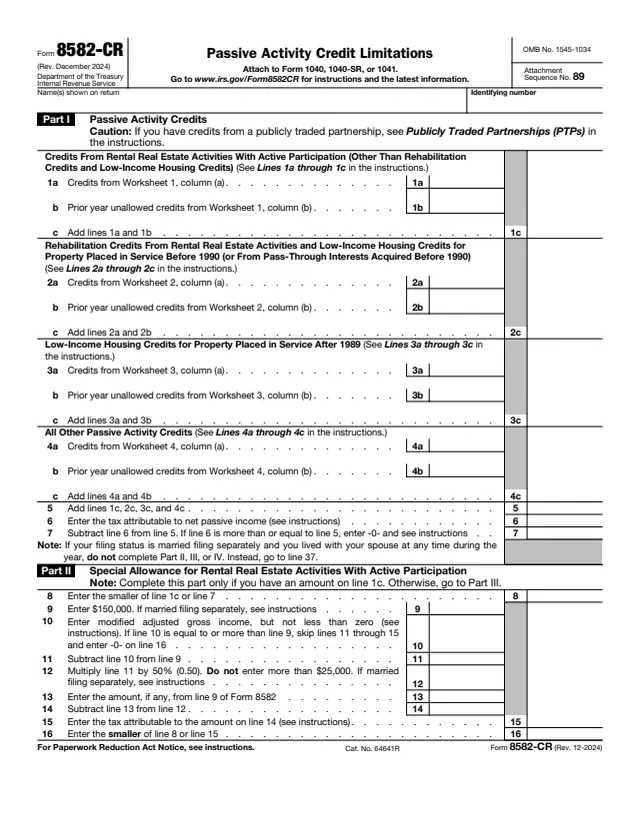
Form 8582-CR, Passive Activity Credit Limitations, is used by noncorporate taxpayers to figure the amount of any passive activity credit (PAC) for the current tax year, including any prior year unallowed credits, and the amount of credit allowed for the current year. It is also used to make the election to increase the basis of credit property when a taxpayer disposes of an interest in an activity.
The form attaches to Form 1040, 1040-SR or 1041. The instructions say credits that are not allowed in the current year are carried forward until they are allowed against the tax on net passive income or the special allowance, if applicable. Corporations subject to the passive activity rules use Form 8810 instead.
This page holds the December 2024 revision. You can fill out the PDF free in your browser on this page and download the result without an account.
Lines 1 to 4 total current and prior year unallowed credits from Worksheets 1 to 4 by type. Line 6 holds the tax attributable to net passive income, and line 7 subtracts it from the line 5 total.
For credits from rental real estate activities with active participation. It starts from $150,000 on line 9 and compares modified adjusted gross income on line 10.
The special allowance for rehabilitation credits from rental real estate and low-income housing credits for property placed in service before 1990. Line 21 starts from $250,000.
The special allowance for low-income housing credits for property placed in service after 1989, on lines 31 to 36.
Line 37 adds lines 6, 16, 30 and 36 to give the passive activity credit allowed.
A box to elect to increase the basis of credit property after disposing of an entire interest in a fully taxable transaction, with the activity name, property description and unallowed credit amount.
The instructions say to convert current year qualified expenditures into credits first, separate them by activity and by type, and enter credits from Form 3800, lines 2, 23 and 32, in column (a) of the matching worksheet.
Enter them in column (b) of the worksheets. With one credit type from one activity, the instructions say it is line 5 minus line 37 of the prior year Form 8582-CR.
Figure the tax on net passive income with the instructions' line A to E computation and enter it on line 6. If line 7 is zero, the instructions say all credits are allowed: enter line 5 on line 37.
Complete each part only when the form says so: Part II with an amount on line 1c, Part III with line 2c, Part IV with line 3c. The form says a married person filing separately who lived with their spouse at any time skips to line 37.
Add lines 6, 16, 30 and 36. With one credit type, line 37 is the credit allowed. With more, Worksheets 5 to 9 allocate allowed and unallowed credits, and allowed general business credits go on Form 3800.
Check line 38 to make the basis election, then name the activity and describe the property and the unallowed credit. The instructions say the election is not available on a partial disposition or a disposition to a related party.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1040, 1040-SR or 1041. Its attachment sequence number is 89.
Worksheets 1 to 9 in the instructions are marked keep for your records and are not filed with the form.
The instructions say to keep a record of each unallowed credit and the activity it belongs to, so the credit can be claimed if it becomes allowable in a future year.
The instructions say $75,000 goes on line 9 instead of $150,000, and no more than $12,500 on line 12, for spouses filing separately who lived apart at all times during the year.
The form points to the Publicly Traded Partnerships (PTPs) section of the instructions for credits from a PTP, which has its own computation.
8582
205 fields, 3 pages
8810
20 fields, 1 page

3800
1,921 fields, 9 pages
8834
11 fields, 2 pages

1040
199 fields, 2 pages

1041
173 fields, 3 pages
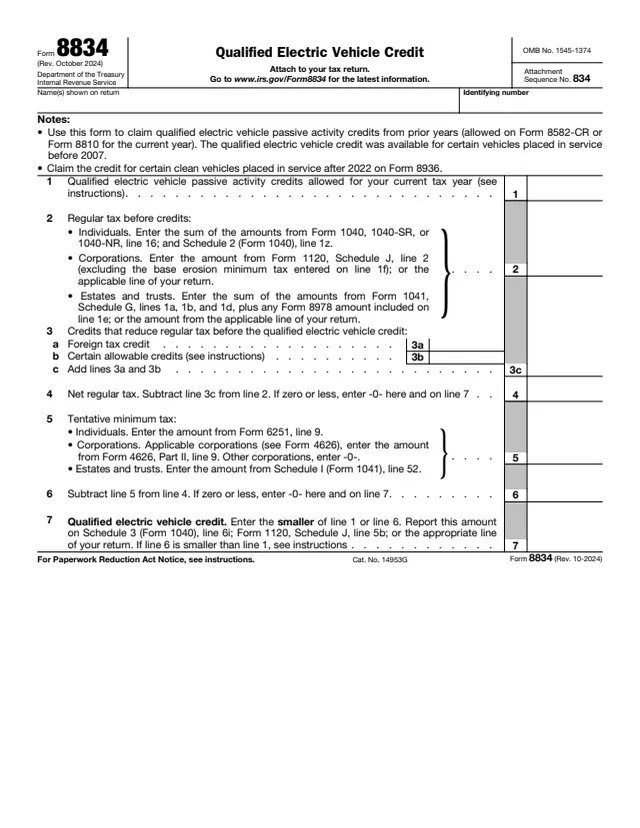
The instructions say Form 8582-CR is filed by individuals, estates and trusts with general business credits or the qualified plug-in electric and electric vehicle credit from passive activities.
No tool matches that search.
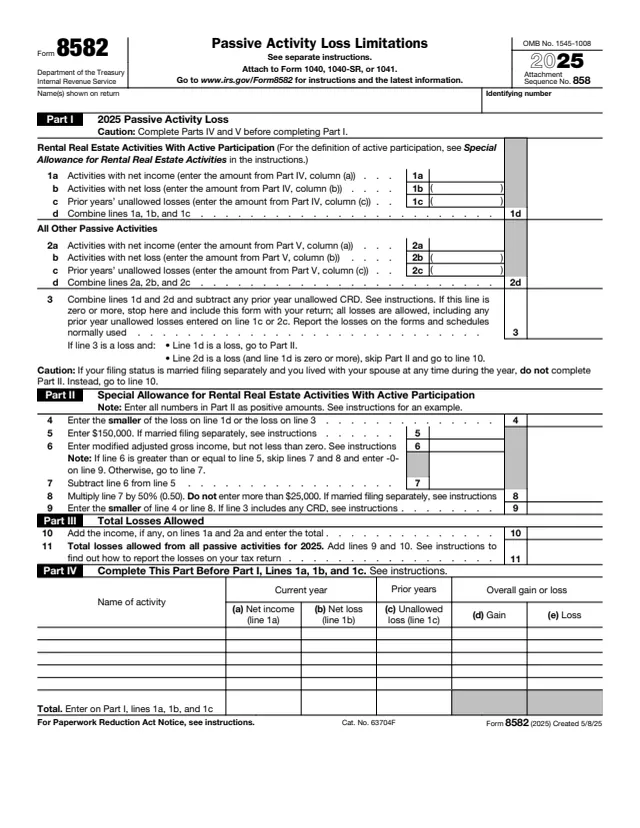
Form 8582 is Passive Activity Loss Limitations. Form 8582-CR is Passive Activity Credit Limitations, and line 13 of Form 8582-CR uses the amount from line 9 of Form 8582.
The instructions list general business credits and the qualified plug-in electric and electric vehicle credit from passive activities, for individuals, estates and trusts.
The instructions say passive activity credits not allowed in the current year are carried forward until they are allowed against the tax on net passive income or the special allowance, if applicable.
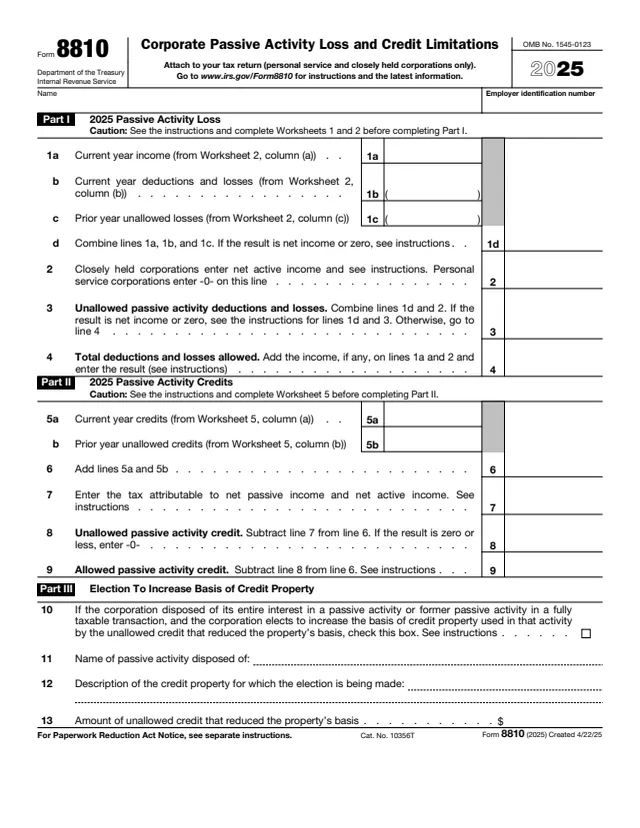
No. The instructions say corporations subject to the passive activity rules use Form 8810.
It records the election to increase the basis of credit property by the unallowed credit that reduced it, after a fully taxable disposition of an entire interest in a passive activity.