Part I, lines 1a to 1t
ECTI allocable to corporate partners, non-corporate partners, 28% rate gain, unrecaptured section 1250 gain and adjusted net capital gain, each with reductions for state and local taxes and Form 8804-C items.
8804-W
Installment Payments of Section 1446 Tax for Partnerships
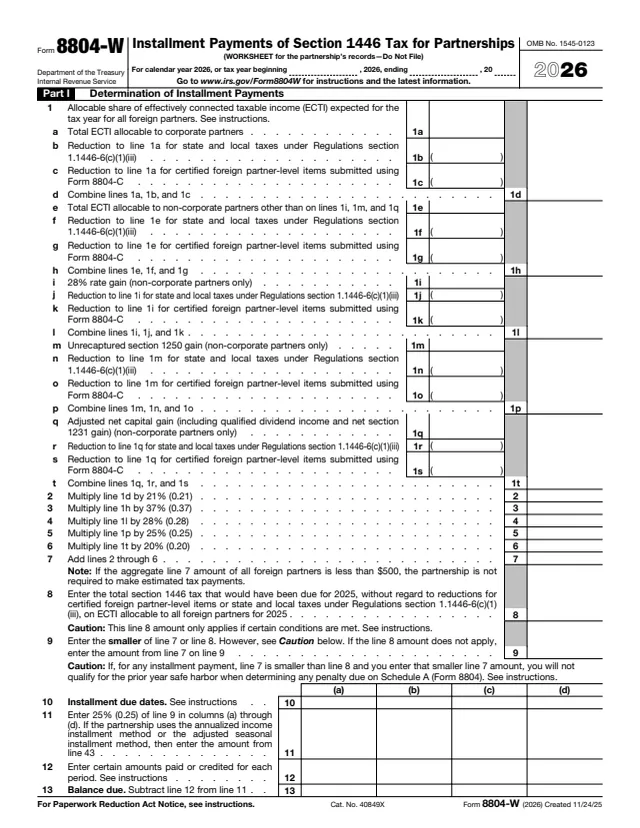
Form 8804-W (WORKSHEET), Installment Payments of Section 1446 Tax for Partnerships, is a four-page worksheet for calendar year 2026 or a tax year beginning in 2026. The IRS About page says partnerships that have effectively connected taxable income (ECTI) allocable to foreign partners can use it to determine the proper estimated section 1446 tax payments.
The form is marked as a worksheet "for the partnership's records" and says "Do Not File." The instructions say "Your use of this form is optional." They also say partnerships generally make installment payments of estimated section 1446 tax if the aggregate tax on the ECTI allocable to all foreign partners will be $500 or more, due by the 15th day of the 4th, 6th, 9th, and 12th months of the partnership's tax year.
You can fill out Form 8804-W free in your browser on this page and download it without an account.
ECTI allocable to corporate partners, non-corporate partners, 28% rate gain, unrecaptured section 1250 gain and adjusted net capital gain, each with reductions for state and local taxes and Form 8804-C items.
Lines 2 to 6 multiply by 21%, 37%, 28%, 25% and 20%. Line 7 is the current-year amount, line 8 the prior-year safe harbor, and line 9 the smaller of the two.
Four installment columns with the due dates, 25% of line 9 (or the line 43 amount), amounts paid or credited for each period, and the balance due.
Lines 14 to 29 use ECTI for tax years beginning in 2023, 2024 and 2025. The form says to use it only if the base period percentage for any 6 consecutive months is at least 70%.
Lines 30 to 36 annualize ECTI for each period, apply the same five rates, and multiply by the applicable percentages of 25%, 50%, 75% and 100%.
Lines 37 to 43 take the Part II or Part III amounts, adjust for earlier columns and give the required installment on line 43, which also goes on line 11.
Enter ECTI allocable to foreign partners by category, then the reductions. The instructions say not to enter a negative number on lines 1a, 1e, 1i, 1m or 1q, and to net losses against the matching category.
The instructions say to complete it only if the prior tax year was 12 months, the prior-year partnership return was timely filed, and prior-year ECTI is not less than 50% of the ECTI expected for the current year.
Enter the smaller of line 7 or line 8, or line 7 if line 8 does not apply. The form cautions that entering a smaller line 7 amount ends the prior-year safe harbor for Schedule A (Form 8804).
Enter the 15th day of the 4th, 6th, 9th, and 12th months of the tax year, or the next business day after a weekend or legal holiday. Line 11 is 25% of line 9, or line 43 when Part II or III is used.
Include any 2025 overpayment credited to 2026, section 1446 tax withheld by another partnership, and certain section 1445 and section 1446(f)(1) tax withheld from the partnership.
The instructions say not to figure any required installment until after the end of the month before its due date. In Part IV, lines 39 to 43 of one column are done before line 38 of the next.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Do Not File." The instructions say to keep the form for your records and not to send it to the IRS Tax Forms and Publications office.
The instructions say a payment can be submitted with Form 8813 and a check or money order, or through EFTPS. With EFTPS, Forms 8804 and 8805 are still filed.
Installments are due by the 15th day of the 4th, 6th, 9th, and 12th months of the partnership's tax year, or the next regular business day if a date falls on a weekend or legal holiday.
A partnership that does not pay installments when due may owe an underpayment penalty, figured on Schedule A (Form 8804). The instructions say an immediate catch-up payment should be made to reduce it.
Options 1 and 2 in Part III are used only if the partnership filed Form 8842 on or before the due date of the first required installment. The instructions say that election is irrevocable for the tax year.
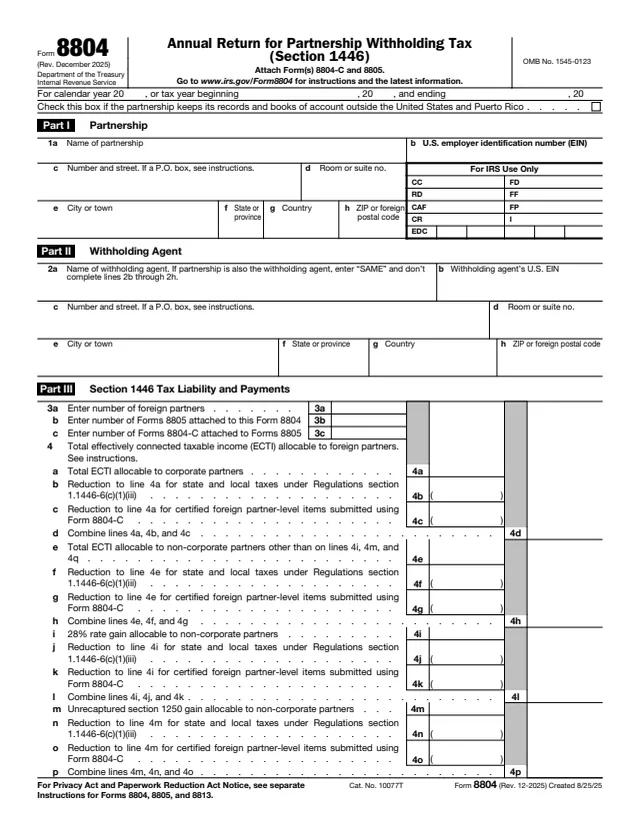
8804
81 fields, 2 pages
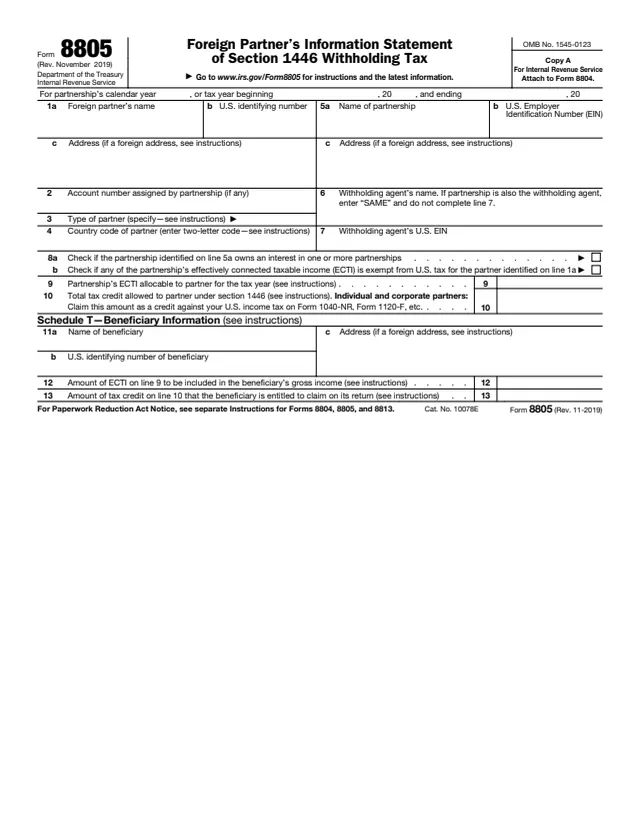
8805
100 fields, 4 pages
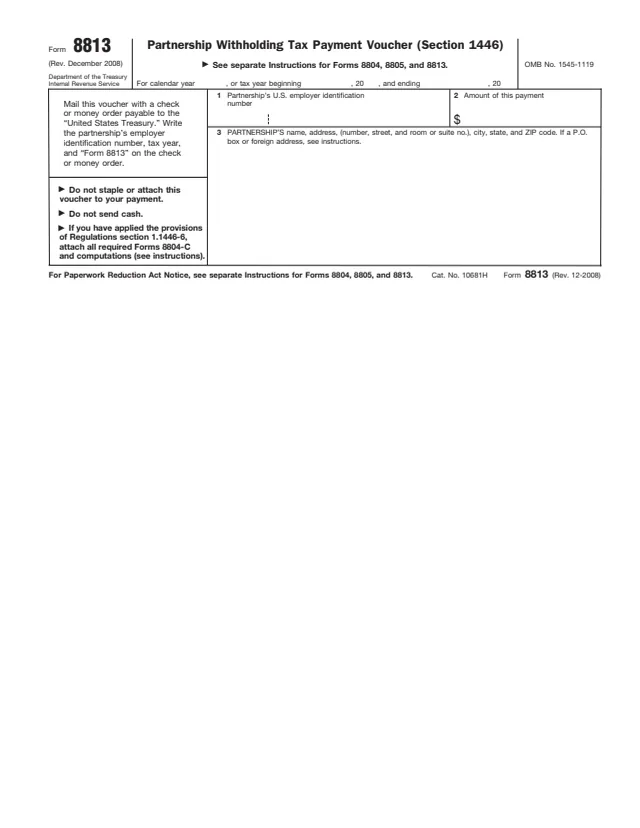
8813
9 fields, 1 page
8804-C
46 fields, 3 pages
8804
405 fields, 5 pages
8842
20 fields, 2 pages
The worksheet belongs to the partnership. It is not sent to the IRS or to the partners.
No tool matches that search.
No. The form is a worksheet for the partnership's records and says "Do Not File."
The instructions say partnerships generally make installment payments if the aggregate tax on the ECTI allocable to all foreign partners will be $500 or more.
By the 15th day of the 4th, 6th, 9th, and 12th months of the partnership's tax year, the instructions say, moved to the next regular business day after a weekend or legal holiday.
Lines 2 to 6 multiply by 21%, 37%, 28%, 25% and 20% for corporate partners, non-corporate partners, 28% rate gain, unrecaptured section 1250 gain and adjusted net capital gain.
The instructions say "Your use of this form is optional. It is provided to aid the partnership in determining its tax liability."
This page hosts the 2026 Form 8804-W, for calendar year 2026 or a tax year beginning in 2026.