Header
Name and identifying number of the person filing Form 8865, name of partnership, EIN or reference ID number, name of U.S. transferor, the two successor boxes and the filing year boxes.
8865 Sch. H
Acceleration Events and Exceptions Reporting Relating to Gain Deferral Method Under Section 721(c)
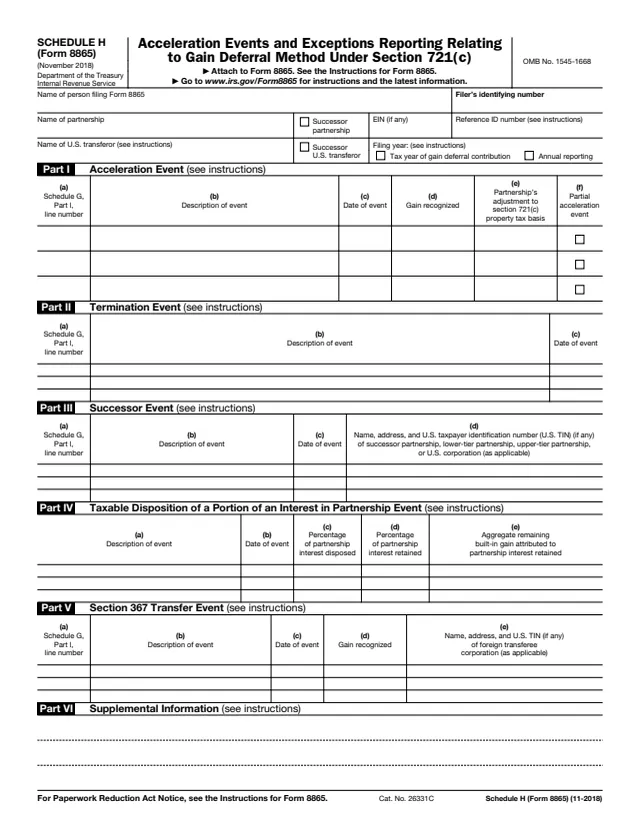
Schedule H (Form 8865), Acceleration Events and Exceptions Reporting Relating to Gain Deferral Method Under Section 721(c), is attached to Form 8865. The Instructions for Form 8865 say that if the gain deferral method is being applied to reportable section 721(c) property, Schedule H is completed and filed to report certain events related to that property, with a separate Schedule H for each partnership.
It works together with Schedule G (Form 8865). The instructions say to complete the Parts of Schedule H that correspond to the boxes checked in Schedule G, Part I, column 7, and the related lines in Schedule G, Part V, answered "Yes." Its six parts cover acceleration events, termination events, successor events, taxable dispositions of a portion of a partnership interest, section 367 transfers and supplemental information.
This is the November 2018 version, OMB No. 1545-1668. You can fill out the PDF free in your browser on this page and download it without an account.
Name and identifying number of the person filing Form 8865, name of partnership, EIN or reference ID number, name of U.S. transferor, the two successor boxes and the filing year boxes.
Schedule G line number, description and date of event, gain recognized, the partnership's adjustment to section 721(c) property tax basis and a partial acceleration event box.
Schedule G line number, description and date of each event. Part III adds the name, address and U.S. TIN, if any, of the successor, lower-tier or upper-tier partnership, or U.S. corporation.
Description and date of the event, percentage of partnership interest disposed and retained, and aggregate remaining built-in gain attributed to the interest retained.
Schedule G line number, description and date of event, gain recognized, and the name, address and U.S. TIN, if any, of the foreign transferee corporation.
Space for added rows from Parts I to V and any other information required by Regulations section 1.721(c)-6 not reported elsewhere.
Enter the filer, partnership and U.S. transferor details and check the boxes that apply. Under Schedule G, the instructions explain the filing year boxes: tax year of gain deferral contribution, annual reporting, or both.
Complete each Part tied to a box checked in Schedule G, Part I, column 7. In column (a) of Parts I, II, III and V, enter the property's line number from Schedule G, Part I, or from its attached statement.
Describe the acceleration event, with the citation for a partial or deemed event. Enter the gain recognized in column (d), the partnership's basis increase in column (e), and check column (f) for a partial acceleration event.
Describe each termination or successor event with the citation to Regulations section 1.721(c)-5(b) or 1.721(c)-5(c). In Part III, column (d), enter the successor's name, address and U.S. TIN, if any.
Part IV takes the percentages disposed and retained and the aggregate remaining built-in gain, with a detailed supporting schedule attached. Part V takes the gain recognized and the foreign transferee corporation's details.
Indicate the Part, column, row and line for each item. If more rows are needed, attach them in the same format as the Part at issue.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says "Attach to Form 8865." It is not filed on its own.
The instructions say Form 8865 is attached to the income tax return (or partnership or exempt organization return) and filed by its due date, including extensions. Without such a return, Form 8865 is filed separately at the time and place one would be filed.
The instructions say to complete a separate Schedule H for each partnership.
The instructions say a transfer of property to a foreign corporation is subject to other reporting under sections 367, 351, 368 and 6038B, for example Form 926, in addition to Schedule H.
The instructions say a failure to comply with the gain deferral method's reporting requirements may result in an acceleration event under Regulations section 1.721(c)-4(b)(2) and a penalty under section 6038B.
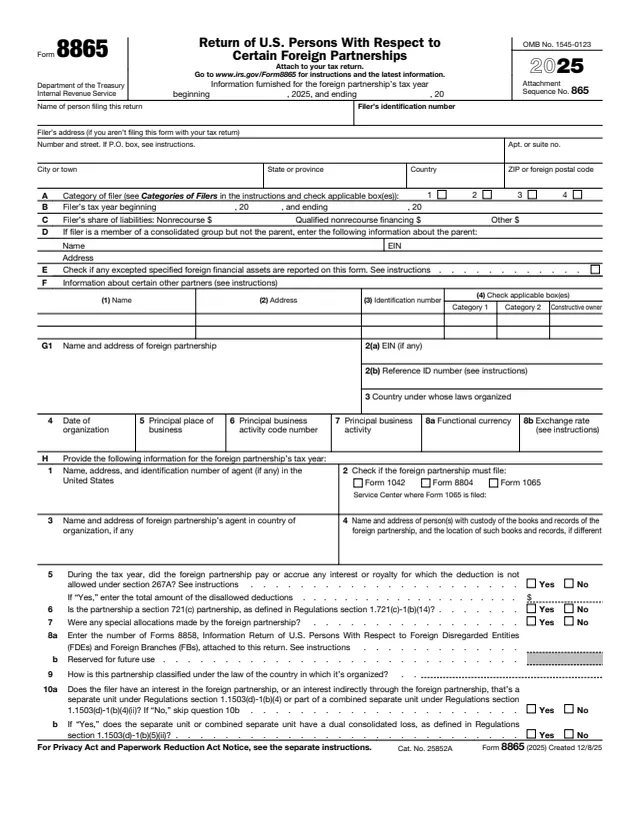
8865
461 fields, 6 pages
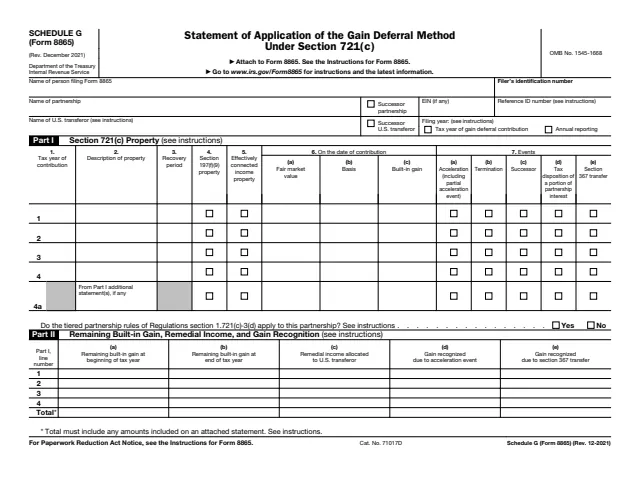
8865 Sch. G
203 fields, 2 pages
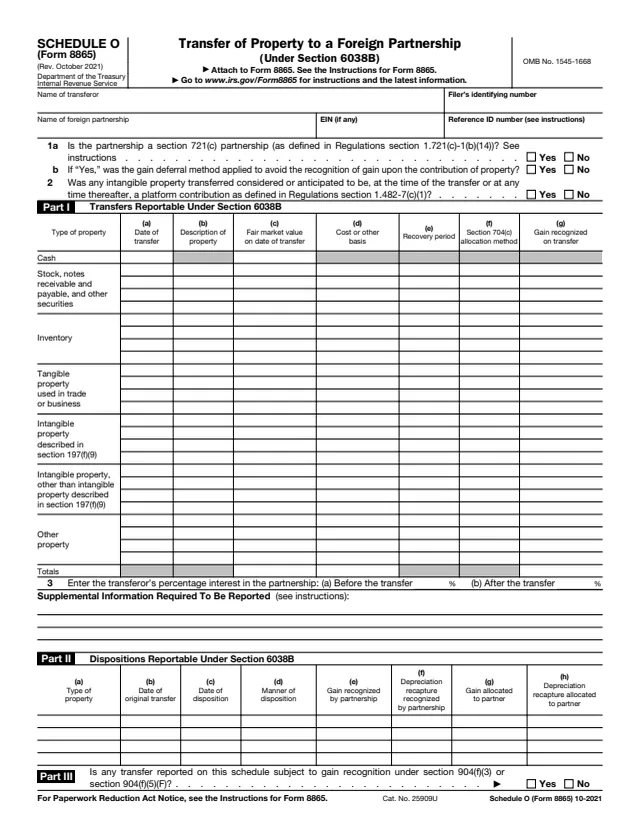
8865 Sch. O
233 fields, 1 page
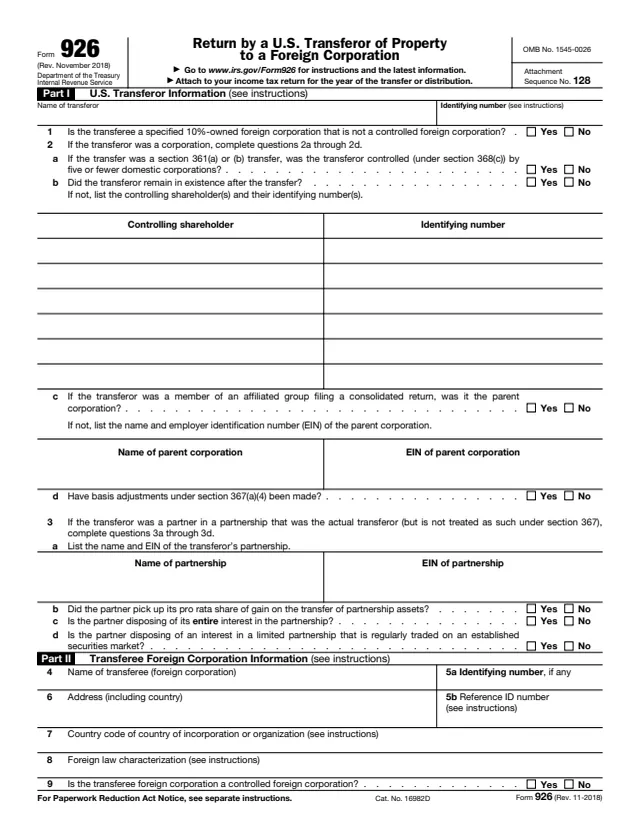
926
212 fields, 3 pages
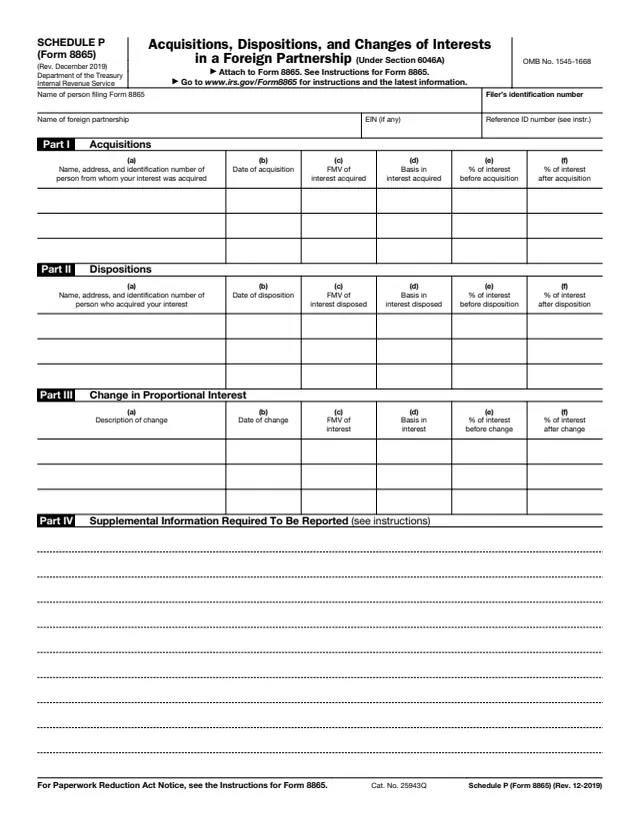
8865 Sch. P
69 fields, 1 page
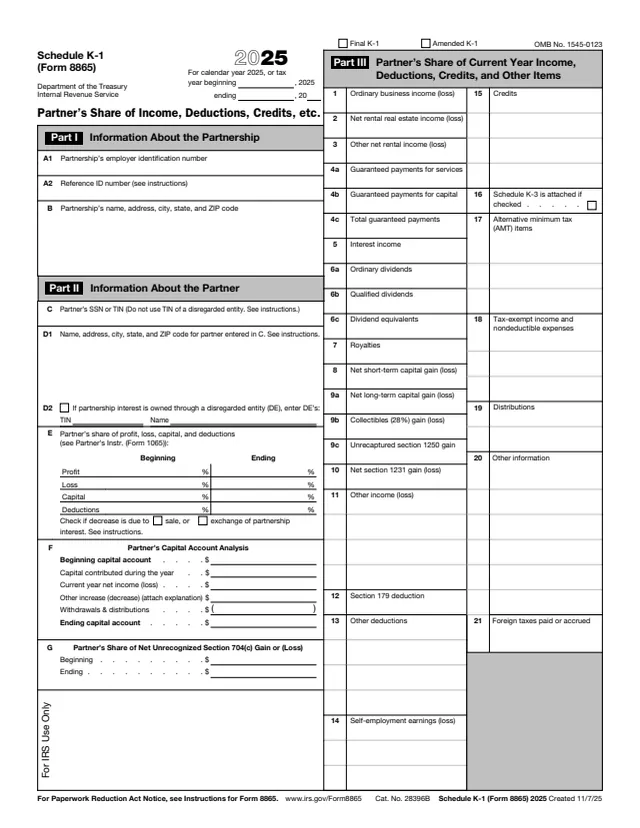
8865
108 fields, 1 page
The instructions tie Schedule H to U.S. transferors that apply the gain deferral method to section 721(c) property. They define a U.S. transferor as a U.S. person other than a domestic partnership.
No tool matches that search.
The instructions say that if the answer is "Yes" to any of the questions on lines 1 through 6b of Schedule G, Part V, Schedule H is also completed and attached.
The instructions say to complete a separate Schedule H for each partnership.
The instructions describe it as any event that would reduce the remaining built-in gain the U.S. transferor would have recognized under the gain deferral method, or could defer recognition of that gain. It applies property by property.
The instructions say a U.S. transferor may treat an acceleration event as having occurred by recognizing the remaining built-in gain in the property and meeting the reporting requirements of the acceleration event.
The instructions say to attach a statement in the same format as the Part and to note it in Part VI, Supplemental Information.
This is the November 2018 version, OMB No. 1545-1668. Its footer reads Schedule H (Form 8865) (11-2018).