Header
Name(s) shown on the return and the taxpayer identification number.
8995-A
Specified Service Trades or Businesses
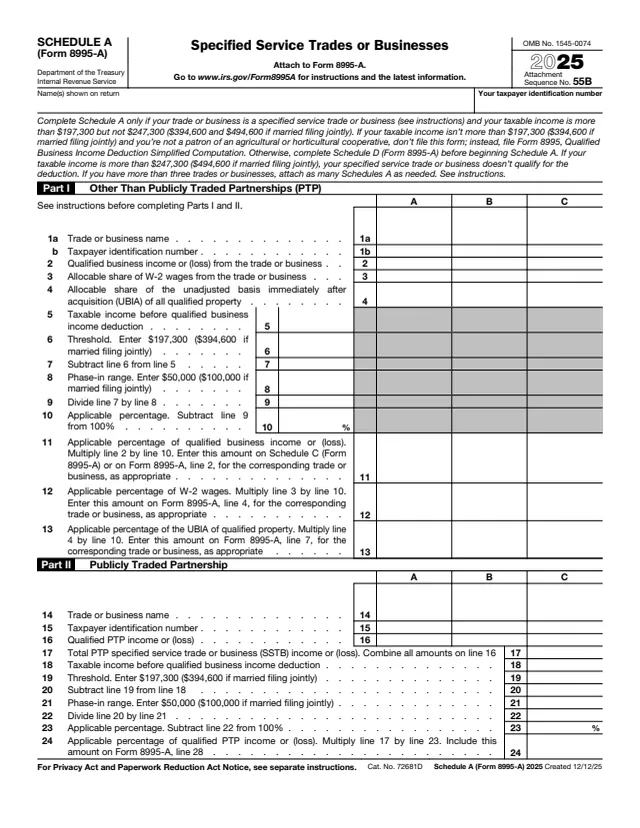
Schedule A (Form 8995-A), Specified Service Trades or Businesses, is the 2025 schedule attached to Form 8995-A for the qualified business income deduction. It is filled out by a taxpayer who has a specified service trade or business (SSTB) and whose taxable income falls inside the range printed at the top of the schedule.
The form says to complete Schedule A only if the trade or business is a specified service trade or business and taxable income is more than $197,300 but not $247,300 ($394,600 and $494,600 if married filing jointly). Below that range, and for a taxpayer who is not a patron of an agricultural or horticultural cooperative, the form points to Form 8995 instead. Above it, the form says the SSTB doesn't qualify for the deduction.
Part I works out an applicable percentage of each SSTB's qualified business income, W-2 wages and UBIA of qualified property. Part II does the same for publicly traded partnership income. The PDF can be filled out free in the browser on this page and downloaded without an account.
Name(s) shown on the return and the taxpayer identification number.
For up to three trades or businesses in columns A, B and C: name, TIN, qualified business income or loss, allocable share of W-2 wages and allocable share of UBIA of qualified property.
Taxable income before the deduction, the $197,300 threshold ($394,600 if married filing jointly), the $50,000 phase-in range ($100,000 if married filing jointly) and the applicable percentage.
The applicable percentage of qualified business income, W-2 wages and UBIA of qualified property, each carried to Schedule C (Form 8995-A) or Form 8995-A.
Publicly traded partnership name, TIN and qualified PTP income or loss, combined on line 17 as total PTP SSTB income or loss.
The same threshold and phase-in figures for PTP income, ending with the applicable percentage of qualified PTP income or loss on line 24.
Compare taxable income with the amounts printed at the top of the form. The form says when to file Form 8995 instead and when the SSTB doesn't qualify for the deduction.
Enter each SSTB's name, TIN, qualified business income or loss, W-2 wages and UBIA in its own column. The form says to attach as many Schedules A as needed for more than three trades or businesses.
Enter taxable income before the qualified business income deduction, subtract the threshold on line 6, divide by the phase-in range on line 8 and subtract the result from 100% on line 10.
Multiply lines 2, 3 and 4 by line 10. The form says to enter line 11 on Schedule C (Form 8995-A) or Form 8995-A, line 2, line 12 on Form 8995-A, line 4, and line 13 on Form 8995-A, line 7.
For publicly traded partnerships, enter each name, TIN and qualified PTP income or loss, then combine all line 16 amounts on line 17.
Repeat the threshold and phase-in figures, multiply line 17 by line 23, and include the line 24 amount on Form 8995-A, line 28.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says Attach to Form 8995-A. It carries attachment sequence number 55B and is not filed on its own.
The form says to attach as many Schedules A as needed when there are more than three trades or businesses.
This is the 2025 schedule. The threshold and phase-in amounts on lines 6, 8, 19 and 21 are the ones printed on the 2025 form.
The form says to go to www.irs.gov/Form8995A for instructions and the latest information, including the definition of a specified service trade or business.
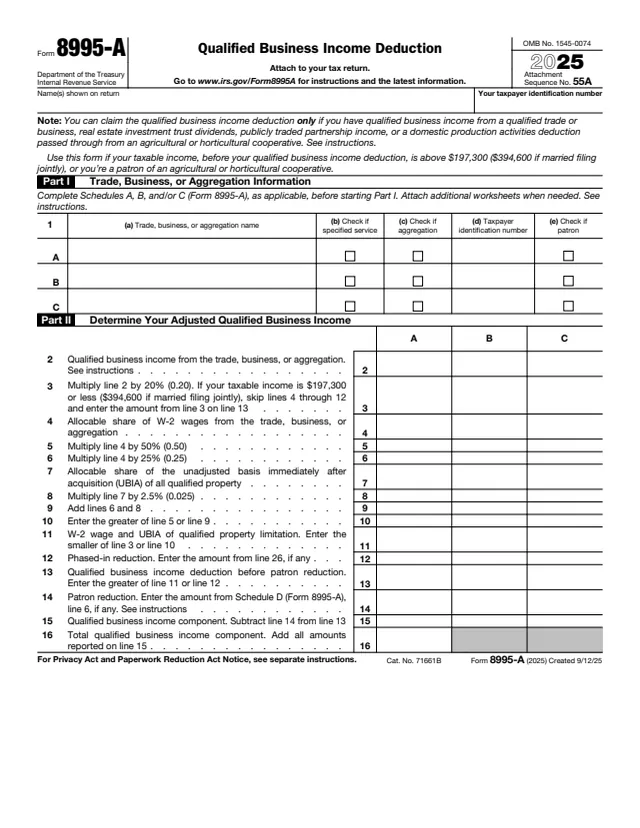
8995-A
111 fields, 2 pages
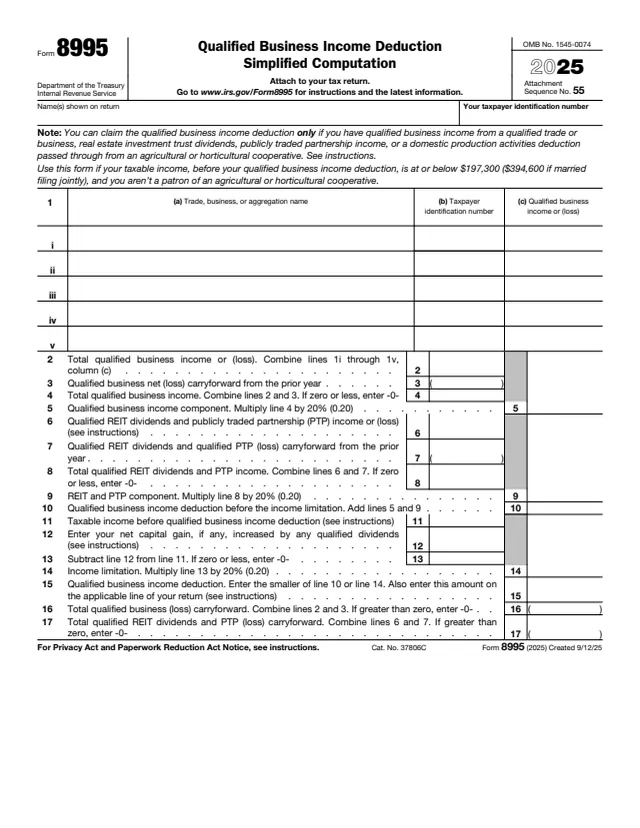
8995
33 fields, 1 page
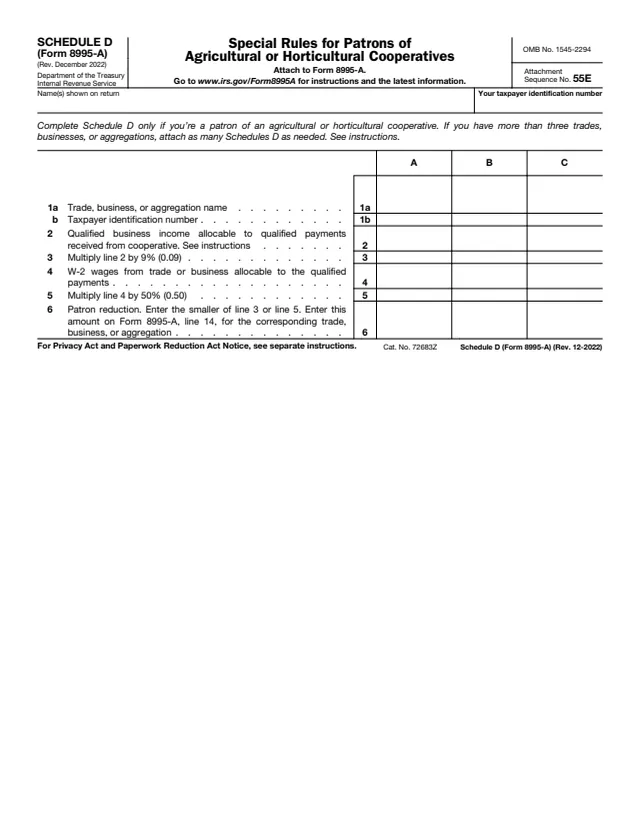
8995-A Sch. D
23 fields, 1 page
8995-A Sch. C
19 fields, 1 page
8995-A Sch. B
27 fields, 1 page
The schedule goes with Form 8995-A on the taxpayer's return. The form's own text sets out when it applies.
No tool matches that search.
The form says to complete it only if the trade or business is a specified service trade or business and taxable income is more than $197,300 but not $247,300 ($394,600 and $494,600 if married filing jointly).
If taxable income isn't more than $197,300 ($394,600 if married filing jointly) and the taxpayer isn't a patron of an agricultural or horticultural cooperative, the form says not to file it and to file Form 8995 instead.
The form says that if taxable income is more than $247,300 ($494,600 if married filing jointly), the specified service trade or business doesn't qualify for the deduction.
Taxable income minus the threshold is divided by the phase-in range of $50,000 ($100,000 if married filing jointly), and the result is subtracted from 100%. Part I does this on lines 5 to 10 and Part II on lines 18 to 23.
Line 11 goes to Schedule C (Form 8995-A) or Form 8995-A, line 2. Line 12 goes to Form 8995-A, line 4, line 13 to Form 8995-A, line 7, and line 24 is included on Form 8995-A, line 28.
No. The form says to attach it to Form 8995-A, and to complete Schedule D (Form 8995-A) before beginning Schedule A.