1041

Alternative Minimum Tax—Estates and Trusts

Agency
IRS
Revision
2025
Fillable fields
85
Pages
3
Official source
IRS form page
Checked
October 21, 2026
Fill 1041 online
Page 1 of form 1041

2025 Schedule I (Form 1041): Alternative Minimum Tax, Estates and Trusts

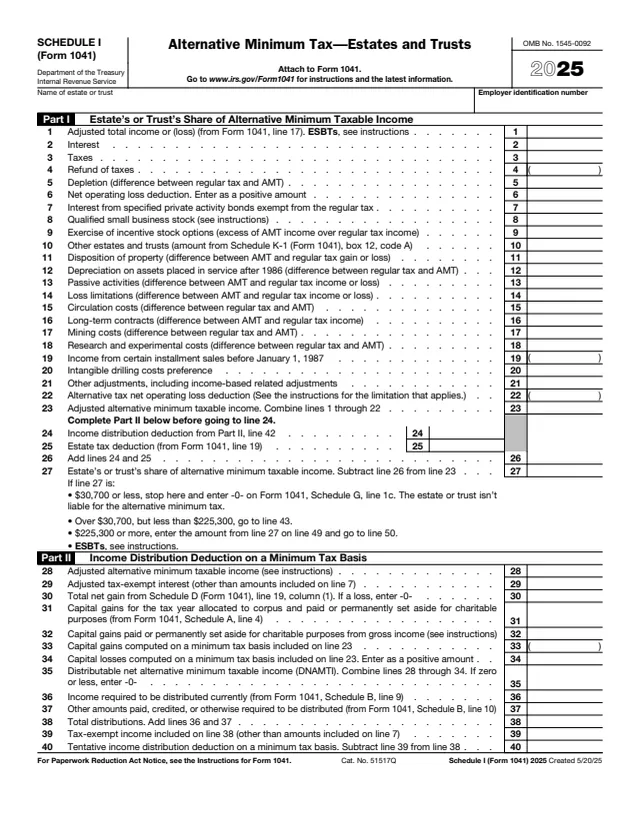
Schedule I (Form 1041) is the IRS schedule for the alternative minimum tax of estates and trusts. The instructions say to use it to figure the estate's or trust's alternative minimum taxable income, the income distribution deduction on a minimum tax basis, and the estate's or trust's alternative minimum tax (AMT). The form says to attach it to Form 1041.

The fiduciary of the estate or trust completes it. It has four parts: the estate's or trust's share of alternative minimum taxable income, the income distribution deduction on a minimum tax basis, the AMT computation, and a line 50 computation using maximum capital gains rates. For 2025 the form prints an exemption amount of $30,700 and a phase-out amount of $102,500. The AMT on line 54 is entered on Form 1041, Schedule G, line 1c.

You can fill out Schedule I (Form 1041) free in your browser on this page and download it without an account.

What's on Schedule I (Form 1041)

Part I: Share of alternative minimum taxable income

Lines 1 to 27 start with adjusted total income from Form 1041, line 17, add adjustments and preference items such as interest, taxes, depletion and incentive stock options, then subtract the income distribution and estate tax deductions.

Line 27 thresholds

If line 27 is $30,700 or less, enter -0- on Form 1041, Schedule G, line 1c. Over $30,700 but less than $225,300, go to line 43. At $225,300 or more, enter it on line 49 and go to line 50.

Part II: Income distribution deduction

Lines 28 to 42 figure distributable net alternative minimum taxable income (DNAMTI), total distributions and the deduction on a minimum tax basis that goes back to line 24.

Part III: Alternative Minimum Tax

Lines 43 to 54 apply the $30,700 exemption and the $102,500 phase-out, the 26% and 28% rates, the AMT foreign tax credit and the regular tax to reach the AMT.

Part IV: Maximum capital gains rates

Lines 55 to 83 refigure line 50 when the estate or trust has qualified dividends or a gain on lines 18a and 19 of column (2) of Schedule D (Form 1041), using 0%, 15%, 20% and 25% rates.

How to fill out Schedule I (Form 1041)

  1. 1

    Line 1

    Enter adjusted total income or loss from Form 1041, line 17. The instructions say the section 199A deduction isn't included here and is entered on line 21 as a negative amount.

  2. 2

    Lines 2 to 22

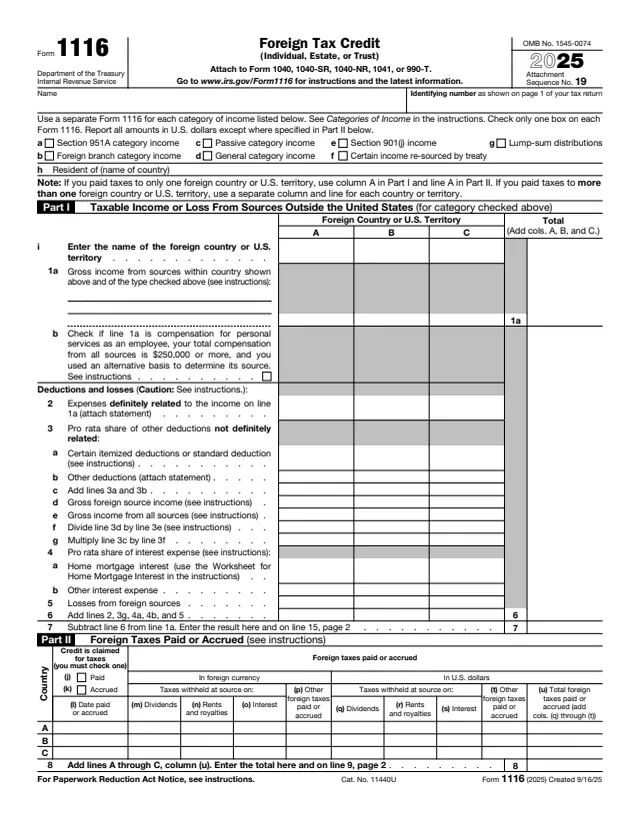
    Enter each AMT adjustment and preference item. The instructions say forms completed for the regular tax may need to be completed again for AMT, but only an AMT Form 1116 is filed with Form 1041.

  3. 3

    Part II before line 24

    The form says to complete Part II before going to line 24. Enter the smaller of line 40 or line 41 on line 42, then carry it to line 24.

  4. 4

    Line 27

    Subtract line 26 from line 23, then follow the thresholds printed under line 27 to see where to go next.

  5. 5

    Lines 43 to 54

    Apply the exemption and phase-out, figure the tentative minimum tax, subtract the tax from Form 1041, Schedule G, line 1a, and enter the AMT on line 54 and on Schedule G, line 1c.

  6. 6

    Line 50 or Part IV

    Without qualified dividends or capital gains, line 50 is 26% of line 49 if it is $239,100 or less, or 28% minus $4,782 if it is more. Otherwise use Part IV.

Why fill Form 1041 on indox

You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.

  • Fill the form right in your browser, no software to install
  • Free to fill and free to download, with no account
  • The official blank straight from the IRS, not a copy someone retyped
  • Works on a phone, tablet or computer

How it is filed and what to keep

Attach to Form 1041

The form says to attach it to Form 1041. It is filed with that return, not on its own.

ESBTs

Use a separate Schedule I for the S portion, add the notation "ESBT" at the top, and attach it to the tax computation attachment for Form 1041.

AMT worksheets stay with your records

The instructions say to keep the AMT Form 8949, AMT Schedule D (Form 1041) and applicable AMT worksheet for your records, and not attach them to Form 1041.

Carryforward records

Carryback and carryforward amounts can differ for the regular tax and the AMT. The instructions say to keep records of both, because the AMT carryforward will be important for the 2026 Schedule I.

Beneficiary items

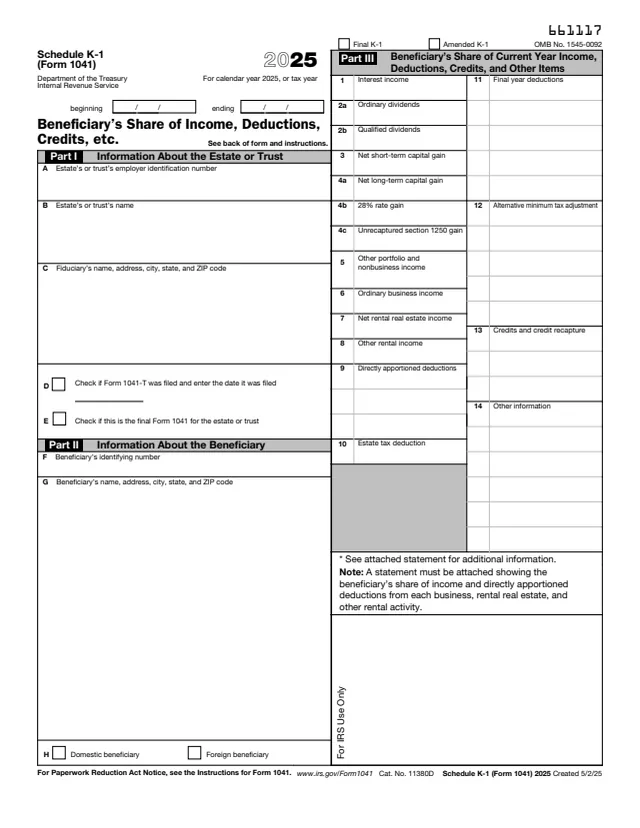
Adjustments for accelerated depreciation, depletion and amortization allocated to beneficiaries are reported in box 12 of Schedule K-1 (Form 1041), with codes G, H and I.

Who completes Schedule I (Form 1041)?

  • Estates and trusts that complete Schedule B

    The instructions say to complete Parts I and II if the estate or trust is required to complete Form 1041, Schedule B, Income Distribution Deduction.

  • AMT income over $30,700

    The instructions say to complete Schedule I if the estate's or trust's share of alternative minimum taxable income on Part I, line 27, exceeds $30,700.

  • General business credit claimants

    Schedule I is also completed if the estate or trust claims any general business credit and line 6 of Part I or line 3 of Part III of Form 3800 is more than zero.

  • Electing small business trusts

    An ESBT figures the AMT for the S and non-S portions on separate Schedules I, with "ESBT" at the top of the one for the S portion. ESBTs do not complete Part II.

  • Estates and trusts that paid AMT before

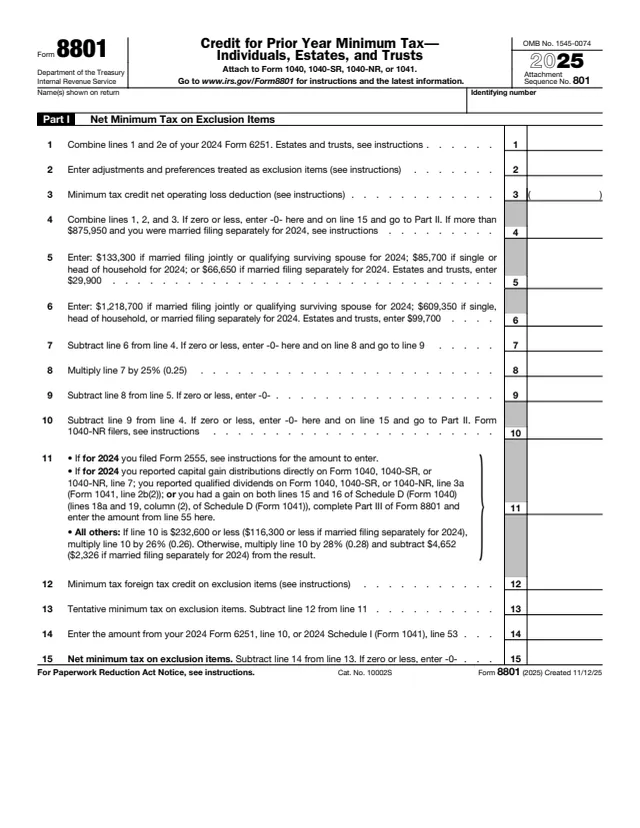
    The instructions point estates and trusts that paid AMT in 2024, or had a minimum tax credit carryforward from the 2024 Form 8801, to Form 8801 for a credit in 2025.

The fiduciary of the estate or trust completes it and attaches it to Form 1041. The instructions list the cases that call for it.

Official sources and the blank

Do it all with indox

View all 123 tools

Questions about Form 1041

When is Schedule I (Form 1041) completed?

The instructions list three cases: the estate or trust is required to complete Form 1041, Schedule B (Parts I and II), line 27 exceeds $30,700, or it claims a general business credit with an amount on Form 3800, Part I, line 6 or Part III, line 3.

What is the 2025 exemption amount?

The form prints $30,700. The instructions say it begins to phase out at amounts over $102,500 and is completely phased out at $225,300.

Where does the AMT go on Form 1041?

The form says to enter line 54 on Form 1041, Schedule G, line 1c.

Do ESBTs use Schedule I?

Yes. An ESBT figures the AMT for its S and non-S portions on separate Schedules I, and does not complete Part II.

What are the AMT rates on line 50?

26% of line 49 if it is $239,100 or less, or 28% minus $4,782 if more. Part IV is used instead when the estate or trust has qualified dividends or capital gains.

Is there a credit for AMT paid in 2024?

The instructions point estates and trusts that paid AMT in 2024, or had a credit carryforward from the 2024 Form 8801, to Form 8801.