Header
Name, EIN, address, tax year ending, the name and address on the original return, the service center where it was filed (or "e-filed") and the number of Forms 8986, amended Schedules K-1 or Schedules Q filed.
1065-X
Amended Return or Administrative Adjustment Request (AAR)
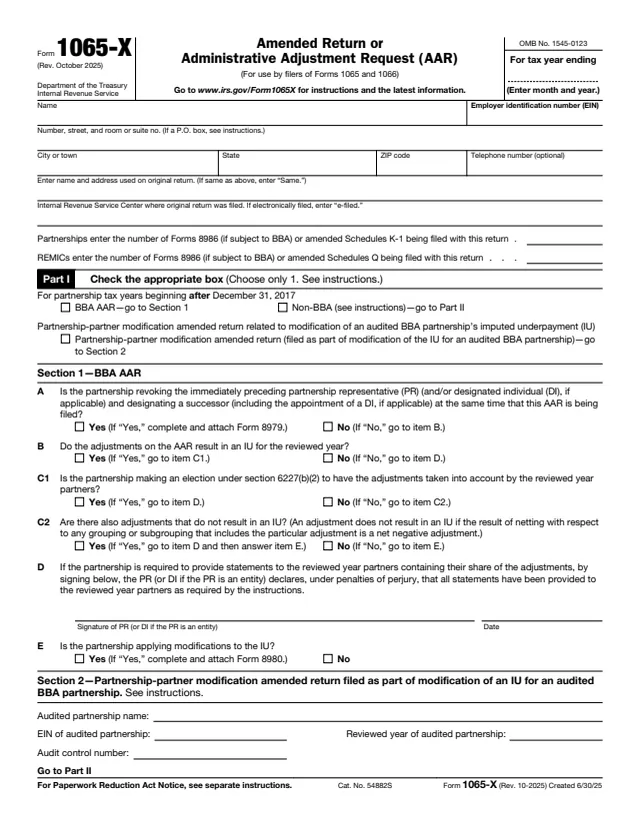
Form 1065-X, Amended Return or Administrative Adjustment Request (AAR), is for use by filers of Forms 1065 and 1066. The IRS About page says it is used, when not filing electronically, to correct items on a previously filed Form 1065, Form 1065-B, or Form 1066, or to make an AAR for one of those returns. The instructions add a third use: a partnership-partner modification amended return related to modification of an audited BBA partnership's imputed underpayment (IU).
Partnerships and real estate mortgage investment conduits (REMICs) file it, not individual partners. The instructions say a BBA partnership's AAR is filed by its partnership representative (PR), or by the designated individual (DI) if the PR is an entity. Form 1065-X can't be used to file a notice of inconsistent treatment under section 6222; that is Form 8082.
The instructions say to use the October 2025 revision for tax years beginning after 2024. You can fill out Form 1065-X free in your browser on this page and download it without an account.
Name, EIN, address, tax year ending, the name and address on the original return, the service center where it was filed (or "e-filed") and the number of Forms 8986, amended Schedules K-1 or Schedules Q filed.
One box: BBA AAR, non-BBA, or partnership-partner modification. Section 1 items A to E cover a successor PR, the IU, the section 6227(b)(2) election, the PR's statement signature and IU modifications.
The audited partnership's name, EIN, reviewed year and audit control number, for a partnership-partner modification amended return.
Schedule K items on lines 1 to 21, from ordinary business income to foreign taxes, each with columns for the amount as originally reported, the net change and the correct amount.
Rows for each item being amended or adjusted, then lines 6 to 16 for REMIC taxes, payments with Form 7004 and the original return, and tax due or overpayment.
Part IV lines 1 to 4 show the IU, total amount due, total payment and balance due. Then the signature area and Part V for explaining each change.
Enter the entity's legal name, EIN and address, the tax year ending, the name and address used on the original return (or "Same"), and the service center where it was filed or "e-filed."
Check only one box. BBA AAR goes to Section 1, non-BBA goes to Part II, and a partnership-partner modification amended return goes to Section 2.
Answer items A to E. A Yes on item A means attaching Form 8979, and a Yes on item E means attaching Form 8980. The PR signs item D when statements go to reviewed year partners.
Column (a) is the amount as originally filed or previously adjusted, column (b) the net change with decreases in parentheses, and column (c) the sum of (a) and (b). REMICs use Part III.
The instructions say a BBA AAR always includes an IU computation. Line 1 shows zero when the adjustments don't result in an IU or the section 6227(b)(2) election is made.
Enter the Part II or III line number before each change with the reason, the Schedule K-1 box and code for partnerships, and the computations. Then sign and date.
The instructions say that if an item in Part I or Part II can't be completed, enter "See Part V" and give the information there.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 1065-X is filed with the service center where the original return was filed.
The instructions say an amended return or AAR is generally filed within 3 years after the later of the dates they list. A BBA partnership files before a notice of an administrative proceeding for the tax year is mailed under section 6231.
Non-BBA partnerships file amended Schedules K-1 with Form 1065-X and furnish copies to partners. A BBA partnership filing an AAR uses Forms 8985 and 8986 instead of Schedules K-1.
Attach any schedule, statement or form the corrected amount needs, with the entity's name and EIN. The instructions say copies of previously filed forms are marked at the top as copy only, not to be processed.
The instructions say a BBA partnership whose AAR results in an IU, and that doesn't elect the alternative to payment, pays the IU when it files. Electronic payments use the description "BBA AAR Imputed Underpayment."
The instructions note that a change to a federal return may affect the state return, and point to the state tax agency where it was filed.

1065
440 fields, 6 pages
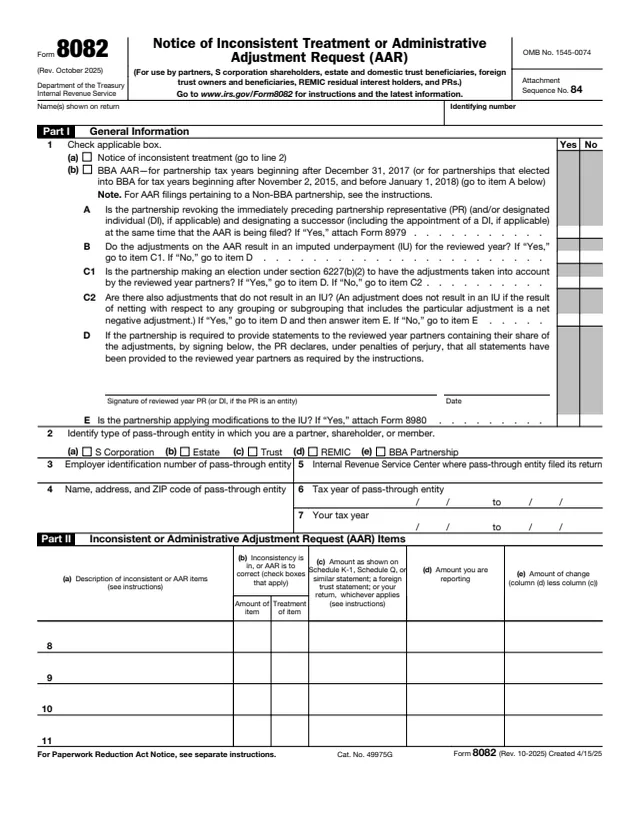
8082
59 fields, 2 pages
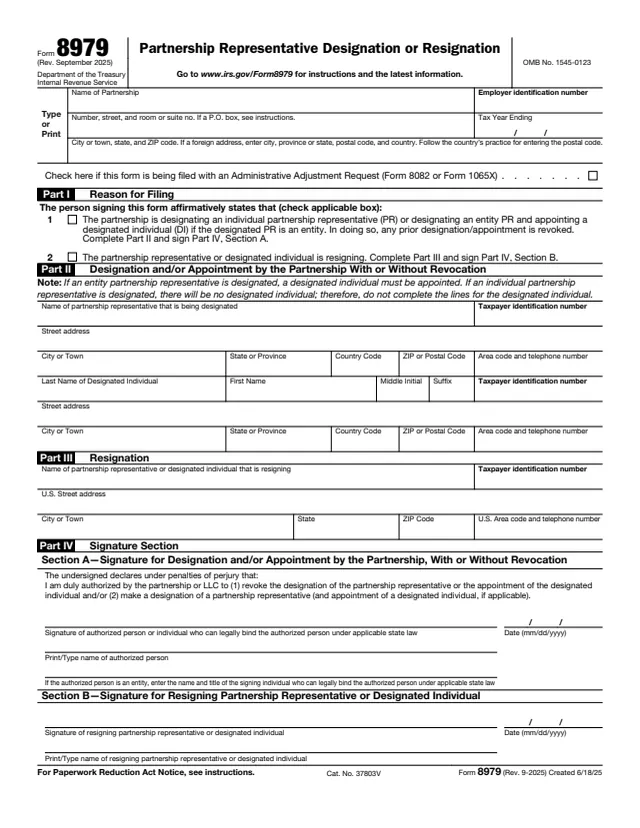
8979
45 fields, 1 page

1065
111 fields, 1 page
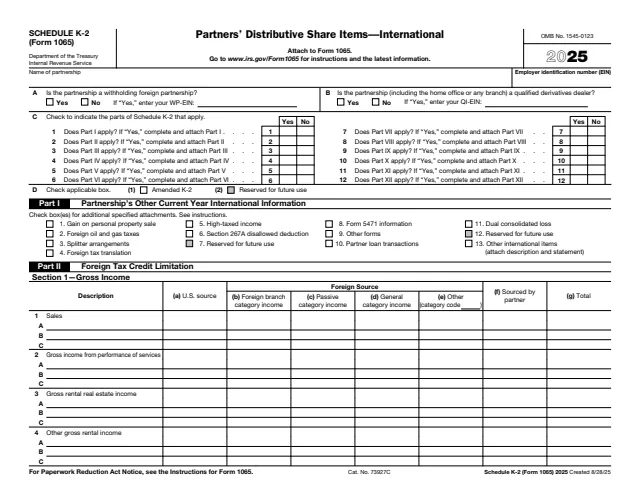
1065
2,799 fields, 19 pages

7004
26 fields, 1 page
The form is filed by the partnership or REMIC itself, and signed by a partner, LLC member, PR or DI depending on the kind of filing.
No tool matches that search.
The About page says it is used when not filing electronically. The instructions say a non-BBA partnership amending electronically uses Form 1065, and a BBA AAR filed electronically uses Form 8082 with Form 1065.
An administrative adjustment request. The instructions say the PR, or the DI if the PR is an entity, files it to correct a previously filed partnership return on behalf of the BBA partnership.
Any partner or LLC member for a non-BBA partnership, the PR (or DI) for a BBA AAR, and a fiduciary when a receiver, trustee or assignee makes the return.
No. The instructions say it furnishes Forms 8986 to reviewed year partners and files them with Form 8985, not Schedules K-1.
No. The instructions say an election out can only be made on a timely filed original return.
No. The instructions say a BBA partnership may not file an AAR solely to change the PR. A successor PR named with an AAR is reported on Form 8979.
The instructions say the October 2025 revision is for tax years beginning after 2024, and name earlier revisions for earlier tax years.