Header
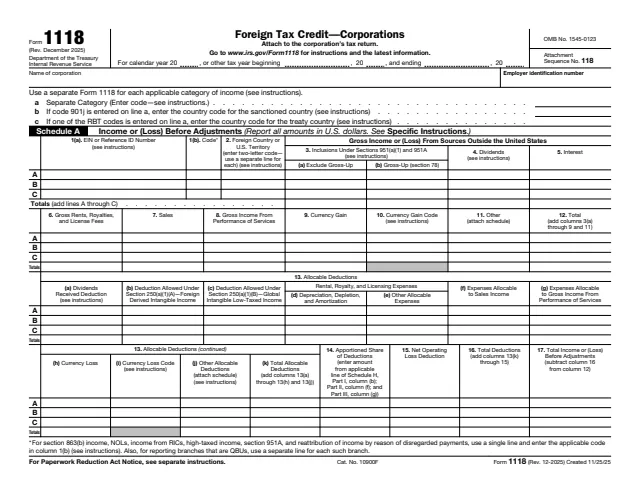
The tax year, the name of the corporation and its employer identification number. The schedule says "Attach to Form 1118."
1118 Sch. J
Adjustments to Separate Limitation Income (Loss) Categories for Determining Numerators of Limitation Fractions, Year-End Recharacterization Balances, and Overall Foreign and Domestic Loss Account Balances
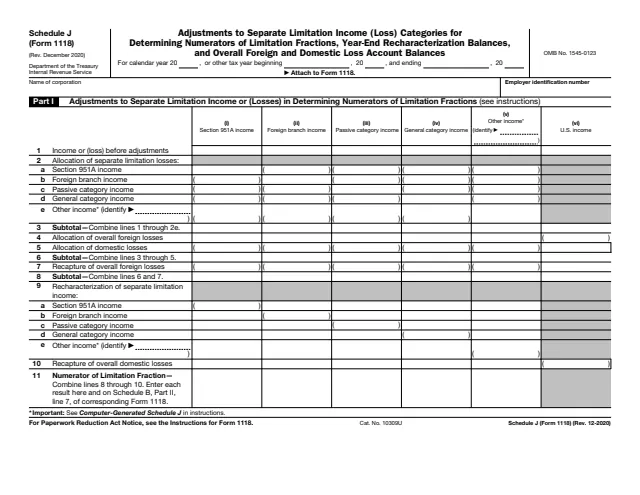
Schedule J (Form 1118) has a long title: Adjustments to Separate Limitation Income (Loss) Categories for Determining Numerators of Limitation Fractions, Year-End Recharacterization Balances, and Overall Foreign and Domestic Loss Account Balances. The IRS About page says corporations claiming foreign tax credit use this schedule to compute adjustments to separate limitation income (losses) and year-end account balances.
The schedule is attached to Form 1118, the corporate foreign tax credit form. Its columns cover section 951A income, foreign branch income, passive category income, general category income, other income and U.S. income. Part I figures the numerator of the limitation fraction for each category, Part II shows year-end recharacterization balances, and Parts III and IV track the overall foreign loss and overall domestic loss accounts. The instructions say to complete Schedule J only once, including adjustments for each applicable separate category.
This page has the December 2020 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
The tax year, the name of the corporation and its employer identification number. The schedule says "Attach to Form 1118."
Income or loss before adjustments, the allocation of separate limitation losses, overall foreign losses and domestic losses, and recapture of overall foreign losses, with subtotals.
Recharacterization of separate limitation income, recapture of overall domestic losses, and line 11, the numerator of the limitation fraction for each category.
Year-end balances of future separate limitation income that must be recharacterized under section 904(f)(5)(C), in a grid of categories.
Overall foreign loss account balances under section 904(f)(1): beginning balance, current year additions, reductions, recapture from Part I, line 7, and ending balance.
Overall domestic loss account balances under section 904(g)(1): beginning balance, additions, reductions, recapture from Part I, line 10, and ending balance.
For columns (i) to (v), enter the income or loss from column 18 of the matching Schedule A for each category. In column (vi), enter Schedule B, Part II, line 8c, minus the total of the other columns.
Allocate each separate limitation loss pro rata to categories with positive income using the formulas in the instructions. Enter the allocated totals in the bold-outlined boxes as positive numbers. Each line should total zero across.
Enter overall foreign losses, U.S. source losses allocated to categories, and recapture of prior overall foreign losses. The instructions say recapture is the smaller of the maximum potential recapture or 50% of Part I, line 6, columns (i) to (v).
Recharacterize current income in a category from which a loss was allocated in a prior year, and recapture overall domestic losses. The instructions say the amounts across each line should equal zero.
Combine lines 8 through 10 and enter each result on line 11 and on Schedule B, Part II, line 7, of the corresponding Form 1118.
Enter last year's ending balances on line 1 of Parts III and IV, show additions, reductions and recapture, and enter the year-end balances. Part II shows the amounts still to be recharacterized.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says "Attach to Form 1118." The line 11 amounts go on Schedule B, Part II, line 7, of the corresponding Form 1118.
The instructions say to complete Schedule J only once and include adjustments for each applicable separate category.
The instructions say a computer-generated Schedule J can be filed if it conforms to the IRS version, with each added other income column labeled "901(j)" and the sanctioned country, or "RBT" and the treaty country and category.
The instructions point to Regulations section 1.904(g)-3 for the ordering of Part I adjustments, and to Regulations sections 1.904(f)-1 and 1.904(g)-1 for account additions and reductions.
A corporation completes it and attaches it to its Form 1118. It is not a form for individuals.
No tool matches that search.
The About page says corporations claiming foreign tax credit use it to compute adjustments to separate limitation income (losses) and year-end account balances.
The instructions say to complete Schedule J only once, including adjustments for each applicable separate category.
The instructions say current income in a category from which a loss was allocated in a prior year is recharacterized as income of the categories that received the loss (section 904(f)(5)). They add that this does not recharacterize any tax.
The instructions say the corporation can make an annual, revocable election to recapture a greater portion by attaching a statement to Form 1118 giving the percentages and dollar amounts.
The instructions say section 904(g)(5) allows an election to recapture up to 100% of any pre-2018 unused overall domestic loss, for tax years beginning after December 31, 2017, and before January 1, 2028.
The instructions say combined separate limitation losses above combined separate limitation income reduce U.S. source income, and any remaining excess is treated as a net operating loss under section 172.