Lines a to d
The separate category code, the country code for a sanctioned country when code 901j is used, the treaty country code when an RBT code is used, and the box for the Regulations section 1.905-5(e) election.
1118 Sch. L
Foreign Tax Redeterminations
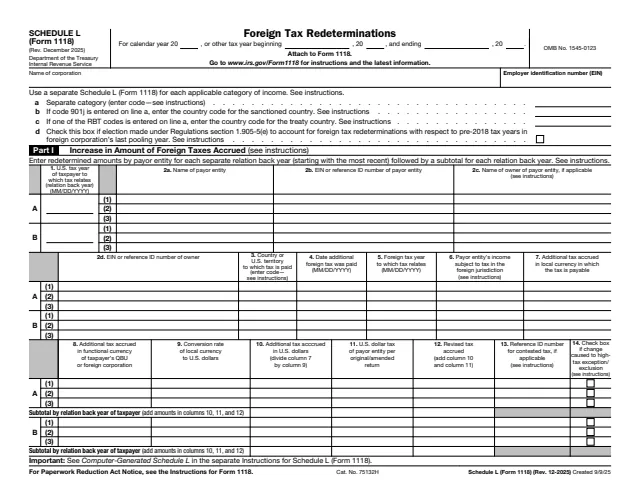
Schedule L (Form 1118), Foreign Tax Redeterminations, is a four-page schedule attached to Form 1118, Foreign Tax Credit, Corporations. The IRS About page says it is used to report foreign tax redeterminations that occurred in the current taxable year and that relate to prior taxable years.
The instructions define a foreign tax redetermination as a change in the liability for foreign income taxes, for example when accrued foreign taxes differ from the amounts claimed as credits, are not paid within 24 months after the close of the tax year they relate to, or are fully or partially refunded. Parts I and II report increases and decreases by payor entity, Parts III and IV report the changes in inclusions, credits and U.S. tax liability, and Part V covers contested taxes.
The schedule says "Attach to Form 1118." You can fill out Schedule L free in your browser on this page and download it without an account.
The separate category code, the country code for a sanctioned country when code 901j is used, the treaty country code when an RBT code is used, and the box for the Regulations section 1.905-5(e) election.
Fourteen columns by payor entity and relation back year: payor and owner details, country code, dates, income subject to foreign tax, additional tax in local and functional currency, conversion rate, U.S. dollar amounts and check boxes.
The same layout for taxes refunded or deemed refunded, with a box for when the section 905(c)(2) two-year rule applies.
Seventeen columns comparing redetermined and original amounts of direct section 901 and 903 taxes, section 951(a)(1) and 951A inclusions, deemed paid taxes and foreign tax credit claimed, on an overall taxpayer basis.
For each relation back year or affected tax year, the total redetermined U.S. tax liability, the liability per the original or amended return, and the difference.
Relation back year, payor entity, reference ID number, country, amount provisionally claimed, whether the contest is ongoing or resolved, the date resolved, tax refunded and additional tax paid.
Enter the tax year, the corporation's name and EIN. On line a, enter the same separate category code shown on the Form 1118 the schedule relates to, and complete lines b to d if they apply.
Enter the ending date of each relation back year, the payor entity's name and EIN or a reference ID number, the country code, dates and amounts. The instructions say not to enter "FOREIGNUS" or "APPLIED FOR" for the EIN.
The instructions say to report exchange rates as the units of foreign currency that equal one U.S. dollar, rounded to at least four places, not as U.S. dollars per unit of foreign currency.
Enter refunded or deemed refunded amounts. For taxes deemed refunded under the two-year rule, the instructions say to enter the date 24 months after the close of the tax year and check column 13.
Report the redetermined and original amounts on an overall taxpayer basis. The instructions say Part IV is completed only once, in the "TOTAL" version of the schedule.
For each contested tax with a provisional credit, enter the reference ID number from Form 7204, check ongoing or resolved, and enter the date resolved, tax refunded and additional tax paid if any.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says "Attach to Form 1118." The instructions say it is attached to the income tax return for the tax year in which the foreign tax redetermination occurs.
The instructions say the "TOTAL" Schedule L is filed with the same category of income that completes Form 1118, Schedule B, Part III.
The instructions say that if U.S. tax liability for any year changes because of the redetermination, an amended return is also filed for that year. If U.S. tax due does not change, no amended return is needed.
The instructions say all information on Schedule L is reported in English and all amounts are stated in U.S. dollars, unless the schedule says otherwise.
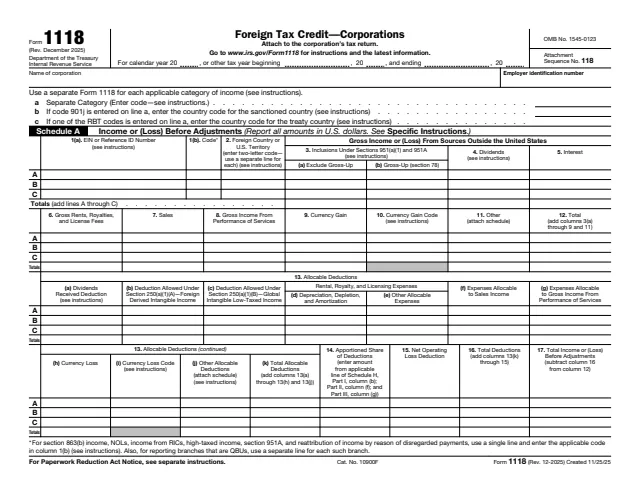
1118
1,263 fields, 12 pages
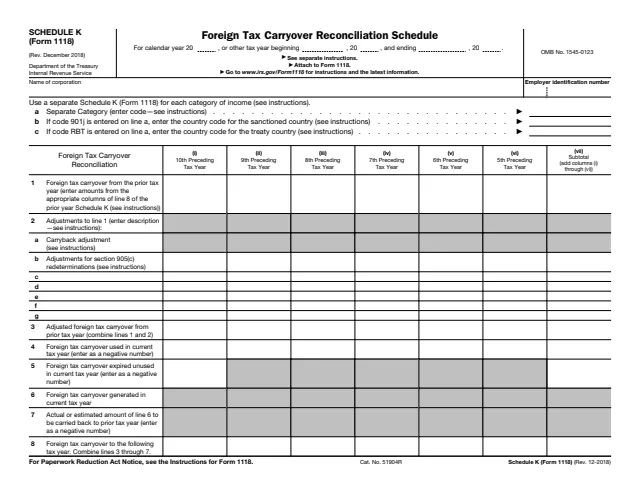
1118 Sch. K
231 fields, 2 pages
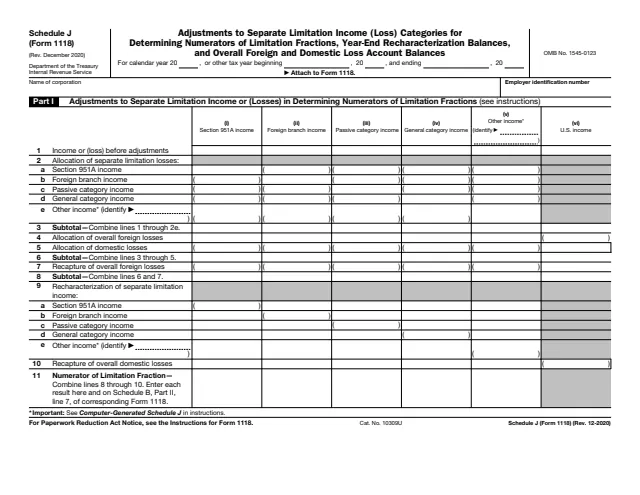
1118 Sch. J
227 fields, 2 pages
1118 Sch. I
113 fields, 2 pages
7204
18 fields, 1 page
Form 1118 is the foreign tax credit form for corporations, and Schedule L asks for the name and EIN of the corporation. The instructions say any taxpayer that has a foreign tax redetermination under section 905(c) completes the schedule.
No tool matches that search.
The instructions define it as a change in the liability for foreign income taxes, including when accrued taxes differ from amounts claimed as credits, are not paid within 24 months, or are fully or partially refunded.
The instructions say it is the U.S. tax year in which the foreign taxes being redetermined were originally taken into account.
Yes. The instructions say the schedule is submitted whether or not the redetermination changed the taxpayer's U.S. tax liability, and filing it satisfies the reporting requirement when no amended return is needed.
One for each applicable separate category of income, plus a "TOTAL" Schedule L that aggregates them, even when there is only one category.
As the units of foreign currency that equal one U.S. dollar, rounded to at least four places. The instructions call this the divide-by convention.
The instructions say previous column 9 of Part V was split into two columns: column 9 for tax refunded, if any, and column 10 for additional tax paid, if any.