Page 1: items A through H
Date of IC-DISC election, business activity code, EIN, date incorporated, total assets, return type boxes, owners of 50%-or-more of voting stock, and the intercompany pricing rules applied.
1120-IC-DISC
Interest Charge Domestic International Sales Corporation Return
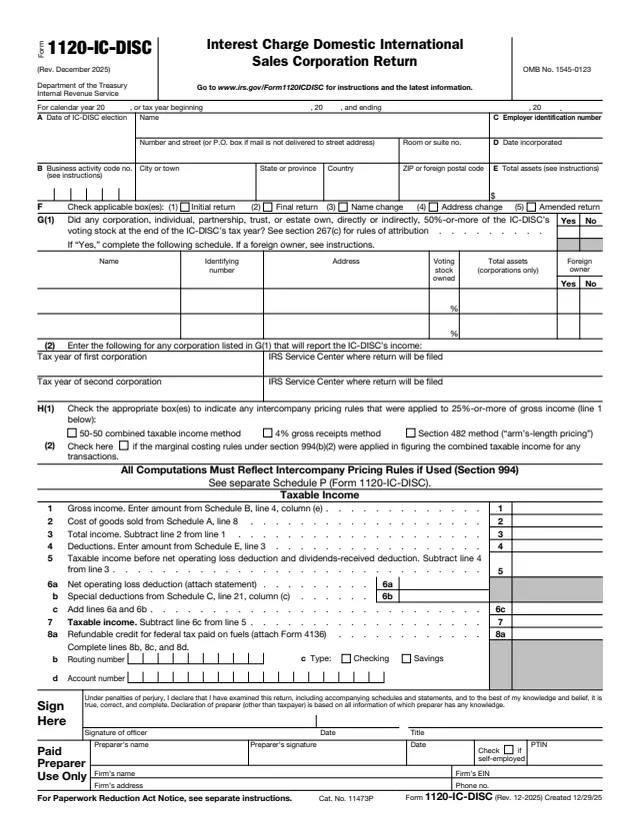
Form 1120-IC-DISC, Interest Charge Domestic International Sales Corporation Return, is an information return filed by interest charge domestic international sales corporations (IC-DISCs), former DISCs and former IC-DISCs. The instructions say an IC-DISC is a domestic corporation that has elected IC-DISC status on Form 4876-A and whose election is still in effect.
The instructions say an IC-DISC is generally not taxed on its income, and its shareholders are taxed when the income is actually or deemed distributed. The return reports taxable income, gross income by type of export receipt, deductions, deemed and actual distributions, balance sheets and other information. Each shareholder who received a distribution or was reported deferred DISC income gets a Schedule K (Form 1120-IC-DISC).
This page hosts the December 2025 revision. You can fill out Form 1120-IC-DISC free in your browser on this page and download it without an account.
Date of IC-DISC election, business activity code, EIN, date incorporated, total assets, return type boxes, owners of 50%-or-more of voting stock, and the intercompany pricing rules applied.
Gross income from Schedule B, cost of goods sold from Schedule A, deductions from Schedule E, special deductions, taxable income, a refundable credit for federal tax paid on fuels, and direct deposit details.
Cost of goods sold; gross income split into qualified export receipts, other qualified export receipts and nonqualified gross receipts; dividends, inclusions and special deductions; and deductions.
Deemed and Actual Distributions and Deferred DISC Income for the Tax Year.
Balance sheets per books, reconciliation of book income with income per return, and analyses of other earnings and profits, previously taxed income and accumulated IC-DISC income.
Export gross receipts of the IC-DISC and related U.S. persons with product codes, and Other Information with Yes or No questions on the 95% tests, stock, separate books, boycotts and section 163(j).
Enter the tax year, name, address, election date, the principal business activity code from the list at the end of the instructions, EIN, date incorporated and total assets. Check any boxes that apply, such as Initial return or Amended return.
Answer the 50%-or-more ownership question and list any such owner, with the tax year and IRS Service Center of any corporation that will report the IC-DISC's income. Check the intercompany pricing rules applied.
Complete Schedules A, B, C and E. The form says all computations reflect intercompany pricing rules if used, and points to Schedule P (Form 1120-IC-DISC).
Carry the schedule totals to page 1 and figure taxable income. Complete lines 8b through 8d if a refund is to be deposited.
Report distributions and deferred DISC income, balance sheets and reconciliations, export gross receipts and other information. Attach a Schedule K for each shareholder who needs one.
An authorized officer signs and dates the return. The instructions say a former DISC or former IC-DISC writes "Former DISC" or "Former IC-DISC" across the top and completes Schedules J, L and M and Schedule K.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file by the 15th day of the 9th month after the IC-DISC's tax year ends. No extensions are allowed.
The instructions point to the IRS page Where to file tax returns, addresses listed by return type, and allow certain IRS-designated private delivery services.
The instructions say to attach schedules and forms after the last page in this order: Schedule N (Form 1120), Form 4136, Schedule D (Form 1120), Form 8992, Form 8993, other schedules, then other forms.
The instructions list $100 for each instance of not providing required information, up to $25,000 during the calendar year, and $1,000 for not filing a return, unless there was reasonable cause.
The instructions say an interest charge of 4½% applies when a distribution to meet the qualification requirements is made after the return is due, payable within 30 days of the distribution.
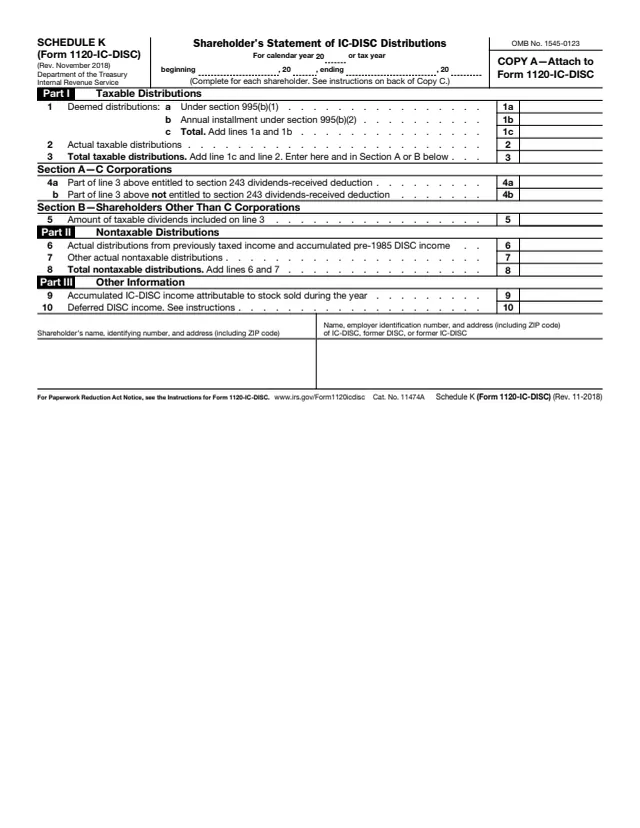
1120-IC-DISC Sch. K
60 fields, 5 pages
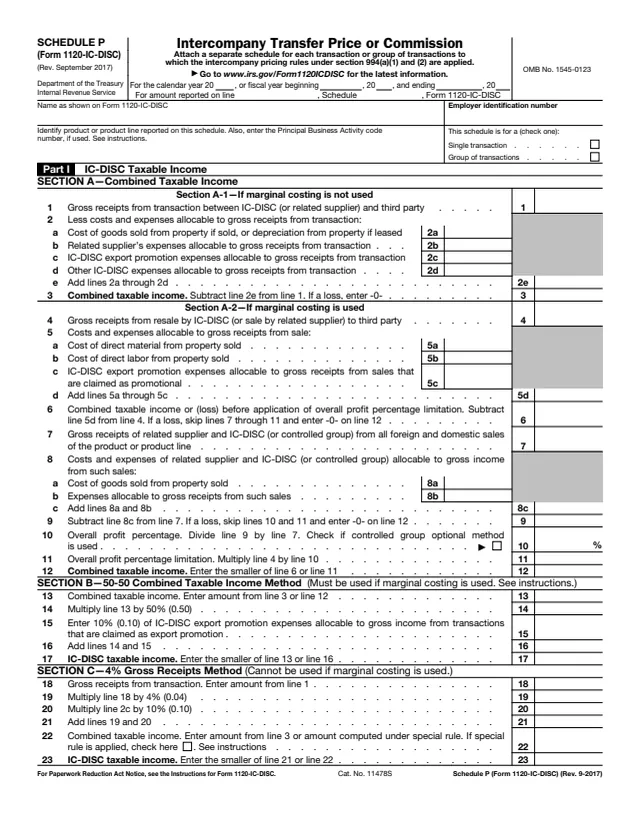
1120-IC-DISC Sch. P
56 fields, 2 pages
1120-IC-DISC
11 fields, 1 page
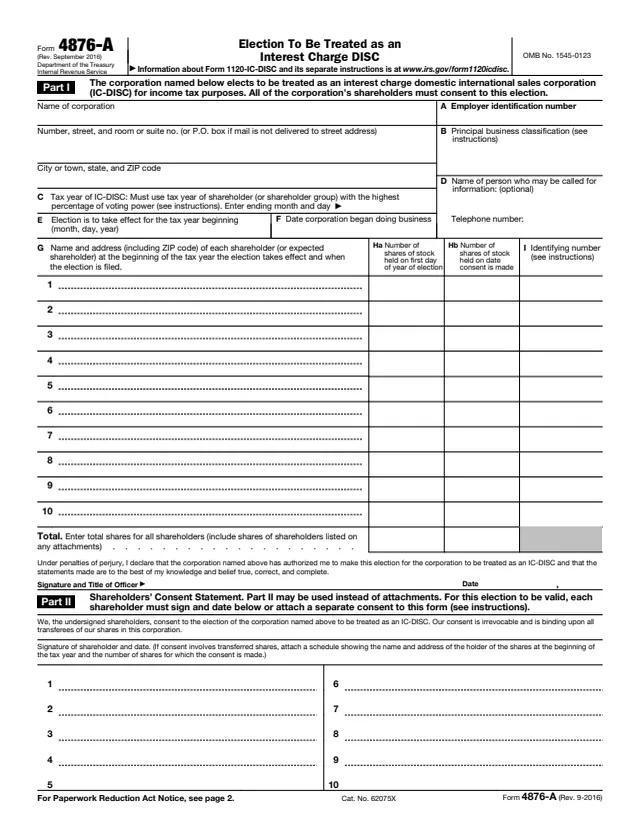
4876-A
74 fields, 2 pages
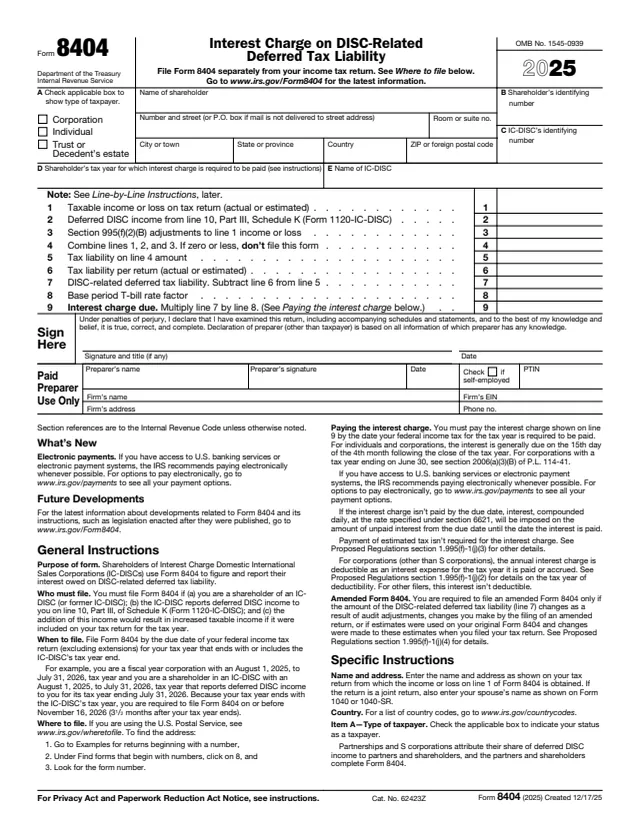
8404
30 fields, 2 pages
5713
383 fields, 4 pages
The return is filed by the corporation, not by its shareholders. The instructions say a corporate officer signs it, and a paid preparer signs the Paid Preparer Use Only area when one is used.
No tool matches that search.
The instructions say it is a domestic corporation that has elected to be an IC-DISC and whose election is still in effect. The election is made on Form 4876-A.
The instructions say an IC-DISC is generally not taxed on its income. Shareholders are taxed when the income is actually or deemed distributed, and Form 8404 covers the shareholder interest charge.
No. The instructions say the return is due by the 15th day of the 9th month after the tax year ends and no extensions are allowed.
The instructions list at least 95% of gross receipts as qualified export receipts, qualified export assets of at least 95% of total adjusted basis, one class of stock of at least $2,500 par or stated value, and separate books and records.
No. The instructions say they need not complete lines 1 through 8 and the taxable income schedules, but complete Schedules J, L and M and Schedule K (Form 1120-IC-DISC).
Each shareholder who received an actual or deemed distribution during the tax year, or to whom the corporation reported deferred DISC income.