Header
The calendar or tax year, the shareholder's name, identifying number and address, and the name, EIN and address of the IC-DISC, former DISC or former IC-DISC.
1120-IC-DISC Sch. K
Shareholder's Statement of IC-DISC Distributions
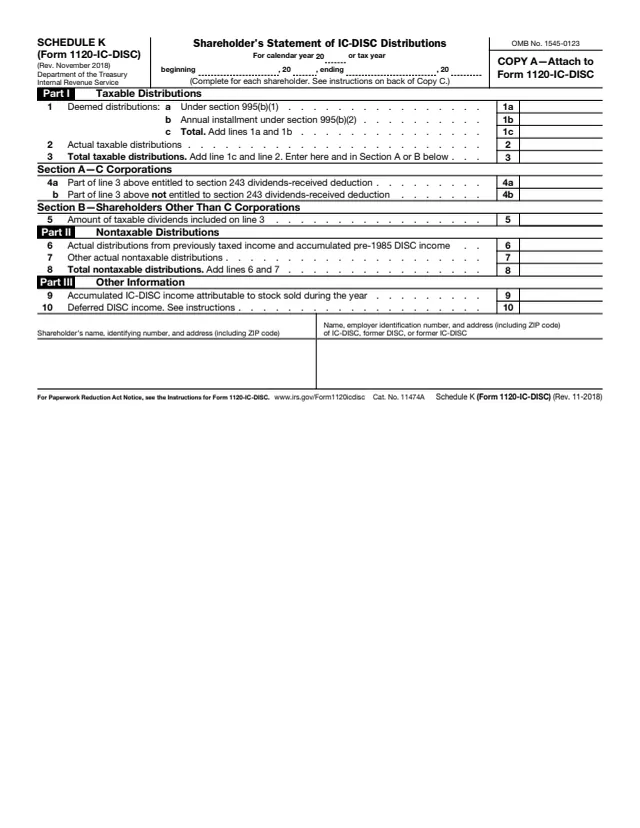
Schedule K (Form 1120-IC-DISC), Shareholder's Statement of IC-DISC Distributions, is completed by an interest charge domestic international sales corporation (IC-DISC), a former DISC or a former IC-DISC, one schedule for each shareholder. The IRS says it reports an actual or deemed distribution from an IC-DISC, former IC-DISC or former DISC, and also reports deferred DISC income from an IC-DISC.
The schedule comes in three copies. The instructions for the IC-DISC say to attach Copy A to Form 1120-IC-DISC, give Copy B to the shareholder, and keep Copy C for the corporation's records. The instructions for the shareholder, printed on the back of Copy B, say to keep it for your records and not to file it with your income tax return.
You can fill out the PDF free in your browser on this page and download it without an account.
The calendar or tax year, the shareholder's name, identifying number and address, and the name, EIN and address of the IC-DISC, former DISC or former IC-DISC.
Deemed distributions under section 995(b)(1) and the annual installment under section 995(b)(2), their total, actual taxable distributions, and total taxable distributions on line 3.
For C corporations: the part of line 3 entitled to the section 243 dividends-received deduction and the part not entitled to it.
For shareholders other than C corporations: the amount of taxable dividends included on line 3.
Actual distributions from previously taxed income and accumulated pre-1985 DISC income, other actual nontaxable distributions, and their total.
Accumulated IC-DISC income attributable to stock sold during the year, and deferred DISC income.
On line 1a, enter the shareholder's pro rata share of the deemed distributions under section 995(b)(1). On line 1b, enter the pro rata share of the annual installment under section 995(b)(2). The instructions say the totals for all shareholders should equal what the corporation reports in Parts I and III of Schedule J, Form 1120-IC-DISC.
On line 2, enter the actual distributions taxable to the shareholder, which come from accumulated IC-DISC income and other earnings and profits. Line 3 adds line 1c and line 2, and the total also goes in Section A or B.
Line 4a holds dividends out of other earnings and profits eligible for the section 243 deduction. The instructions list three kinds of dividend with no deduction: paid out of accumulated IC-DISC or pre-1985 DISC income, paid out of previously taxed income, or a deemed distribution under section 995(b)(1). Line 5 is for individuals, partnerships, S corporations, estates or trusts.
Line 6 is the shareholder's share of actual distributions from previously taxed income and accumulated pre-1985 DISC income; the total for all shareholders should equal Schedule J, Part IV, line 4a. Line 7 is other actual nontaxable distributions; that total should equal Schedule J, Part IV, line 4d.
Line 9 applies when a shareholder disposes of stock, or the stock is disposed of in a transaction that ends the corporation's separate existence: enter the accumulated IC-DISC income from the period the shareholder held the stock. Line 10 is the shareholder's share of deferred DISC income at year end; the total should equal Schedule J, Part V, line 3.
Attach Copy A to Form 1120-IC-DISC, give Copy B to the shareholder, and keep Copy C.
These steps follow the Instructions for IC-DISC printed on the back of Copy C.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attached to Form 1120-IC-DISC, one for each shareholder.
The instructions say to give Copy B to the shareholder by the last day of the second month after the corporation's tax year ends.
Kept for the IC-DISC's records.
The instructions say not to report actual and deemed distributions or deferred DISC income on Form 1099-DIV.
The shareholder keeps Copy B and does not file it with the income tax return. If line 10 shows deferred DISC income, the instructions point to Form 8404 to figure the interest charge under section 995(f).
1120-IC-DISC
483 fields, 7 pages
8404
30 fields, 2 pages
1120-IC-DISC Sch. P
56 fields, 2 pages
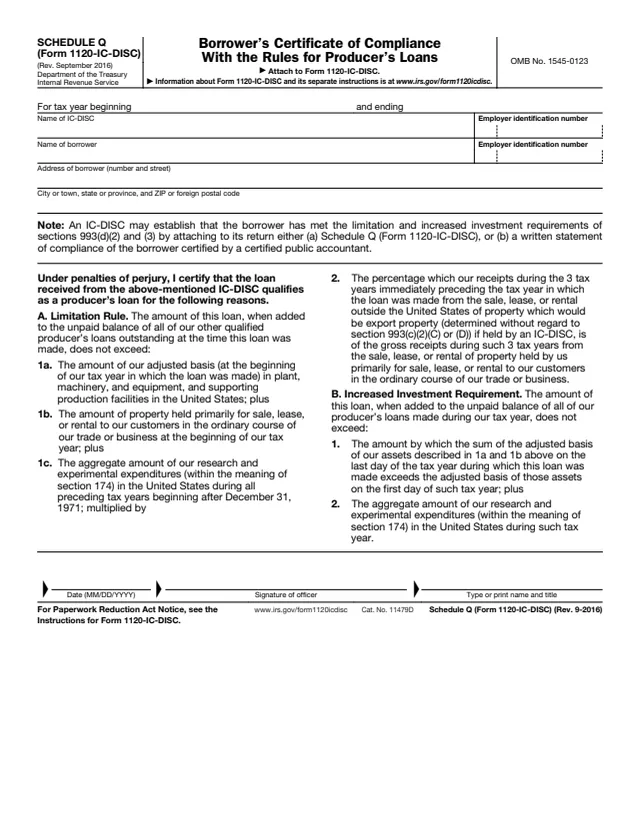
1120-IC-DISC
11 fields, 1 page
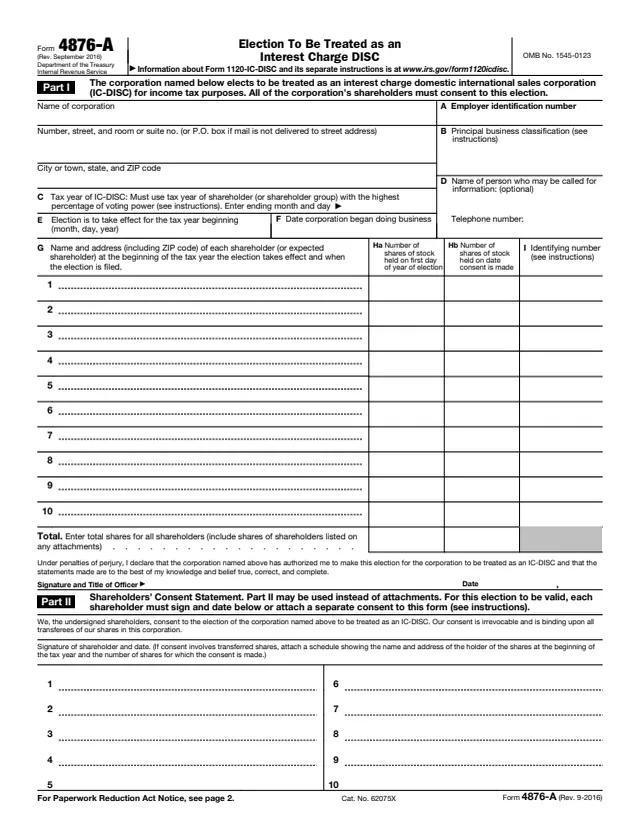
4876-A
74 fields, 2 pages
1099-DIV
140 fields, 6 pages
The corporation completes the schedule. The shareholder receives Copy B and keeps it.
No tool matches that search.
The IC-DISC, former DISC or former IC-DISC completes one for each shareholder who had an actual or deemed distribution during the tax year, or to whom it reports deferred DISC income.
No. The shareholder instructions say to keep Copy B for your records and not file it with your income tax return.
The instructions say by the last day of the second month after the corporation's tax year ends.
No. The instructions say not to report actual and deemed distributions or deferred DISC income on Form 1099-DIV.
The shareholder instructions say line 4a shows the part of the line 3 total that qualifies for the 50% or 65% dividends-received deduction under section 243, and line 4b the part that does not.
It is the shareholder's share of the IC-DISC's deferred income for the year. The instructions say section 995(f) imposes an interest charge on it, figured on Form 8404.