Header
The corporation's name and employer identification number (EIN).
1120 Sch. B
Additional Information for Schedule M-3 Filers
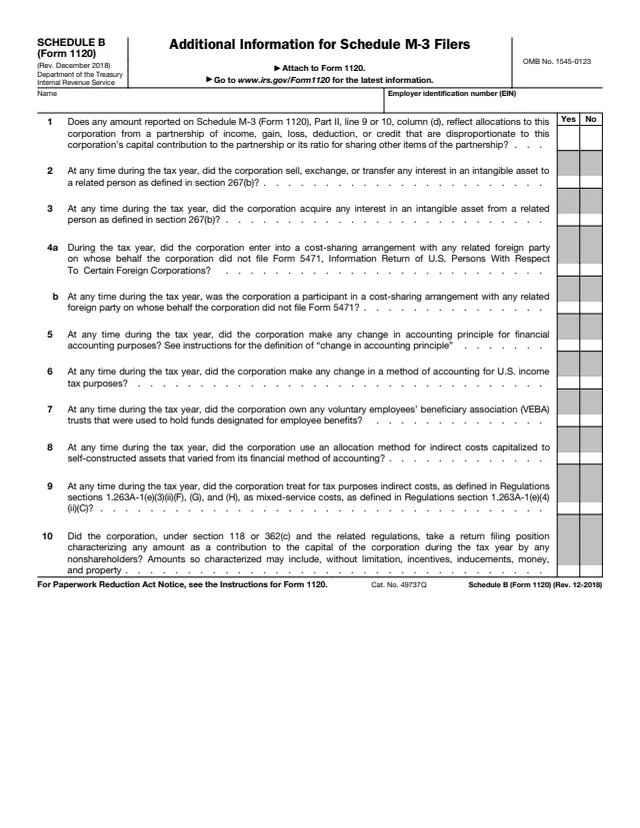
Schedule B (Form 1120), Additional Information for Schedule M-3 Filers, is a corporate attachment to Form 1120. The About page says filers of Schedule M-3 (Form 1120), Net Income (Loss) Reconciliation for Corporations With Total Assets of $10 Million or More, use it to provide answers to additional questions.
The schedule is a set of yes or no questions about the tax year: disproportionate partnership allocations, transfers or acquisitions of intangible assets with related persons, cost-sharing arrangements with related foreign parties, changes in accounting principle or method, VEBA trusts, indirect costs and nonshareholder contributions to capital. It prints "Attach to Form 1120" and asks for the corporation's name and employer identification number (EIN). Instructions are printed on page 2 of the PDF.
You can fill out the PDF free in your browser on this page and download it without an account.
The corporation's name and employer identification number (EIN).
Whether Schedule M-3 Part II, line 9 or 10, column (d) reflects partnership allocations disproportionate to the corporation's capital contribution or sharing ratio.
Transfers or acquisitions of intangible assets with related persons under section 267(b), and cost-sharing arrangements with related foreign parties without a Form 5471.
Changes in accounting principle for financial accounting purposes and changes in a method of accounting for U.S. income tax purposes.
Ownership of VEBA trusts holding funds for employee benefits, indirect cost allocation for self-constructed assets, and mixed-service cost treatment.
Whether the corporation took a filing position under section 118 or 362(c) treating an amount from nonshareholders as a contribution to capital.
Enter the corporation's name and employer identification number as on Form 1120.
The instructions say to answer Yes if the corporation is a partner that received special allocations of income, gain, loss, deduction or credit from the partnership. They give a 99% depreciation allocation as an example.
The instructions say to answer Yes if a change from one generally accepted accounting principle to another during the year affected, or is expected to affect, income for financial statement purposes.
Answer whether the corporation changed a method of accounting for tax purposes. The instructions note corporations generally file Form 3115, or a statement in lieu of it, to request such a change.
Answer Yes for owned VEBA trusts holding employee benefit funds, for an indirect cost allocation method that varied from the financial statement method, and for purchasing, handling and storage costs treated as mixed-service costs.
Check Yes or No for questions 2, 3, 4a, 4b and 10 based on the corporation's activity during the tax year.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule prints "Attach to Form 1120." It is filed with the corporation's return, not on its own.
The parent corporation files one Schedule B for the entire group, according to the instructions.
The instructions say that after December 22, 2017, contributions by any civic group or any governmental entity are not eligible for exclusion under section 118, except governmental contributions under a master development plan approved before that date.
The schedule points to www.irs.gov/Form1120 for the latest information. The Paperwork Reduction Act Notice is in the Instructions for Form 1120.

1120
481 fields, 6 pages
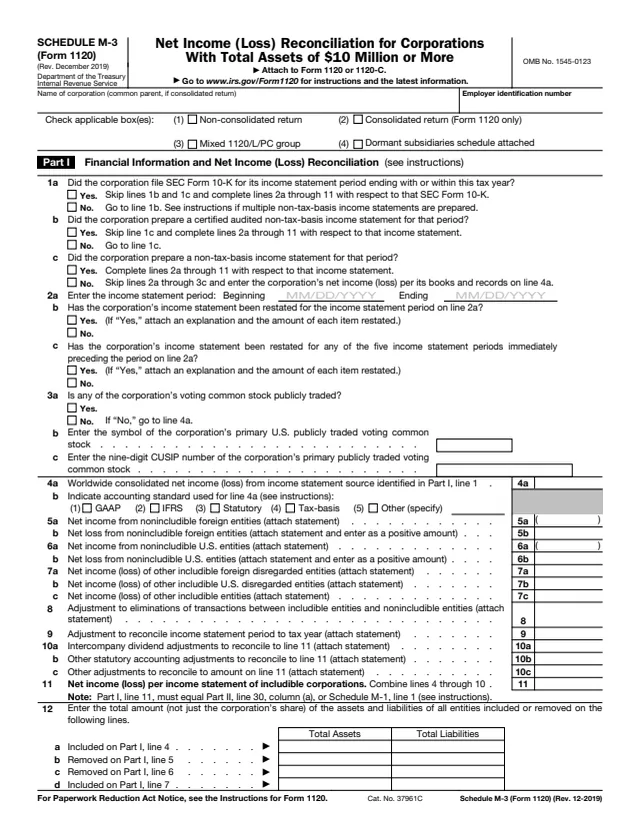
1120 Sch. M-3
380 fields, 3 pages
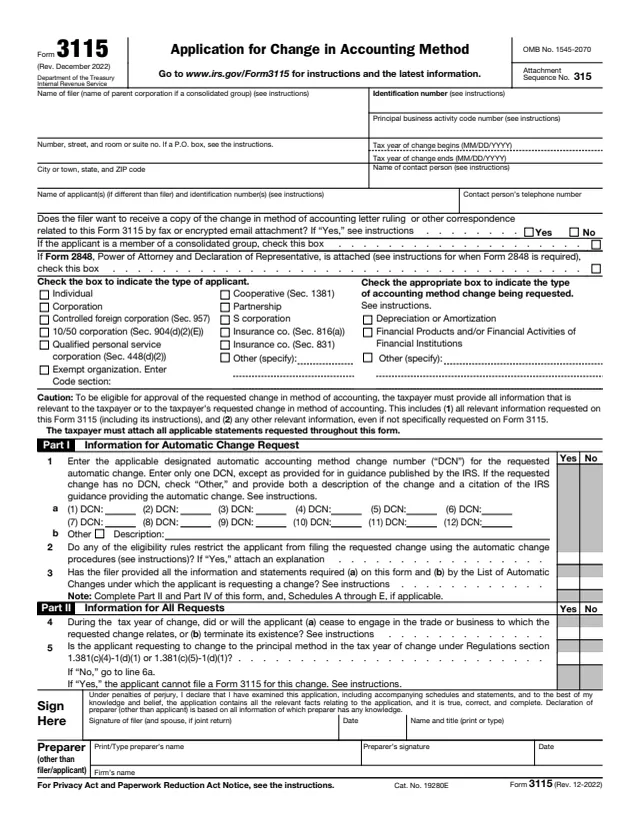
3115
294 fields, 8 pages

5471
437 fields, 6 pages
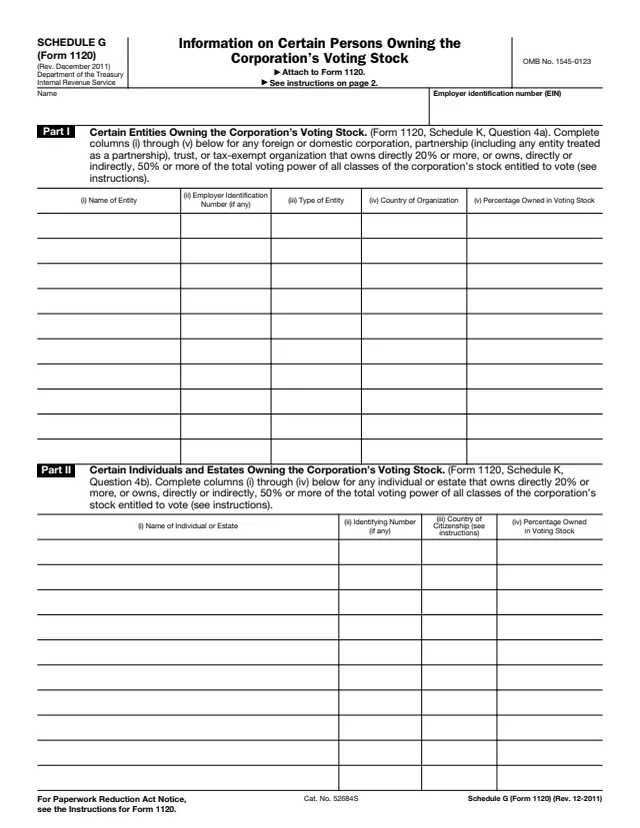
1120 Sch. G
92 fields, 2 pages
1120
48 fields, 1 page
The instructions say that, generally, filers of Form 1120 that file Schedule M-3 (Form 1120) complete and file Schedule B (Form 1120), with the exceptions below.
No tool matches that search.
Form 1120. The schedule prints "Attach to Form 1120."
No. The instructions exclude filers with less than $50 million in total assets at the end of the tax year and filers who file Schedule M-3 voluntarily.
One. The instructions say the parent corporation files one Schedule B for the entire group.
The instructions define it as a change from one generally accepted accounting principle to another, as described in SFAS No. 154, Accounting Changes and Error Corrections.
On page 2 of the PDF. The schedule also points to www.irs.gov/Form1120 for the latest information.