Header on each page
Plan name, Applicant's EIN and plan number, repeated at the top of every page.
14568-D
Model VCP Compliance Statement - Schedule 4 SIMPLE IRAs
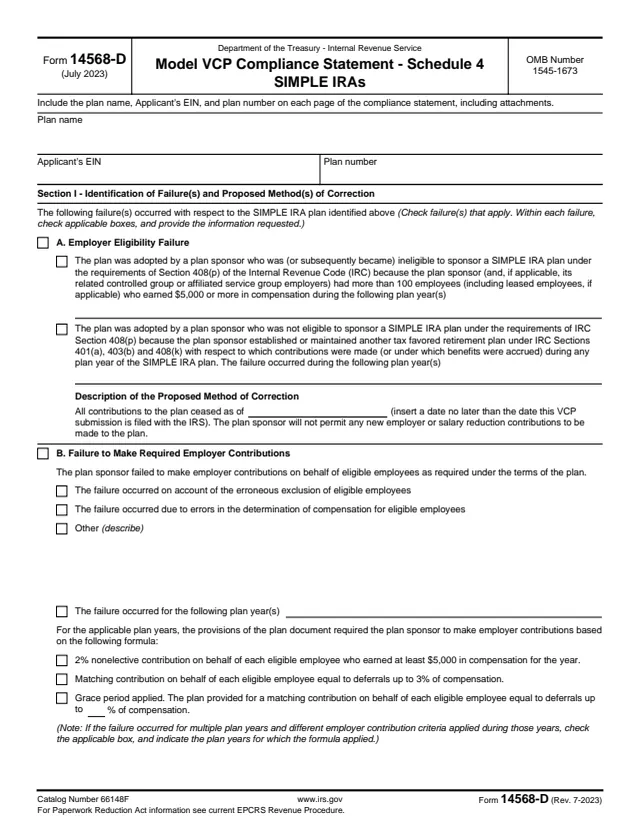
Form 14568-D is the Model VCP Compliance Statement, Schedule 4, for SIMPLE IRAs. It describes failures that occurred in a SIMPLE IRA plan and the proposed method of correcting each one, as part of a VCP submission filed with the IRS. The form says to include the plan name, the Applicant's EIN and the plan number on each page, including attachments.
Section I covers five failure types: employer eligibility, failure to make required employer contributions, failure to provide eligible employees with the opportunity to make elective deferrals, excess amounts contributed, and a written arrangement not timely updated for tax law changes. Each one prints its proposed method of correction. Sections II to IV cover changes in administrative procedures, a request for excise tax relief and the enclosures.
For Paperwork Reduction Act information, the form points to the current EPCRS Revenue Procedure. You can fill out Form 14568-D free in your browser on this page and download the result without an account.
Plan name, Applicant's EIN and plan number, repeated at the top of every page.
For a sponsor that had more than 100 employees who earned $5,000 or more in compensation, or that maintained another tax favored retirement plan. The correction states that all contributions ceased as of a date entered.
B covers required employer contributions not made, under a 2% nonelective or a matching formula. C covers eligible employees not given the opportunity to make elective deferrals, corrected at 1.5% of compensation adjusted for earnings.
D covers excess amounts contributed, corrected by distribution or return, with a separate box for excess amounts of $250 or less. E covers a plan not timely updated for EGTRRA as required by Revenue Procedure 2002-10.
Section II explains how and why the failures arose and the measures to keep them from recurring. Section III is a box requesting relief from the excise tax under IRC Section 4972.
A list of what to enclose: the plan document, a written explanation, any updated EGTRRA document, calculations for corrective contributions or distributions, and explanations for excise tax relief.
Enter the plan name, the Applicant's EIN and the plan number. The form says these go on each page of the compliance statement, including attachments.
In Section I, check each failure that applies, check the boxes inside it and enter the plan years. For failure B, check the contribution formula the plan document required.
Enter the total corrective contribution or distribution for each year, and for failure D the number of participants affected. Check one earnings method: actual investment results, the rate in the Department of Labor's VFCP Online Calculator, or a combination.
Check whether former employees are affected and, if so, describe the actions the plan sponsor will take to locate those who cannot be found.
Explain how and why the failures arose and the measures to keep them from recurring. Check Section III only to request excise tax relief, and the form says to enclose a written explanation supporting it.
Assemble the items Section IV lists, including the plan document in effect at the time of the failures and the supporting calculations. The form says to use estimates, including an estimated correction date, if corrections are not yet made.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The compliance statement is part of a VCP submission filed with the IRS. The form prints no mailing address.
For an employer eligibility failure, the date contributions ceased is a date no later than the date the VCP submission is filed with the IRS, the form says.
The form says that when a participant's total excess amount is $250 or less before earnings, the excess amount will not be distributed.
The form says the amount returned to the plan sponsor is reported on Form 1099-R as a distribution to the affected participant with the taxable amount as zero, and the sponsor is not entitled to a deduction for it.
The form points to the current EPCRS Revenue Procedure.
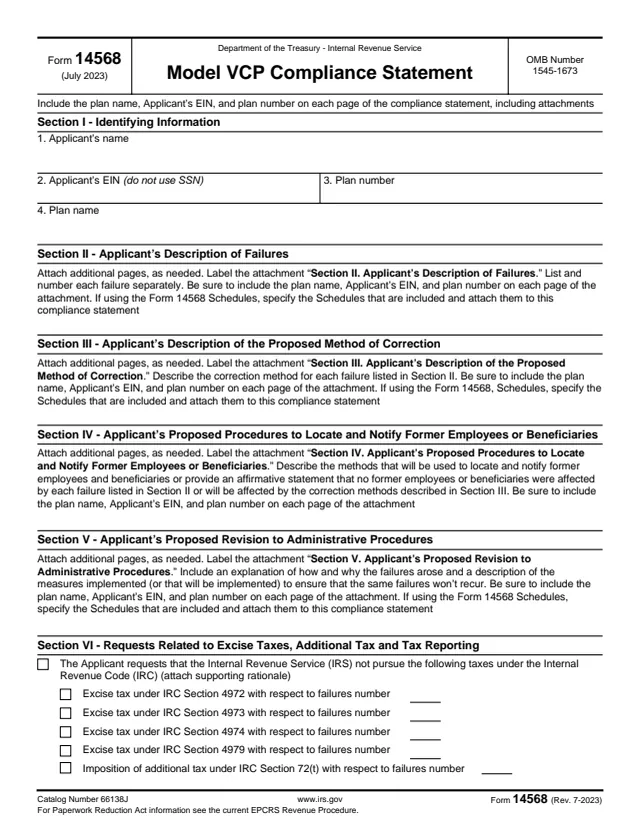
14568
45 fields, 3 pages
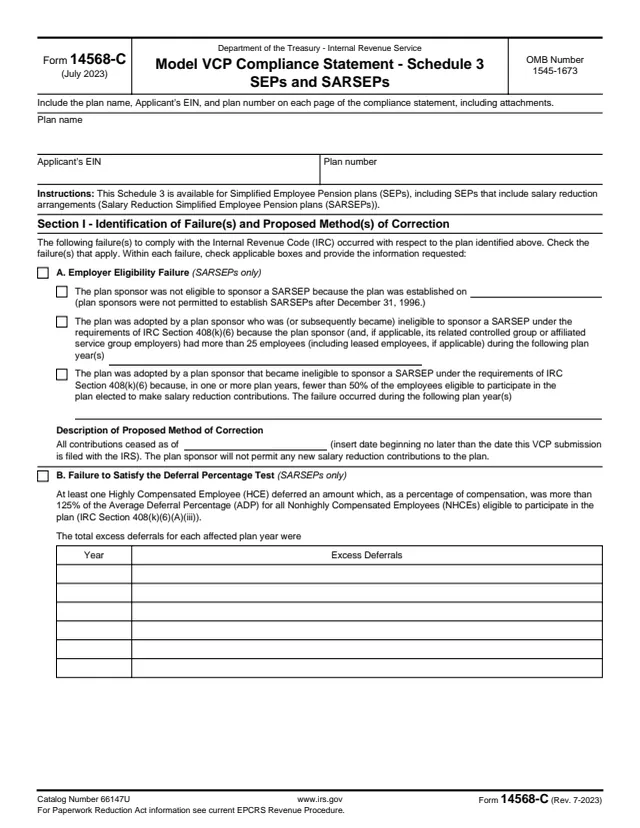
14568-C
178 fields, 8 pages
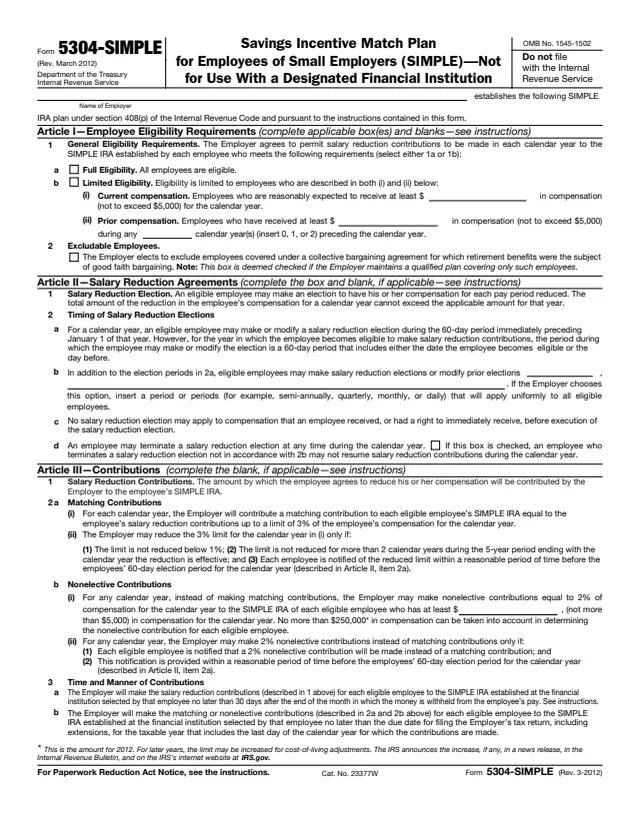
5304-SIMPLE
32 fields, 6 pages
5305-SIMPLE
32 fields, 6 pages
1099-R
257 fields, 9 pages
The form is completed for a SIMPLE IRA plan as part of a VCP submission. Its correction text describes what the plan sponsor has done or will do.
No tool matches that search.
It is Schedule 4 of the model VCP compliance statement, for SIMPLE IRAs. It lists failures in a SIMPLE IRA plan and the proposed method of correction for each.
Employer eligibility failures, failure to make required employer contributions, failure to provide eligible employees with the opportunity to make elective deferrals, excess amounts contributed, and a written arrangement not timely updated for tax law changes.
The form says the corrective contribution is 50% of an assumed deferral of 3% of compensation, which equals 1.5% of compensation, adjusted for earnings.
The form offers actual investment results of the employee's SIMPLE IRA, the interest rate in the Department of Labor's VFCP Online Calculator when actual earnings cannot be ascertained, or a combination of both.
Section IV lists the plan document in effect at the time of the failures, a written explanation, any updated EGTRRA document, supporting calculations, and explanations for excise tax relief requests.