Header and questions A and B
Tax year, name, address, EIN or SSN, the type of annual return (Form 990, 990-EZ, 990-PF, 5227 or Other), the foreign organization question and the question about filing for more than one organization.
4720
Return of Certain Excise Taxes Under Chapters 41 and 42 of the Internal Revenue Code
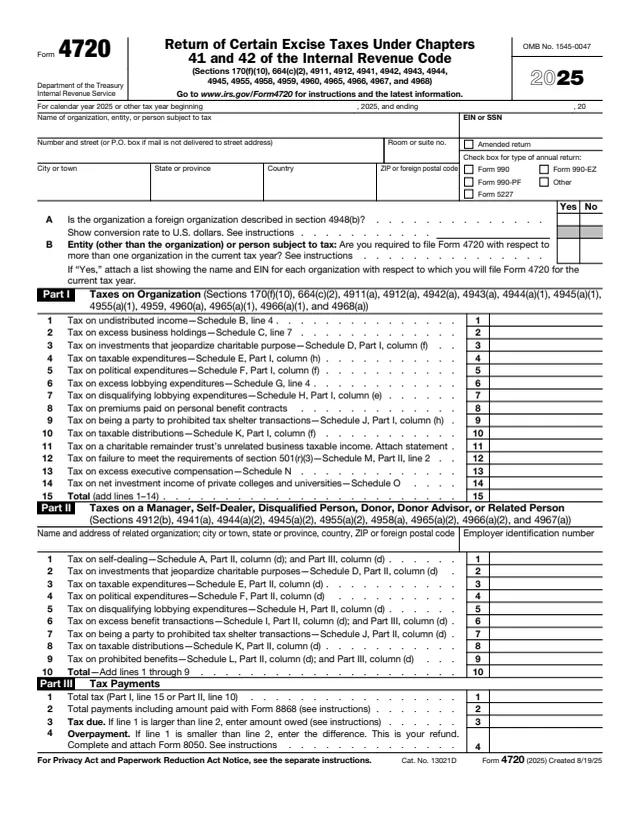
Form 4720, Return of Certain Excise Taxes Under Chapters 41 and 42 of the Internal Revenue Code, is used to figure and pay certain excise taxes in chapters 41 and 42 of the Internal Revenue Code. This is the 2025 form. The instructions list taxes such as the initial taxes on private foundations, disqualified persons and foundation managers for self-dealing, failure to distribute income, excess business holdings, investments that jeopardize charitable purpose and taxable expenditures, along with taxes on excess lobbying, political expenditures, excess benefit transactions, excess executive compensation and the net investment income of certain private colleges and universities.
The organization that owes tax files the form, and each manager, self-dealer, disqualified person, donor, donor advisor or related person who owes tax files a separate Form 4720. Organizations report their taxes in Part I, those persons report theirs in Part II, and Part III shows the total tax, payments and the amount due or overpaid. Schedules A through O figure each tax.
You can fill out Form 4720 free in your browser on this page and download it without an account.
Tax year, name, address, EIN or SSN, the type of annual return (Form 990, 990-EZ, 990-PF, 5227 or Other), the foreign organization question and the question about filing for more than one organization.
Lines 1 to 14 for each tax owed by the organization, from the tax on undistributed income to the tax on net investment income of private colleges and universities, totaled on line 15.
Lines 1 to 9 for taxes on a manager, self-dealer, disqualified person, donor, donor advisor or related person, with the related organization's name and EIN, totaled on line 10.
Total tax, total payments including the amount paid with Form 8868, tax due, and any overpayment, with Form 8050 attached for a refund.
One schedule per tax, from initial taxes on self-dealing (Schedule A) to the tax on excess executive compensation (Schedule N) and net investment income of private colleges and universities (Schedule O).
Signature of an officer or trustee, signature of a manager or other person subject to tax, the question on discussing the return with the preparer, and the Paid Preparer Use Only area.
Enter the tax year and the name, address and EIN or SSN of the organization, entity or person subject to tax. The instructions say an organization uses the same name, address and EIN as on its Form 990-PF, 5227, 990 or 990-EZ.
Question A asks about foreign organizations described in section 4948(b). A person filing for more than one organization answers Yes to B and attaches a list with each organization's name and EIN.
Read each applicable schedule's instructions first. The instructions say the organization completes all parts of each applicable schedule, including the tax on other persons, even though it is not liable for those amounts.
Carry the taxes from the schedules to Part I when filing as the organization, or to Part II when filing as a manager, self-dealer, disqualified person, donor, donor advisor or related person. The instructions say the organization makes no entries in Part II.
Enter the total tax, payments and either the tax due or the overpayment. The instructions say amounts from Part I and Part II cannot be combined in Part III.
A person authorized to sign signs the return, such as a corporate officer, an authorized partner or the trustee. The instructions say a person with a valid power of attorney may sign and includes a copy of it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
For Part I taxes, by the due date (not including extensions) of the organization's Form 990-PF, 990, 990-EZ or 5227, or by the 15th day of the 5th month after its accounting period ends if none is required. Part II filers file by the 15th day of the 5th month after the end of their tax year.
The instructions point to Form 8868 for an automatic extension of time to file, granted if it is properly completed, filed, and any balance due on Form 4720 is paid by its due date.
The instructions say private foundations reporting tax liability on Schedules A to F, J or N file electronically, and other filers required to file at least 10 returns of any type during the calendar year file electronically.
Filers in the United States: Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0027. Filers in a foreign country or a U.S. territory: Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
The instructions list EFTPS, electronic funds withdrawal for electronic filers, or a check payable to "United States Treasury" with the SSN or TIN and "Form 4720" written on it.
Form 843 is used to request abatement, refund or relief under section 4962. An amended return uses the same year form, checks the Amended Return box and includes a statement of the changes.
990-PF
1,147 fields, 13 pages
990
1,075 fields, 12 pages
5227
411 fields, 7 pages
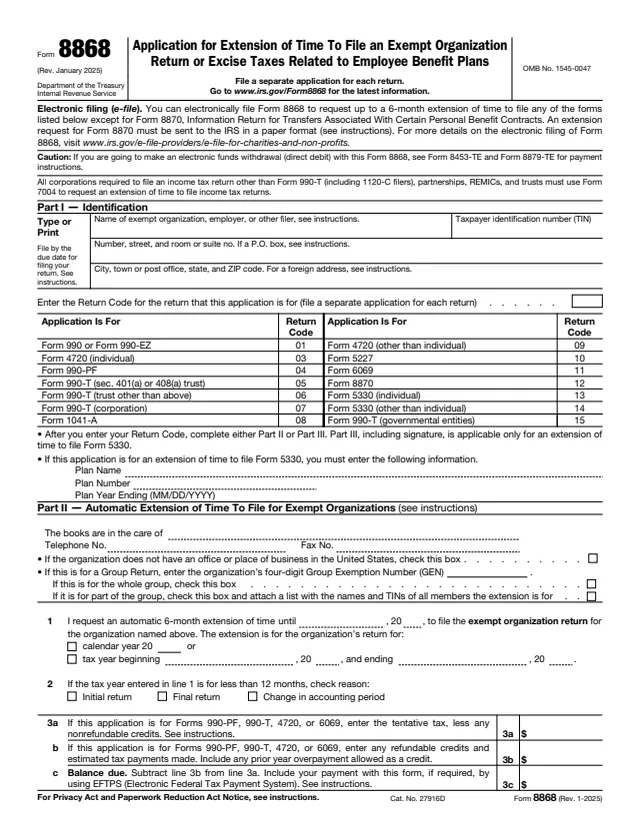
8868
47 fields, 2 pages
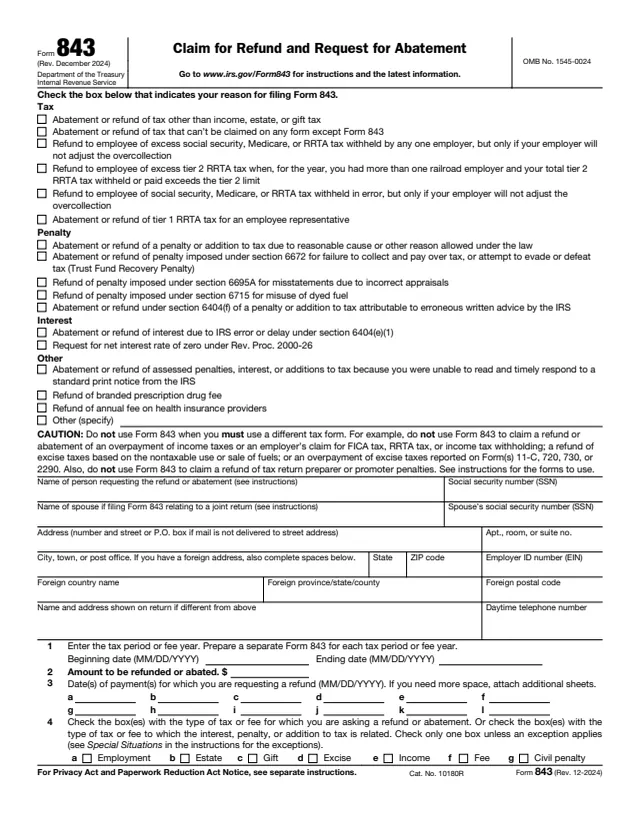
843
85 fields, 2 pages
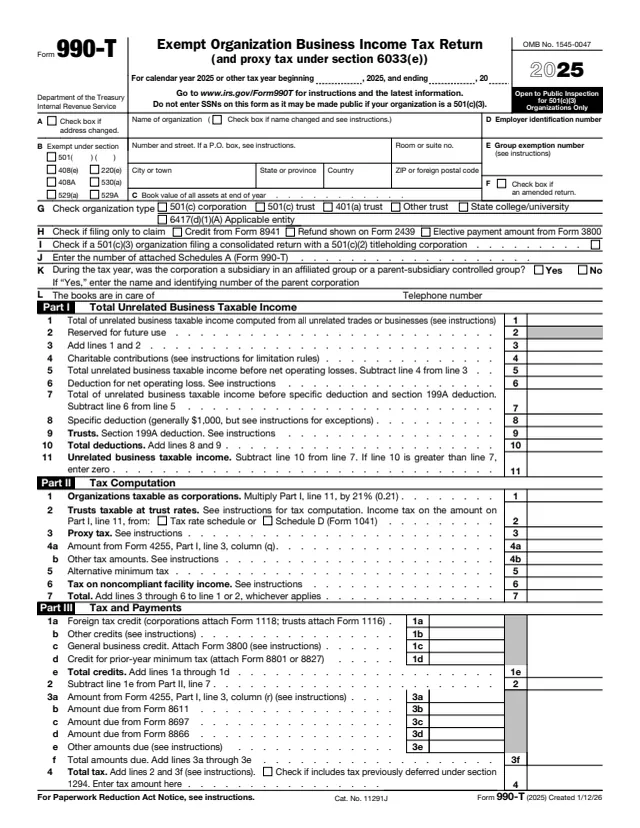
990-T
128 fields, 2 pages
The instructions name both organizations and persons, and say each taxpayer required to file Form 4720 files their own return.
No tool matches that search.
No. The instructions say a manager, self-dealer, disqualified person, donor, donor advisor or related person who owes tax may no longer report it on the organization's Form 4720. Each files a separate Form 4720.
The instructions say a private foundation reports a self-dealing transaction on Schedule A but does not pay the tax of any disqualified person or manager, and that managers and self-dealers should pay those taxes from their own funds.
For the organization, by the due date (not including extensions) of its Form 990-PF, 990, 990-EZ or 5227. Persons reporting in Part II file by the 15th day of the 5th month after the end of their tax year.
Filers not required to file electronically can mail it to the Ogden address in the instructions. The instructions say paper returns from organizations required to file electronically will not be accepted or processed.
The instructions say foreign organizations described in section 4948(b) complete and file the form in the same manner as domestic organizations, but they and their foundation managers and self-dealers don't have to pay any tax that would otherwise be due on this return.
Part III, line 4 shows the overpayment. The form says to complete and attach Form 8050, Direct Deposit of Tax Exempt or Government Entity Tax Refund.