Heading, items A to J
EIN, telephone, return type boxes, type of organization, fair market value of all assets at end of year, and accounting method.
990-PF
Return of Private Foundation or Section 4947(a)(1) Trust Treated as Private Foundation
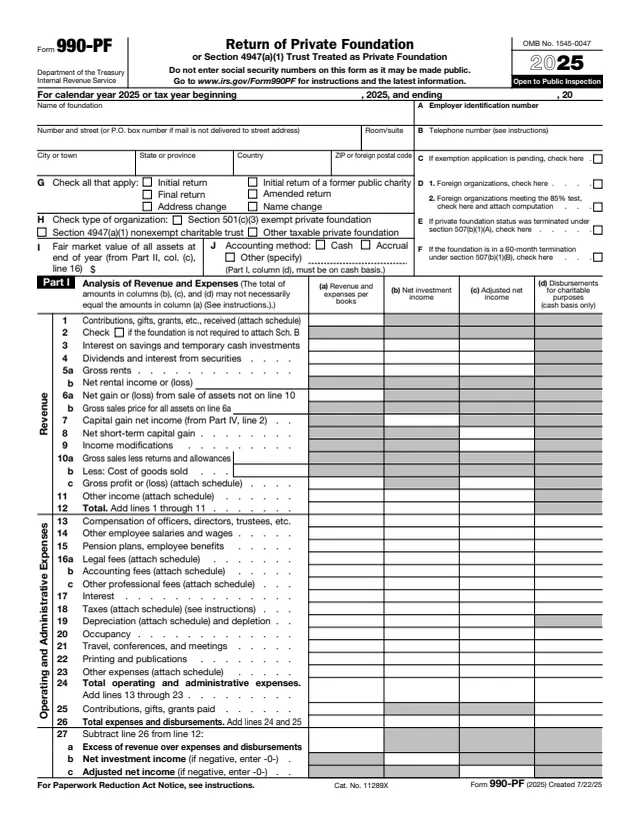
Form 990-PF, Return of Private Foundation or Section 4947(a)(1) Trust Treated as Private Foundation, is an annual information return. The instructions say it is used to figure the tax based on investment income and to report charitable distributions and activities. It also serves as a substitute for the income tax return of a section 4947(a)(1) nonexempt charitable trust, Form 1041, when the trust has no taxable income.
The return covers revenue and expenses, balance sheets, capital gains, the excise tax based on investment income, statements about activities, officers and pay, charitable activities, the minimum investment return, the distributable amount and qualifying distributions. The form is marked Open to Public Inspection and says not to enter social security numbers on it, as it may be made public.
This page has the 2025 form, for calendar year 2025 or a tax year beginning in 2025. The instructions say a 2025 Form 990-PF is required to be filed electronically. You can fill out the PDF free in your browser on this page to prepare or review it, and download the result without an account.
EIN, telephone, return type boxes, type of organization, fair market value of all assets at end of year, and accounting method.
Revenue and expenses in four columns, beginning and end of year balance sheets, and the analysis of changes in net assets or fund balances.
Capital gains and losses, then the excise tax. Line 1b shows 1.39% (0.0139) of line 27b for domestic foundations and 4% (0.04) for exempt foreign organizations.
Statements regarding activities, questions about acts for which Form 4720 may be required, officers, directors and highly paid employees, and charitable activities and program-related investments.
Minimum investment return, distributable amount, qualifying distributions, undistributed income, and the private operating foundation tests.
Supplementary information including grants paid, income-producing activities and transfers to noncharitable exempt organizations, then the officer's and paid preparer's signatures.
The instructions offer an order so amounts are ready when needed: Part IV first, then Parts I and II, the heading, Part III, Part VI-A, Part VII and onward.
Enter the tax year, name, EIN and address, check the return and organization type, and enter the end of year fair market value of all assets from Part II, column (c), line 16.
The instructions say to answer Yes, No or N/A to each question, make an entry (including a zero when appropriate) on all total lines, and enter None or N/A if an entire part does not apply.
Part I, column (d), disbursements for charitable purposes, is completed on the cash receipts and disbursements method, as the form and instructions say.
The instructions say all domestic foundations complete Part IX. The form says to complete Part XIV only if the foundation had $5,000 or more in assets at any time during the year.
An authorized officer or trustee signs, dates and enters a title. A paid preparer, if any, completes the Paid Preparer Use Only area.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say by the 15th day of the 5th month following the close of the foundation's tax year, or the next business day if that falls on a Saturday, Sunday or legal holiday.
The instructions say a 2025 Form 990-PF is required to be filed electronically, and point to IRS.gov/EOefile for e-file providers.
The instructions say a foundation generally uses Form 8868 to request an automatic extension of time to file its return.
The instructions list $25 a day ($130 a day for a large organization), up to the lesser of $13,000 ($65,000 for a large organization) or 5% of gross receipts, unless due to reasonable cause.
If state law requires it, foundation managers furnish a copy of Form 990-PF to the state Attorney General at the same time the return is filed with the IRS.
The instructions say a private foundation makes its annual returns and exemption application available for public inspection.
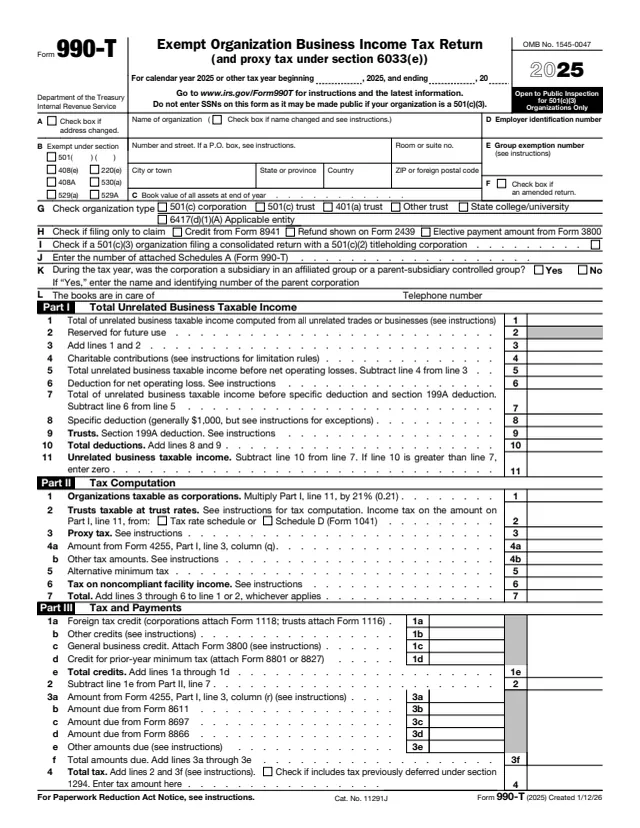
990-T
128 fields, 2 pages
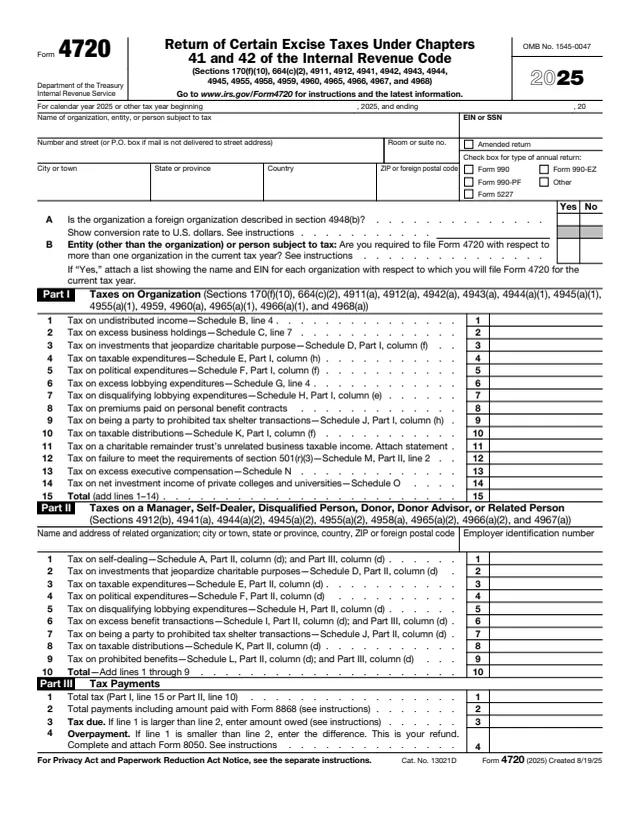
4720
666 fields, 10 pages
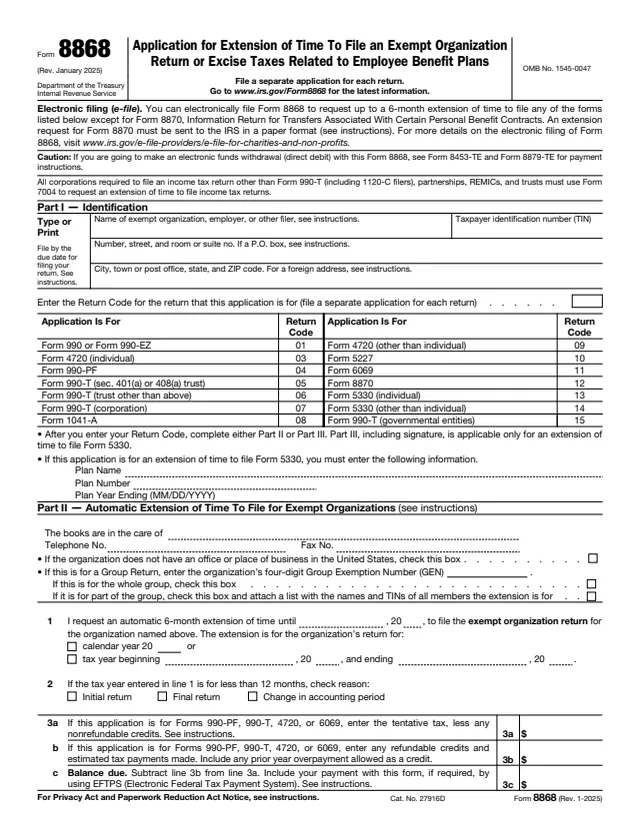
8868
47 fields, 2 pages

1041
173 fields, 3 pages
990 Sch. B
201 fields, 4 pages
2220
322 fields, 4 pages
The instructions list the organizations that file it. An authorized officer signs it, or the authorized trustee for a trust.
No tool matches that search.
The instructions list private foundations exempt under section 501(a), taxable private foundations, section 4947(a)(1) nonexempt charitable trusts treated as private foundations, and certain organizations with pending or claimed private foundation status.
The instructions say by the 15th day of the 5th month following the close of the foundation's tax year, moved to the next business day when it falls on a weekend or legal holiday.
The instructions say a 2025 Form 990-PF is required to be filed electronically. They add that e-file is only available for the current tax year and 2 prior tax periods, and that older returns are paper filed.
The instructions say a foundation generally uses Form 8868 to request an automatic extension of time to file its return.
The form is marked Open to Public Inspection, and it says not to enter social security numbers on it as it may be made public.
Part V, line 1b shows 1.39% (0.0139) of line 27b for domestic foundations, and 4% (0.04) of Part I, line 12, column (b) for exempt foreign organizations.
The instructions say a trust with no taxable income may use Form 990-PF to satisfy its Form 1041 filing requirement by checking the box on Part VI-A, line 15.