Article I: Eligibility Requirements
Blanks for a minimum age (not to exceed 21) and years of service (not to exceed 3 of the immediately preceding 5), and boxes for union employees, certain nonresident aliens and employees paid less than $450*.
5305A-SEP
Salary Reduction Simplified Employee Pension--Individual Retirement Accounts Contribution Agreement
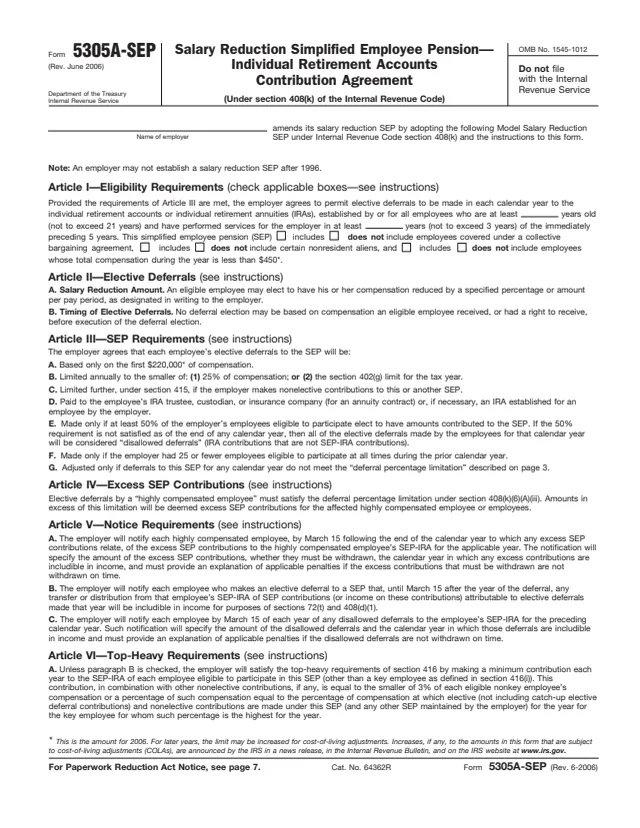
Form 5305A-SEP is the IRS model salary reduction simplified employee pension (SEP) under section 408(k). The instructions say an employer uses it to permit employees to make elective deferrals to a SEP: employees choose whether to have part of their pay contributed to a traditional IRA set up by or for each of them, or to receive it in cash.
The form prints a note that an employer may not establish a salary reduction SEP after 1996. The instructions add that a SEP permitting elective deferrals that was established before 1997 may continue to be maintained. The opening line reads that the named employer amends its salary reduction SEP by adopting this model.
The 8-page PDF holds the agreement, the employer and employee instructions, a model deferral election form, a model notice of excess SEP contributions and a deferral percentage worksheet. The form says not to file it with the IRS. You can fill out the PDF free in your browser on this page and download it without an account.
Blanks for a minimum age (not to exceed 21) and years of service (not to exceed 3 of the immediately preceding 5), and boxes for union employees, certain nonresident aliens and employees paid less than $450*.
How employees elect salary reduction, and the limits: the first $220,000* of compensation, the smaller of 25% of compensation or the section 402(g) limit, and the 50% and 25-employee rules.
The deferral percentage limitation for highly compensated employees, and the notices the employer gives by March 15 about excess SEP contributions and disallowed deferrals.
A minimum contribution of the smaller of 3% of compensation or the key employee rate, a box B to meet it through another SEP, the effective date and the employer's signature.
The Model Salary Reduction SEP Deferral Form, which the employee signs, and the Notification of Excess SEP Contributions, which the employer signs.
A 25-row table of employee name, HCE or other status, compensation, deferrals and ratios, with lines A to C to figure the permitted ratio.
Enter the name of the employer on the opening line, which states that the employer amends its salary reduction SEP by adopting the model.
Enter the minimum age and years of service, and check includes or does not include for each of the three employee groups. The instructions say less restrictive requirements are allowed, but not more restrictive ones.
Check box B only if the top-heavy requirements will be met through contributions to nonkey employees' SEP-IRAs under the employer's other SEP. Otherwise paragraph A applies.
The employer signs and enters the date, name and title. Article VII says the SEP is effective upon adoption and establishment of IRAs for all eligible employees.
The instructions say the agreement is adopted when all blanks are completed and each eligible employee has a copy of the form and the statements the instructions list.
Use the page 8 worksheet to compare highly compensated employees' deferrals with the permitted ratio, then use the page 5 model notice for any excess SEP contributions.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Nowhere. The form says "Do not file Form 5305A-SEP with the IRS. Instead, keep it with your records."
The instructions say employers that set up a salary reduction SEP with this form and give each participant the listed documents and disclosures are not required to file Forms 5500 or 5500-EZ for the SEP, with an ERISA Title I exception.
The form sets March 15 for notices of excess SEP contributions and disallowed deferrals. The instructions set the later of January 31 following the year or 30 days after a contribution for contribution notices.
The asterisk note says amounts such as $450 and $220,000 are the amounts for 2006 and may be increased for cost-of-living adjustments in later years.
The instructions say employers liable for the 10% tax on excess contributions use Form 5330 to pay the excise tax.
The instructions say an employer that used the March 2002 version of Form 5305-A SEP is not required to use this version.
5305-SEP
7 fields, 2 pages
5305
10 fields, 2 pages
5305-A
10 fields, 2 pages
5330
304 fields, 6 pages
5500-EZ
78 fields, 2 pages
W-2
568 fields, 11 pages
The employer completes and signs the agreement. Employees use the model deferral form on page 5 to make their elections.
No tool matches that search.
The form says an employer may not establish a salary reduction SEP after 1996. The instructions say one established before 1997 may continue to be maintained.
No. The form says not to file it with the IRS and to keep it with the employer's records.
The instructions say Form 5305A-SEP is for SEPs that permit employee elective deferrals. An employer that wants nonelective employer contributions uses Form 5305-SEP or a nonmodel SEP.
The form says the smaller of 25% of compensation or the section 402(g) limit for the tax year, based only on the first $220,000* of compensation. The asterisk marks it as the 2006 amount.
The instructions say they are deferrals by a highly compensated employee above the deferral percentage limitation: the average deferral percentage of eligible nonhighly compensated employees multiplied by 1.25.
The instructions list employers with leased employees, another qualified retirement plan, more than 25 eligible employees in the prior year, and state or local governments or tax-exempt organizations.