Header
Names and identifying numbers of the person filing Form 5471 and the U.S. shareholder, and the foreign corporation's name, EIN if any and reference ID number.
5471 Sch. H-1
Pro Rata Share of CFC Adjusted Net Income or Loss for Corporate Alternative Minimum Tax
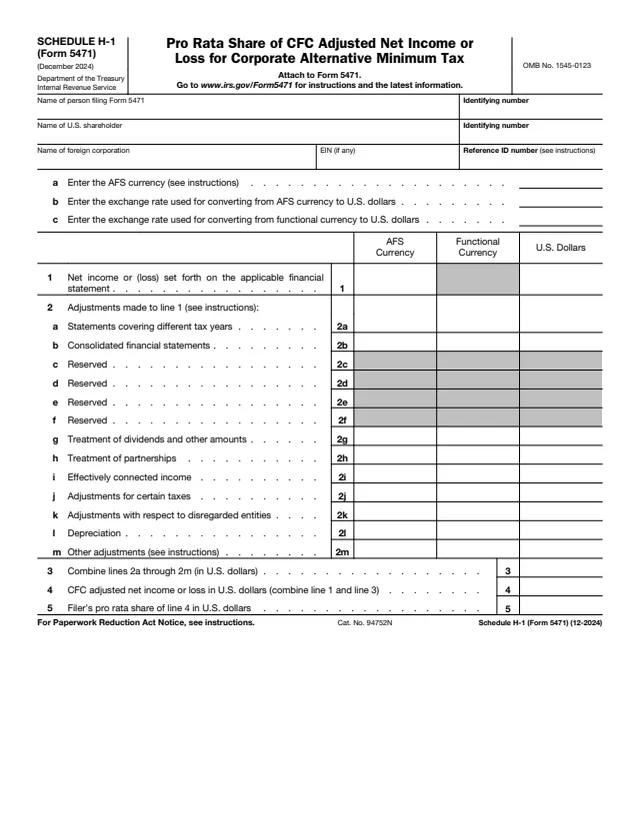
Schedule H-1 (Form 5471), Pro Rata Share of CFC Adjusted Net Income or Loss for Corporate Alternative Minimum Tax, is a separate schedule filed with Form 5471. The instructions say it is used to report the controlled foreign corporation's (CFC's) adjusted net income or loss for corporate alternative minimum tax (CAMT) purposes.
The schedule starts from the net income or loss on the applicable financial statement (AFS), adds the adjustments on lines 2a through 2m, and ends with the filer's pro rata share in U.S. dollars on line 5. It has three amount columns: AFS currency, functional currency and U.S. dollars.
The About Form 5471 page says applicable corporations filing Form 5471 use this schedule, and the instructions point to the Instructions for Form 4626 for CAMT. This page covers the December 2024 edition. You can fill out the PDF free in your browser on this page and download it without an account.
Names and identifying numbers of the person filing Form 5471 and the U.S. shareholder, and the foreign corporation's name, EIN if any and reference ID number.
The AFS currency, the exchange rate from AFS currency to U.S. dollars, and the exchange rate from functional currency to U.S. dollars.
Net income or loss set forth on the applicable financial statement, in the AFS currency, functional currency and U.S. dollar columns.
Statements covering different tax years, consolidated financial statements, dividends, partnerships, effectively connected income, certain taxes, disregarded entities, depreciation and other adjustments. Lines 2c to 2f are marked Reserved.
Line 3 combines lines 2a through 2m in U.S. dollars, line 4 is the CFC adjusted net income or loss in U.S. dollars, and line 5 is the filer's pro rata share of line 4.
Enter the names and identifying numbers of the filer, the U.S. shareholder and the foreign corporation, with the corporation's EIN if any and its reference ID number.
The instructions say the AFS currency is the currency the applicable financial statements are denominated in, which is not necessarily the functional currency. The rate on item b is the weighted average exchange rate, reported using the divide-by convention.
Enter the AFS net income or loss in AFS currency and, if it is not already in U.S. dollars, convert it using the weighted average exchange rate, as the instructions describe.
Report each adjustment in the column for the currency it is denominated in, plus its U.S. dollar amount. The instructions' example: a 100x adjustment in AFS currency at a rate of 1 to 1.1 is reported as 100x in the AFS Currency column and 110x in the U.S. Dollars column.
Line 2g covers dividends from stock of a foreign corporation, line 2h partnership investment AFSI, line 2l the difference between section 167 depreciation and AFS depreciation expense, and line 2m any other adjustments.
Combine lines 2a through 2m on line 3, combine line 1 and line 3 on line 4, then enter the filer's pro rata share on line 5. The instructions say it is determined under rules similar to the rules under section 951(a)(2).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 5471. The instructions say Form 5471 is attached to the filer's income tax return and both are filed by the due date, including extensions, for that return.
The instructions say to send each Category 4, 5a or 5b filer required to file Schedule H-1 a copy of their separate schedule.
The instructions say exchange rates are reported with a divide-by convention, as units of foreign currency that equal one U.S. dollar, rounded to at least four places.
The instructions point to the Instructions for Form 4626 for CAMT and for determining applicable financial statements. The line instructions cite Proposed Regulations sections such as 1.56A-1(e) and 1.59A-6.
The PDF prints its edition as December 2024 and its footer as 12-2024. The form says to go to www.irs.gov/Form5471 for instructions and the latest information.

5471
437 fields, 6 pages
4626
813 fields, 8 pages
5471 Sch. H
41 fields, 1 page
5471 Sch. I-1
35 fields, 1 page
5471 Sch. J
282 fields, 3 pages
5471 Sch. G-1
29 fields, 1 page
The person filing Form 5471 completes it and attaches it to that form. The instructions say a separate Schedule H-1 is attached for each person described in Categories 4, 5a and 5b that is an applicable corporation within the meaning of section 59(k).
No tool matches that search.
The person filing Form 5471 attaches it. The instructions say a separate Schedule H-1 is attached for each Category 4, 5a or 5b person that is an applicable corporation within the meaning of section 59(k).
AFS currency, functional currency and U.S. dollars. The instructions say amounts on lines 1 through 2m are entered in the currency in which the item originates.
The instructions say the rate from AFS currency to U.S. dollars is the weighted average exchange rate, reported using the divide-by convention.
The filer's pro rata share of line 4 in U.S. dollars. The instructions say it is determined under rules similar to the rules under section 951(a)(2).
The form labels lines 2c, 2d, 2e and 2f as Reserved.
They are a section of the Instructions for Form 5471. The form points to www.irs.gov/Form5471.