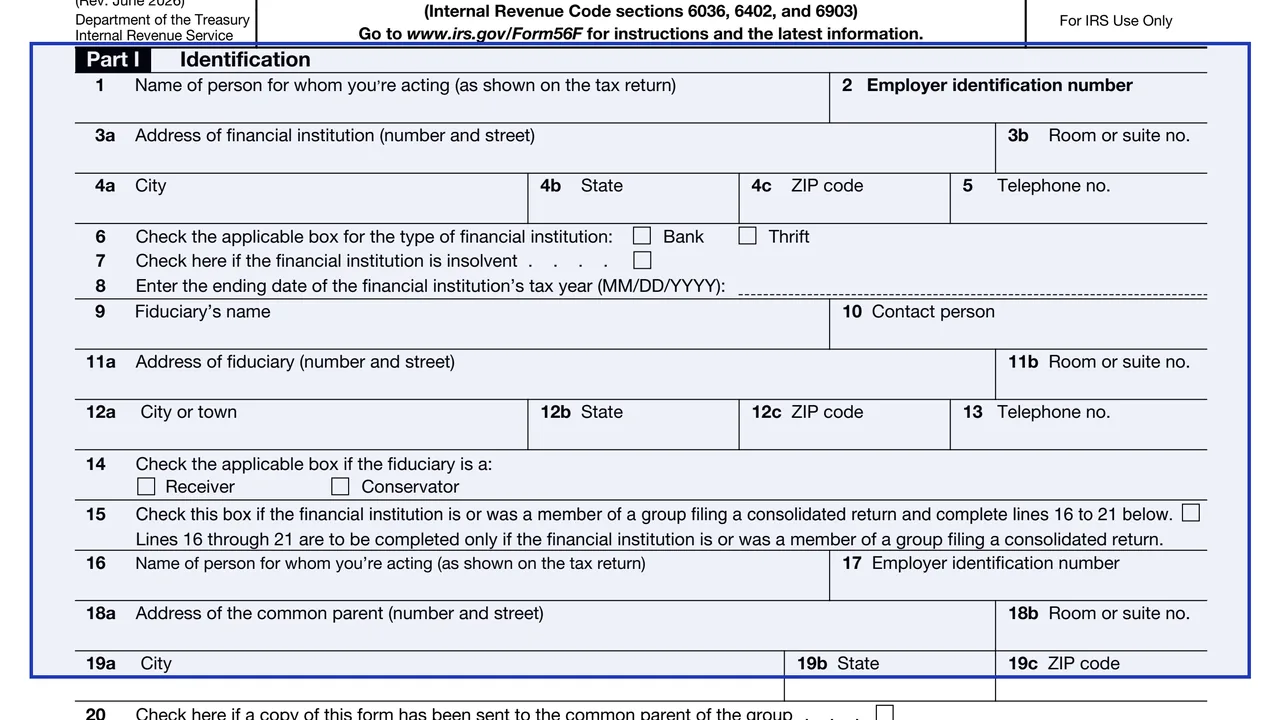
Part I, lines 1 to 8: the institution
The institution's name and EIN, address, phone, whether it is a bank or thrift, whether it is insolvent, and the ending date of its tax year.
56-F
Notice Concerning Fiduciary Relationship of Financial Institution
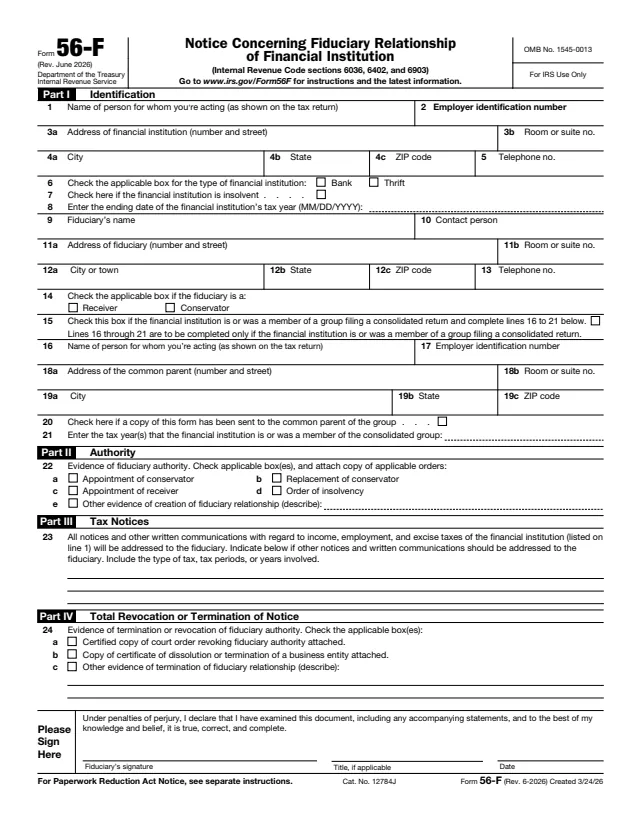
Form 56-F notifies the IRS of a fiduciary relationship only when that relationship is with respect to a financial institution, such as a bank or a thrift. The form cites Internal Revenue Code sections 6036, 6402 and 6903.
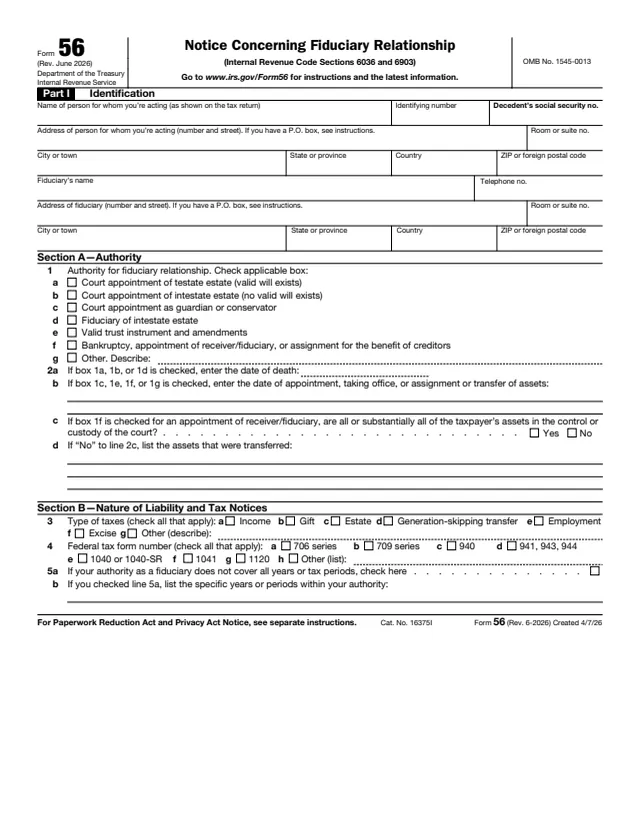
It is not a form for individuals or for ordinary executors and trustees. The instructions say it is filed, instead of Form 56, by the federal agency acting as fiduciary, which they define as the Federal Deposit Insurance Corporation or another federal agency authorized by law to act as a receiver or conservator of a financial institution. The instructions also say the filing of Form 56-F is a requirement to secure a refund under section 6402(k).
The form identifies the institution, the fiduciary, any consolidated group, the evidence of authority, the tax notices to be sent to the fiduciary and any revocation. You can fill out the Form 56-F PDF free in your browser on this page and download the result without an account.
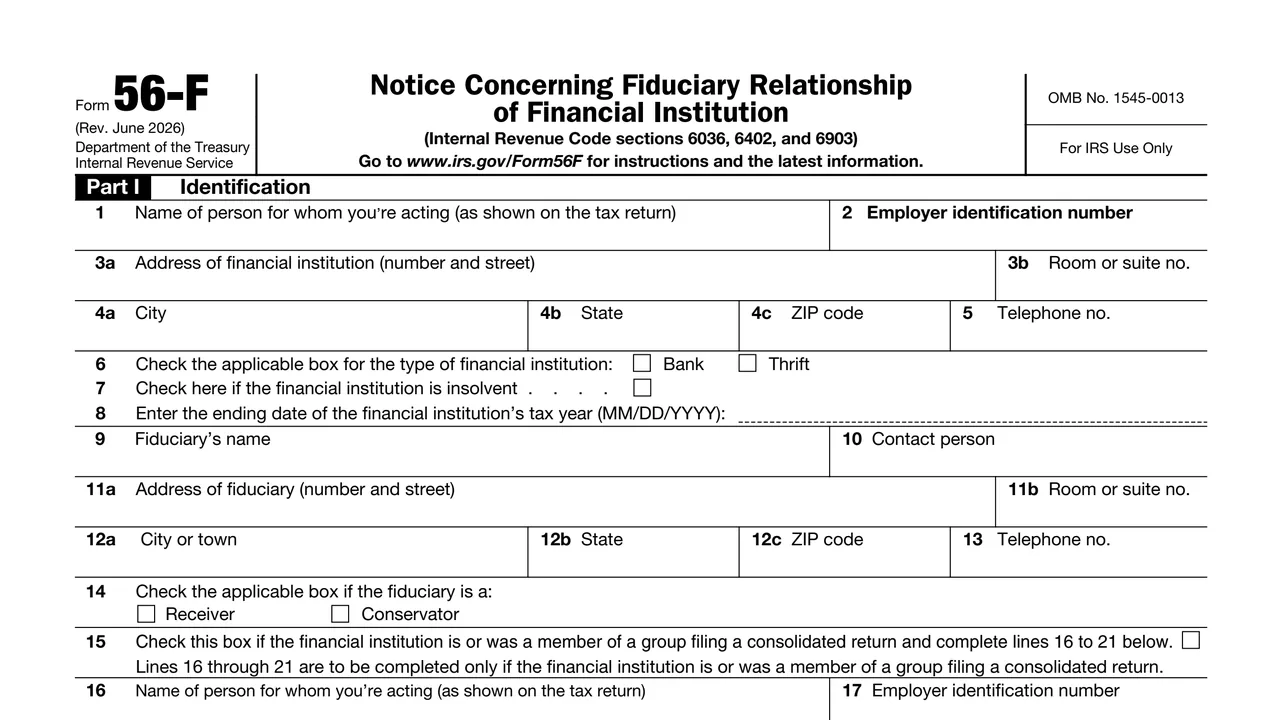
The institution's name and EIN, address, phone, whether it is a bank or thrift, whether it is insolvent, and the ending date of its tax year.
The fiduciary's name, contact person, address and phone, and whether the fiduciary is a receiver or a conservator.
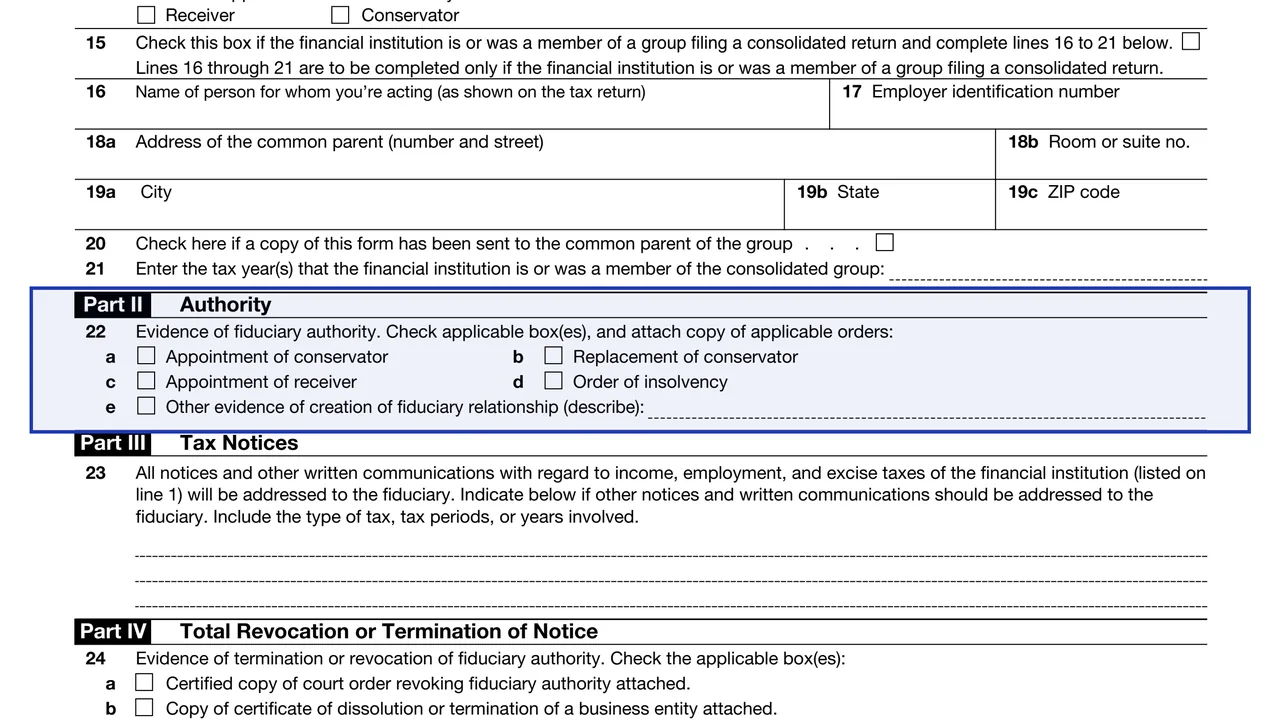
Completed only if the institution is or was a member of a group filing a consolidated return: the common parent's name, EIN and address, a box for a copy sent to the parent, and the tax years.
Line 22 boxes for appointment of conservator, replacement of conservator, appointment of receiver, order of insolvency or other evidence, with copies of the orders attached.
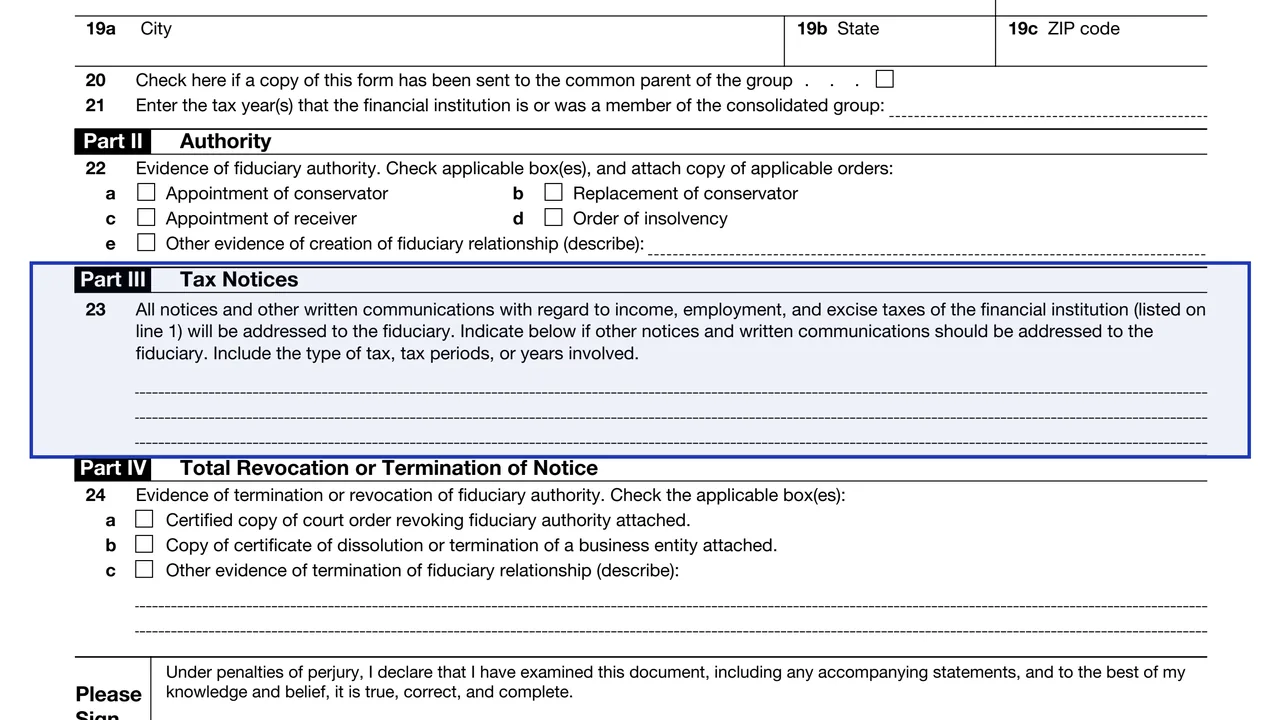
Line 23 lists other notices and written communications to be addressed to the fiduciary, with the type of tax and the periods or years involved.
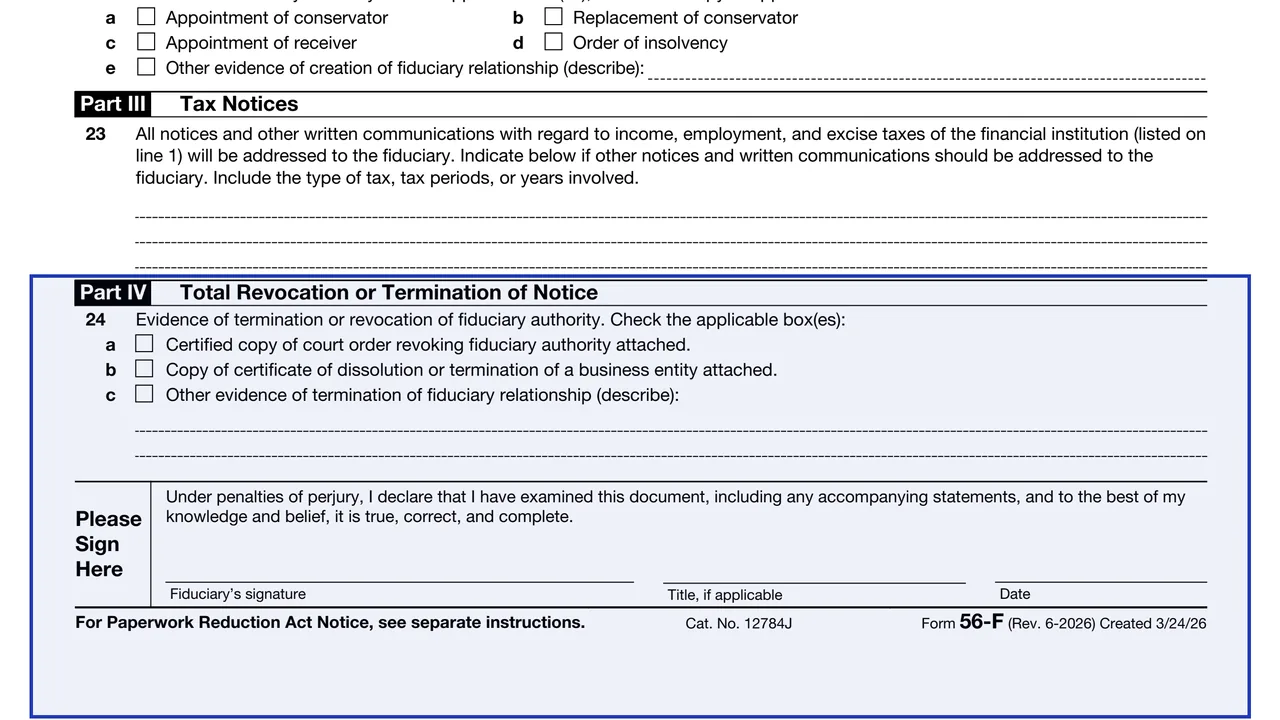
Line 24 boxes for evidence of a total revocation or termination, then the fiduciary's signature under penalties of perjury, title and date.
Enter the institution's name as shown on its return, its EIN on line 2, its address and phone, and check bank or thrift. Check line 7 only if the institution is insolvent within the meaning of the statutes the instructions list.
Enter the fiduciary's full name, such as the Federal Deposit Insurance Corporation. The instructions say the line 10 contact person is the individual in the agency with authority to handle all tax matters for the institution.
Fill these in only for a member of a consolidated group. The instructions say a separate Form 56-F is filed for each parent if the institution was in more than one group during a refund year.
Check the boxes that match the evidence of authority and attach a copy of each applicable order.
Use line 23 for other notices to be sent to the fiduciary, for example a transferee liability under section 6901. Complete Part IV only when revoking or terminating all prior notices.
Sign under penalty of perjury and enter the title for the fiduciary role, receiver or conservator.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Form 56-F is filed with the IRS within 10 days from the date the fiduciary is appointed to act as a receiver or conservator.
For section 6402(k), the instructions say it should be filed in every subsequent tax year that the fiduciary continues to act as receiver or conservator for that institution.
Send it to the Internal Revenue Service Center where the financial institution files its income tax return.
Send it to Internal Revenue Service, Insolvency, Attn: FDIC, MS 5027, Dallas, TX 75242, as listed in the instructions.
If a Form 56-F was filed for a solvent institution that later becomes insolvent, the instructions say the fiduciary should file a new Form 56-F and check line 7.
The instructions say the federal agency acting as fiduciary files Form 56-F to notify the IRS of the creation, termination or change in status of a fiduciary relationship with a financial institution. The IRS receives it.
No tool matches that search.
The About page says Form 56-F is used only when the fiduciary relationship is with respect to a financial institution, such as a bank or a thrift. Other fiduciary relationships use Form 56.
The instructions define it as the Federal Deposit Insurance Corporation or another federal agency authorized by law to act as a receiver or conservator of a financial institution.
Within 10 days from the date the fiduciary is appointed as receiver or conservator, and in each later tax year the fiduciary keeps acting, according to the instructions.
The instructions say filing Form 56-F is a requirement to secure a refund under section 6402(k) and Regulations section 301.6402-7.
A copy of each applicable order checked in Part II, such as an appointment of receiver or an order of insolvency.