Line 1: method
One box: 1a for the international boycott factor from Schedule A, or 1b for specifically attributable taxes and income from Schedule B.
5713
Tax Effect of the International Boycott Provisions
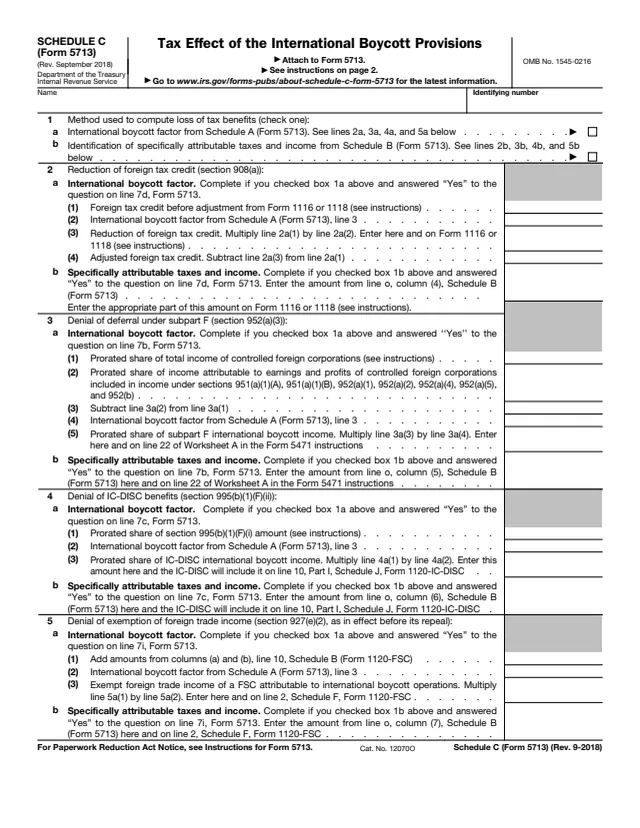
Schedule C (Form 5713) is used to compute the loss of tax benefits attributable to participation in or cooperation with an international boycott. It takes the result of either the international boycott factor from Schedule A (Form 5713) or the specifically attributable taxes and income from Schedule B (Form 5713) and applies it to each tax benefit.
The lines cover the reduction of the foreign tax credit under section 908(a), the denial of deferral under subpart F, the denial of IC-DISC benefits, the denial of the exemption of foreign trade income of an FSC, and the reduction of foreign trade income qualifying for the extraterritorial income exclusion. Each result is then entered on another form, such as Form 1116, Form 1118, Form 1120-IC-DISC, Form 1120-FSC, Form 8873 or Worksheet A in the Form 5471 instructions.
The schedule is attached to Form 5713. You can fill out the Schedule C PDF free in your browser on this page and download the result without an account.
One box: 1a for the international boycott factor from Schedule A, or 1b for specifically attributable taxes and income from Schedule B.
The reduction of the foreign tax credit under section 908(a), figured on line 2a with the boycott factor or taken from Schedule B on line 2b.
The denial of deferral under section 952(a)(3), with the prorated share of subpart F international boycott income of controlled foreign corporations.
The denial of IC-DISC benefits under section 995(b)(1)(F)(ii) and the denial of the exemption of FSC foreign trade income under section 927(e)(2), as in effect before its repeal.
On page 2, the reduction of foreign trade income qualifying for the extraterritorial income exclusion, using line 49 of Form 8873 and the boycott factor.
Check 1a or 1b. The schedule says a person who applies the boycott factor to one operation applies it to all that tax year's operations, and a person who identifies specifically attributable taxes and income uses that method for all of them.
Complete 2a or 2b if you answered Yes on Form 5713, line 7d. Line 2a(1) takes the foreign tax credit before adjustment from Form 1116, line 30, Part IV, or Form 1118, Schedule B, Part III, line 7.
Complete it if you answered Yes on Form 5713, line 7b. The result on line 3a(5) or 3b is also entered on line 22 of Worksheet A in the Form 5471 instructions.
Complete line 4 for a Yes on Form 5713, line 7c, and line 5 for a Yes on line 7i. Line 4 goes to Form 1120-IC-DISC, Schedule J, Part I, line 10, and line 5 to Form 1120-FSC, Schedule F, line 2.
Complete it if you answered Yes on Form 5713, line 7j. Enter the amount from line 49 of Form 8873, multiply by the boycott factor, and enter the result on Form 8873, line 50.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 5713. The Instructions for Form 5713 say to attach the original Form 5713 and Schedules A, B and C, if applicable, to your income tax return.
The instructions say Form 5713 is due when your income tax return is due, including extensions.
Each reduction is also entered on the form the line names: Form 1116 or 1118, Worksheet A in the Form 5471 instructions, Form 1120-IC-DISC, Form 1120-FSC or Form 8873.
The instructions say willful failure to file Form 5713 may result in a $25,000 fine, imprisonment for no more than 1 year, or both.
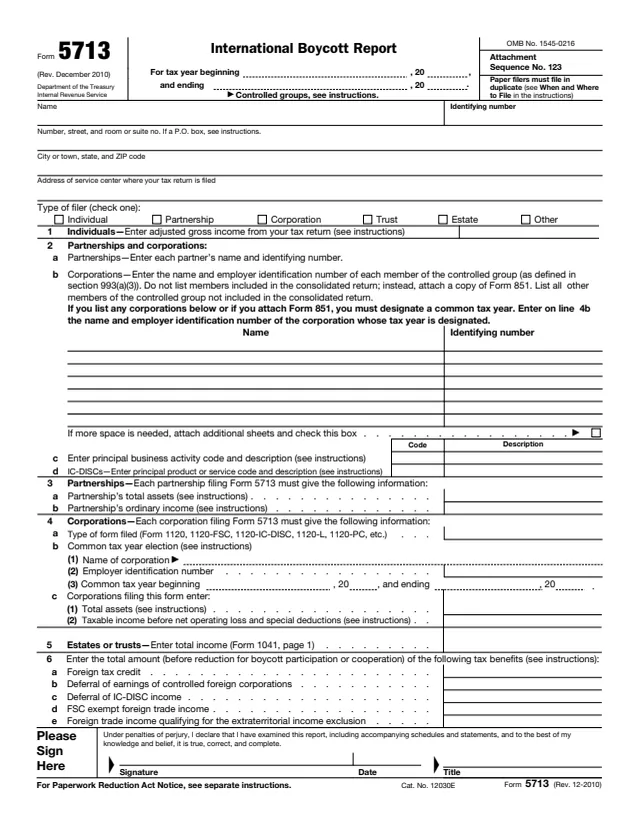
5713
383 fields, 4 pages
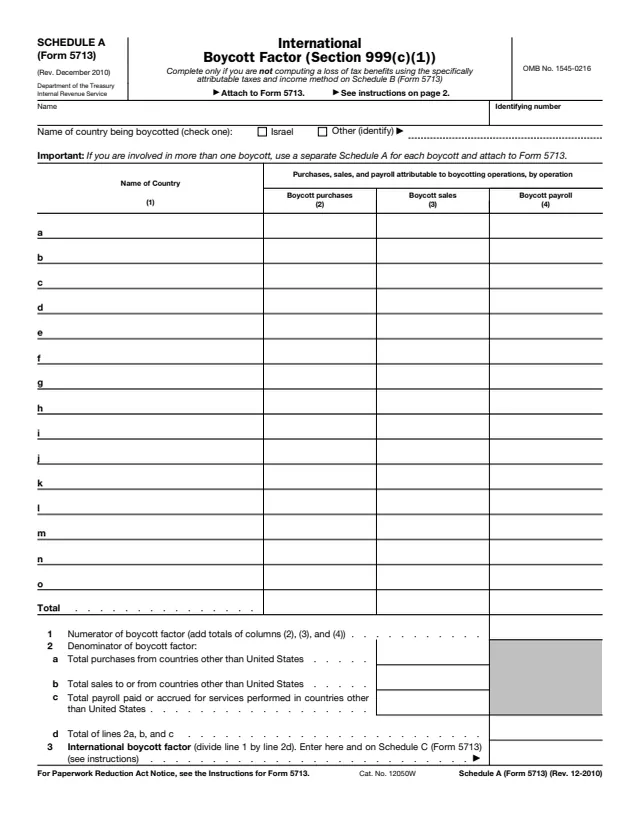
5713
74 fields, 2 pages
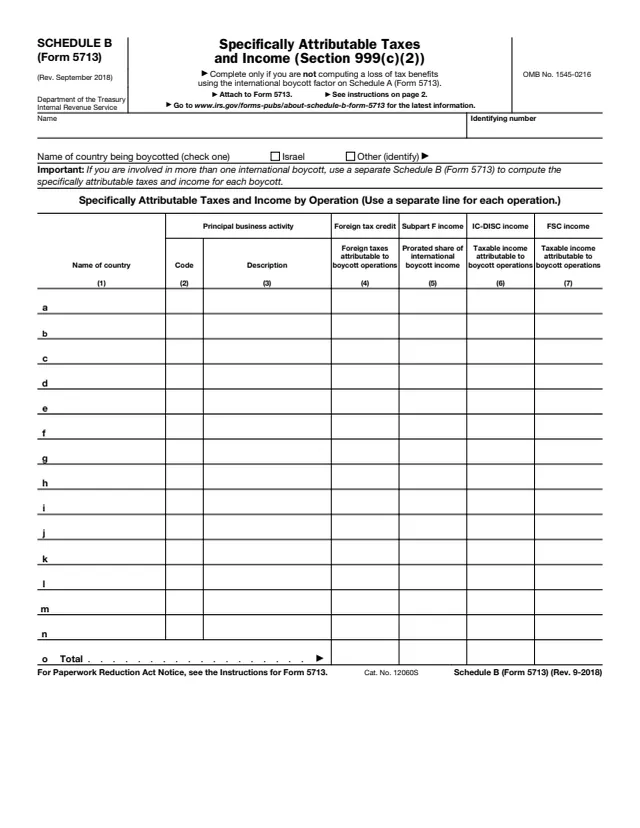
5713
107 fields, 2 pages
1116
118 fields, 2 pages
1118
1,263 fields, 12 pages
8873
152 fields, 2 pages
The instructions on page 2 of the schedule say to complete Schedule C if you completed either Schedule A or Schedule B of Form 5713. It is attached to Form 5713, which U.S. persons file with their income tax return.
No tool matches that search.
The schedule says anyone who completed Schedule A or Schedule B of Form 5713. Each partner completes a separate Schedule C, and partnerships do not complete it.
The schedule says a person who applies the boycott factor to one operation applies it to all that tax year's operations, and the same holds for specific attribution.
On Form 1116 or Form 1118. For line 2a(3), the schedule names Form 1116, line 32, Part IV, or Form 1118, Schedule B, Part III, line 8.
The international boycott factor from Schedule A. Line 6 of Schedule C multiplies the Form 8873, line 49 amount by that factor.
It is attached to Form 5713, which the instructions say is due when your income tax return is due, including extensions.