Name, number and boycotted country
The filer's name and identifying number, and one box for the country being boycotted: Israel, or Other with the country identified.
5713
Specifically Attributable Taxes and Income (Section 999(c)(2))
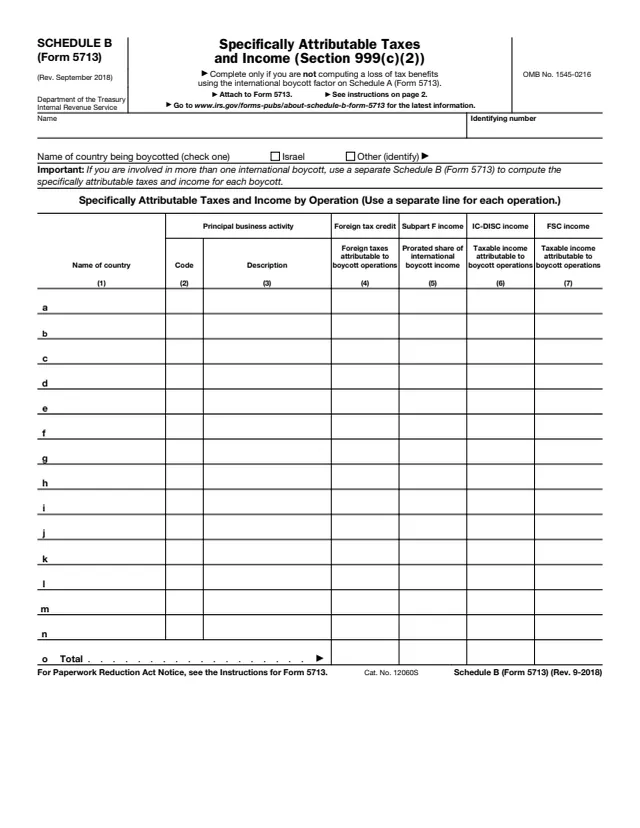
Schedule B (Form 5713) is one of the two ways to figure the tax benefits lost because of participation in or cooperation with an international boycott. Instead of applying the international boycott factor from Schedule A (Form 5713), it lists the taxes and income specifically attributable to each boycott operation under section 999(c)(2).
The schedule says to complete it only if you are not computing a loss of tax benefits using the international boycott factor on Schedule A, and to attach it to Form 5713. Its column totals carry to Schedule C (Form 5713), which figures the actual tax effect. The instructions on page 2 of the schedule say not to use Schedule B to figure the reduction to foreign trade income qualifying for the extraterritorial income exclusion; Schedule A is used for that.
A separate Schedule B is used for each international boycott. You can fill out the Schedule B PDF free in your browser on this page and download the result without an account.
The filer's name and identifying number, and one box for the country being boycotted: Israel, or Other with the country identified.
The name of the country, the principal business activity code and a short description of the activity, on one line per operation, lines a through n.
Foreign taxes attributable to boycott operations. The instructions say these taxes are not eligible for the foreign tax credit.
Your prorated share of international boycott income of a controlled foreign corporation, which the instructions say is not eligible for tax deferral.
Taxable income of an IC-DISC and of an FSC attributable to boycott operations, followed by the totals on line o.
Enter the name and identifying number and check the box for the country being boycotted. File it for the period covered by your income tax return, reporting only your own taxes and income, not those of other members of a controlled group.
Enter the country that requires participation in or cooperation with the boycott, which the instructions say is not necessarily where you have operations. Use the activity code list in the Instructions for Form 5713. IC-DISCs enter the major product code in parentheses.
Enter foreign taxes paid, accrued or deemed paid that are attributable to the boycott operation, leaving out taxes disallowed under sections 901 through 907, 911 and 6038. The total goes to Schedule C (Form 5713), line 2b.
Enter your prorated share of the controlled foreign corporation's income attributable to the boycott operation, with a reasonable amount for allocable deductions. The total goes to Schedule C, line 3b.
For an IC-DISC, follow the four steps on page 2, which use Form 1120-IC-DISC, Schedule J and a 16/17 multiplier for C corporations. For an FSC, enter income that would have been exempt. Totals go to Schedule C, lines 4b and 5b.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 5713. The Instructions for Form 5713 say to attach the original Form 5713 and Schedules A, B and C, if applicable, to your income tax return.
The instructions say Form 5713 is due when your income tax return is due, including extensions.
If the original Form 5713 is filed electronically as an attachment to an e-filed income tax return, the instructions say no duplicate Form 5713 is required.
The schedule says one act of participation or cooperation creates a presumption for all operations in each country that helps carry out the boycott, which can be rebutted by showing an operation is separate from the boycott.
The instructions say willful failure to file Form 5713 may result in a $25,000 fine, imprisonment for no more than 1 year, or both.
5713
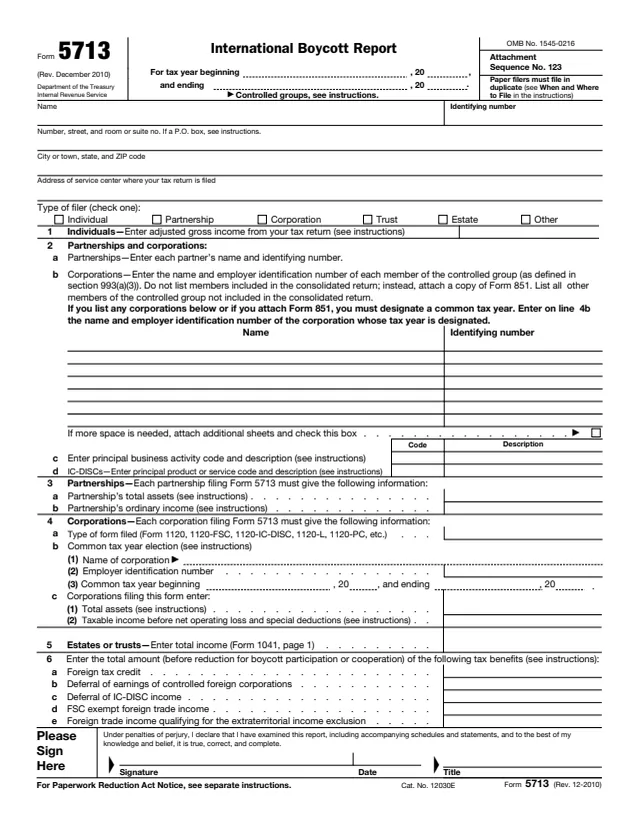
383 fields, 4 pages
5713
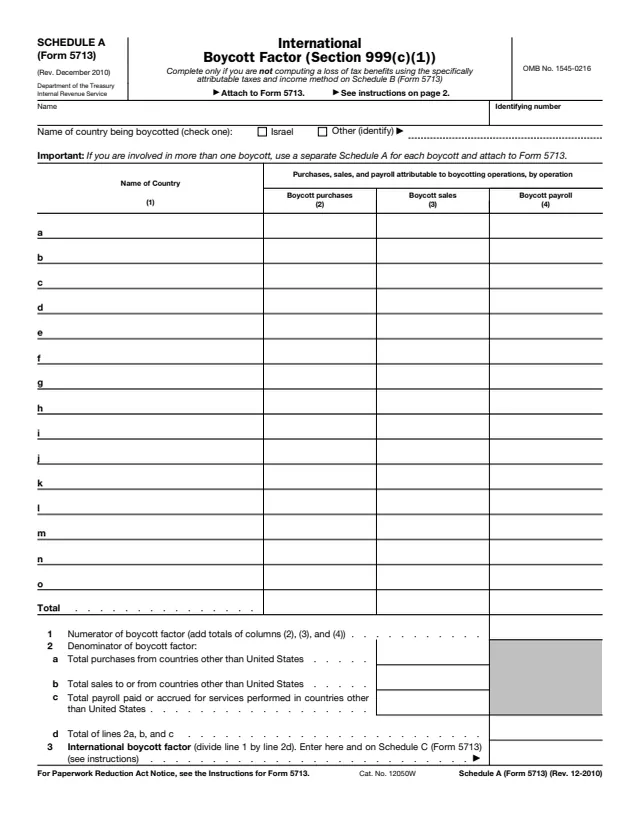
74 fields, 2 pages
5713
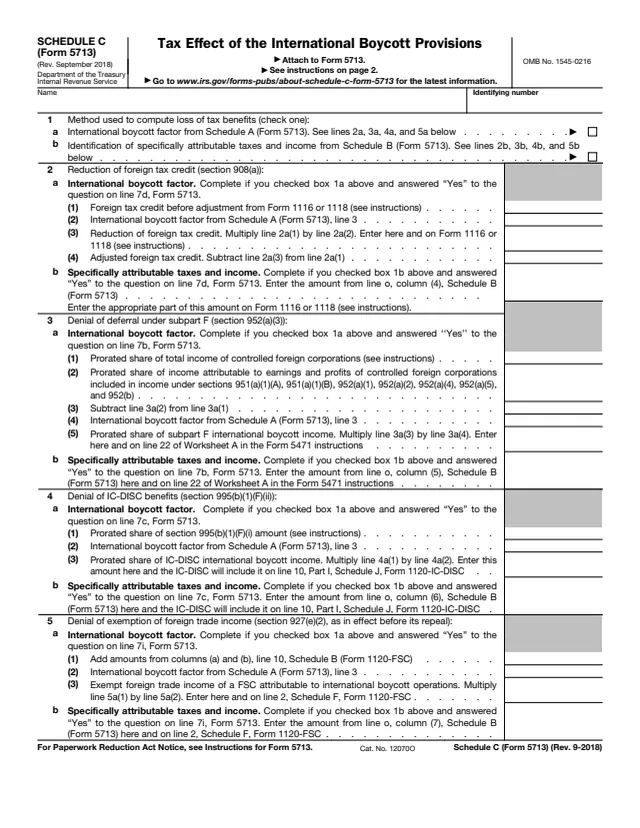
26 fields, 2 pages
1118
1,263 fields, 12 pages
1116
118 fields, 2 pages
1120-IC-DISC
483 fields, 7 pages
The About page says Schedule B is completed if you participated in or cooperated with an international boycott and you figure the loss of tax benefits by specifically attributing taxes and income. It is attached to Form 5713, which U.S. persons file with their income tax return.
No tool matches that search.
Schedule A applies the international boycott factor. Schedule B identifies taxes and income specifically attributable to boycott operations. The Form 5713 instructions say either can be used for most tax benefits.
The schedule says to enter the totals of columns (4), (5), (6) and (7) on Schedule C (Form 5713), lines 2b, 3b, 4b and 5b.
The schedule says to use a separate Schedule B (Form 5713) for each boycott.
The country that requires participation in or cooperation with the boycott as a condition of doing business there. The instructions say it is not necessarily the country where you have operations.
No. The schedule says that reduction is figured with the international boycott factor on Schedule A (Form 5713).