Part I, line 1
The skip person distributee's name, TIN and address, with foreign country, province and postal code lines.
706-GS
Notification of Distribution From a Generation-Skipping Trust
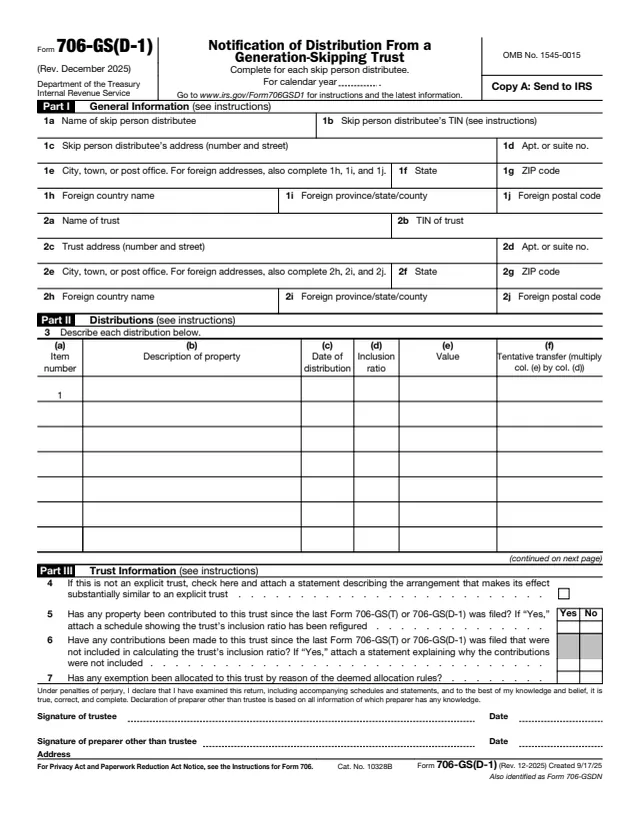
Form 706-GS(D-1), Notification of Distribution From a Generation-Skipping Trust, is filed by a trustee, not by the person who receives the distribution. The IRS says a trustee uses it to report certain distributions from a trust that are subject to the generation-skipping transfer (GST) tax and to provide the skip person distributee with the information needed to figure the tax due on the distribution.
The trustee completes one form for each skip person distributee. Copy A goes to the IRS and Copy B goes to the distributee, who uses it to complete Form 706-GS(D), Generation-Skipping Transfer Tax Return for Distributions.
This page covers the December 2025 revision. Its instructions say the Part I entry lines were reorganized and lines 1b and 2b now ask for a TIN. You can fill out Form 706-GS(D-1) free in your browser on this page and download the result without an account.
The skip person distributee's name, TIN and address, with foreign country, province and postal code lines.
The trust's name, TIN and address, with the same foreign address lines.
Line 3 describes each distribution in six columns: item number, description of property, date of distribution, inclusion ratio, value and tentative transfer. Pages 2 and 4 continue the table.
Line 4 flags a trust that is not an explicit trust. Lines 5 to 7 ask about contributions since the last Form 706-GS(T) or 706-GS(D-1) and deemed allocations of exemption.
Signature of the trustee with the date, and a separate signature line and address for a preparer other than the trustee.
Copy B repeats Parts I and II for the distributee, and page 5 holds the Instructions for Skip Person Distributee.
Enter the Social Security number of an individual distributee, or "unknown" or "none" if it is unknown or there is none. For a trust distributee, enter the trust's TIN.
Enter the TIN of the trust that made the distribution. The instructions say to write "Applied for" if the TIN has not been received by the filing time.
Number each distribution in order, and list items with different inclusion ratios separately. Describe the property in detail, such as CUSIP numbers for stocks and bonds. The date of distribution is when title passed to the distributee.
Enter the inclusion ratio, which the instructions define as the excess of 1 over the trust's applicable fraction. The applicable fraction is rounded to at least the nearest one-thousandth.
Enter the value of the property at the time of distribution, then multiply column (e) by column (d) for the tentative transfer in column (f).
Check line 4 for a nonexplicit trust and attach a statement. Answer lines 5 to 7 and attach what a Yes answer asks for. The trustee signs and dates.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Copy A goes to the IRS and Copy B to the distributee by April 15 of the year following the calendar year when the distribution was made, or the next business day.
Department of the Treasury, Internal Revenue Service Center, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915. The instructions give the same street address for private delivery services.
To change a filed return, the instructions say to file another Form 706-GS(D-1) with "Supplemental Information" across the top of page 1, a statement of what changed and a copy of the original.
The distributee instructions say not to change any items on Copy B. The distributee asks the trustee for a corrected form and a copy sent to the IRS.
Copy B says the skip person distributee reports the distribution on Form 706-GS(D), filed with Internal Revenue Service, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915.
GST exemption is allocated on Form 709 or Form 706, so the instructions say to obtain allocation details for the trust from the settlor or the settlor's executor.
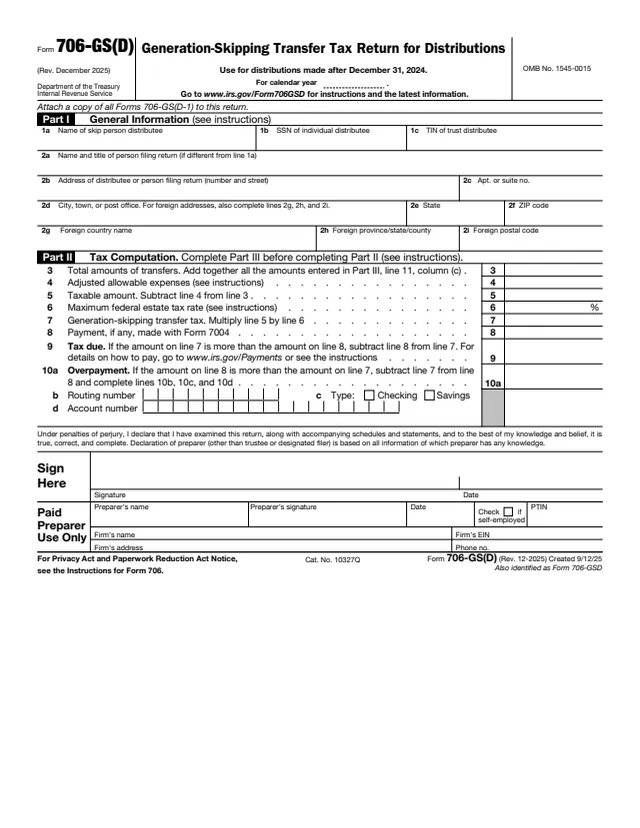
706-GS
191 fields, 2 pages
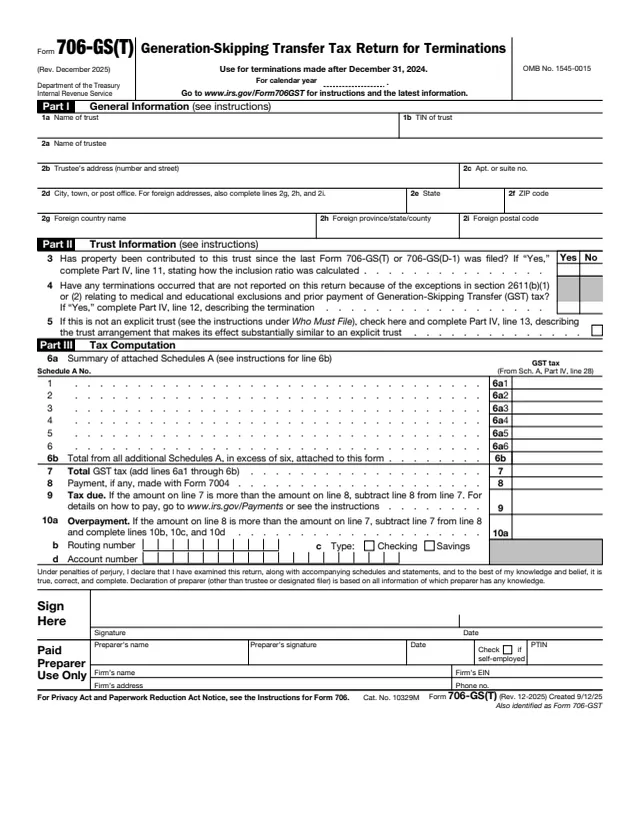
706-GS
287 fields, 6 pages

706
316 fields, 5 pages
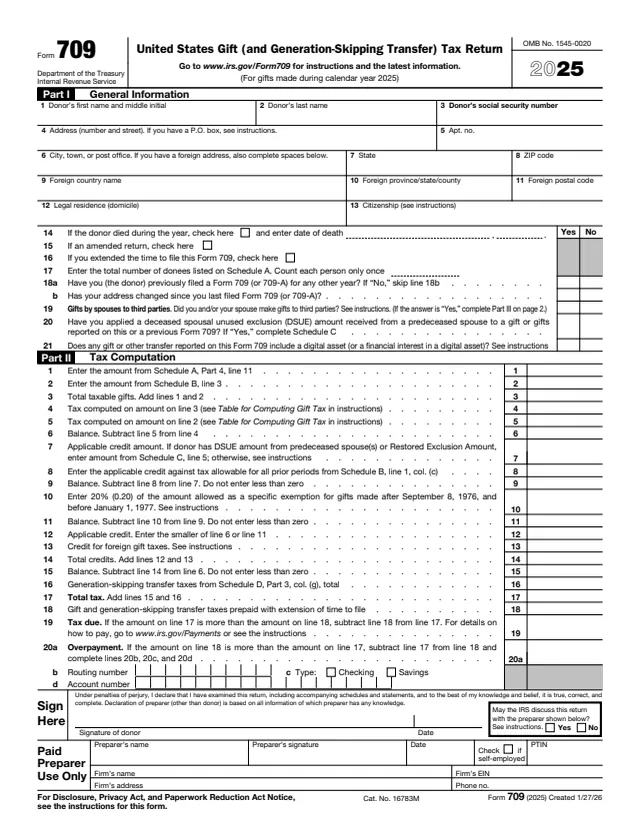
709
1,851 fields, 10 pages
SS-4
89 fields, 2 pages
The instructions say the trustee of any trust that makes a taxable distribution files a Form 706-GS(D-1) for each skip person, even if the inclusion ratio for the distribution is zero.
No tool matches that search.
The trustee. The instructions say the trustee of any trust that makes a taxable distribution files one for each skip person, sending Copy A to the IRS and Copy B to the distributee.
The distributee uses it to complete Form 706-GS(D) and, the instructions say, attaches a copy of each Form 706-GS(D-1) received during the year and keeps a copy.
Yes. The instructions say the trustee files a return for each skip person even if the inclusion ratio applicable to the distribution is zero.
The instructions define it as a natural person assigned to a generation two or more generations below the settlor's, or a trust that meets certain conditions, such as all interests being held by skip persons.
The instructions say the Part I entry lines were reorganized, and lines 1b and 2b were modified to include TIN as the identification number.
The date of distribution in column (c), which the form describes as the date title to the property passed from the trustee to the distributee.