Page 1 header
The shareholder's name, identifying number, address and type, a shareholder contact and phone number, and the PFIC's name, EIN and address.
8621-A
Return by a Shareholder Making Certain Late Elections To End Treatment as a Passive Foreign Investment Company
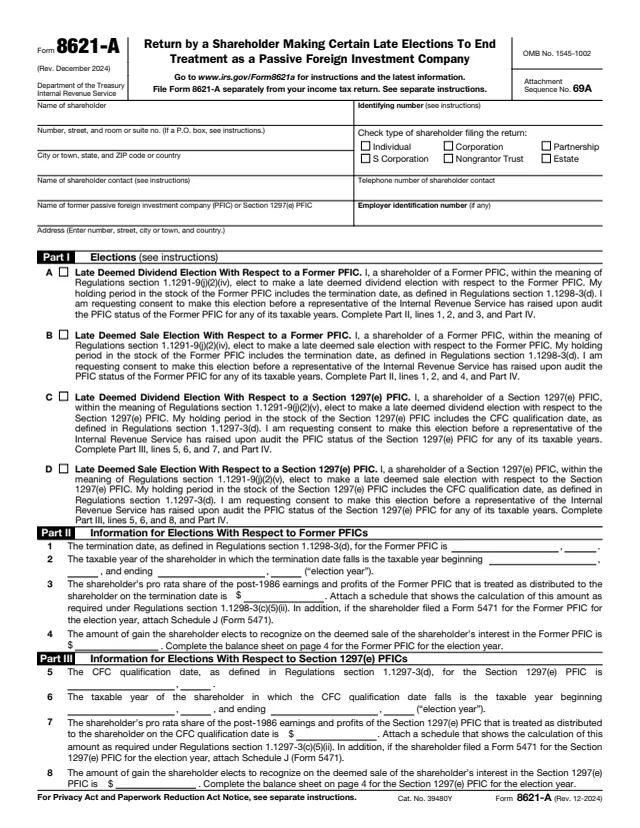
Form 8621-A is the return by a shareholder making certain late elections to end treatment as a passive foreign investment company (PFIC). The About page says a U.S. person that is a direct or indirect shareholder of a former PFIC or a Section 1297(e) PFIC is treated as holding stock in a PFIC, and stays subject to tax under section 1291, unless the shareholder makes a purging election under section 1298(b)(1).
The instructions say a timely purging election is made on Form 8621, and Form 8621-A is used only for a late one: one made more than 3 years after the due date, as extended, of the return for the year that includes the termination date or the CFC qualification date.
The form offers four elections, a late deemed dividend or late deemed sale for each kind of PFIC, figures the tax and interest due, and includes a closing agreement and a balance sheet. It is filed separately from the income tax return. You can fill it out free in your browser on this page and download the result without an account.
The shareholder's name, identifying number, address and type, a shareholder contact and phone number, and the PFIC's name, EIN and address.
Election A, late deemed dividend, and B, late deemed sale, for a former PFIC. Election C, late deemed dividend, and D, late deemed sale, for a Section 1297(e) PFIC.
Lines 1 to 4 give the termination date, election year and the deemed dividend or gain for a former PFIC. Lines 5 to 8 give the same with the CFC qualification date.
Lines 9a to 21 allocate the excess distribution over the holding period, figure the increases in tax, foreign tax credit and interest, and show the balance due on line 21, followed by signatures.
A closing agreement under section 7121 between the shareholder and the Commissioner, signed by both, used when the election year is a closed tax year.
Assets, liabilities and shareholders' equity of the PFIC for the election year, at the beginning and end of the period, completed for Election B or D.
Enter the shareholder and PFIC details. For the contact, the instructions say to enter "Same" if it is the taxpayer, or another person's details with Form 2848 attached.
Check the one election being made. A separate Form 8621-A is filed for each PFIC, and forms for PFICs in one chain of ownership are filed together.
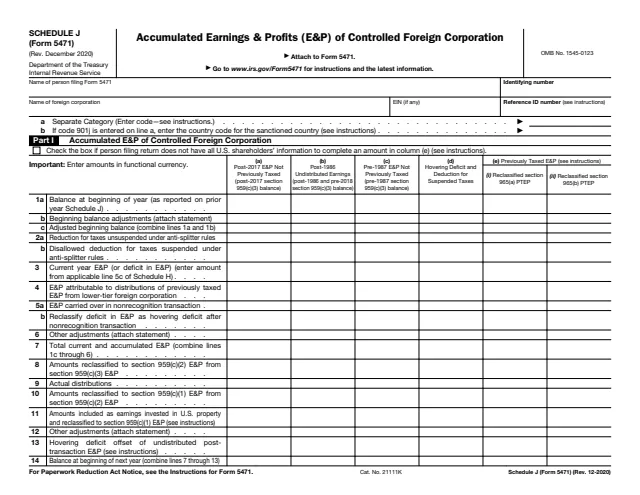
Complete the lines named at the end of the chosen election. Lines 3 and 7 need an attached calculation schedule, plus Schedule J (Form 5471) if a Form 5471 was filed for the year.
Attach the line 9b allocation statement. Line 19 adds interest from the election year's due date, without extensions, to the date the form and payment are filed.
Sign page 2. For a closed election year, file the closing agreement in duplicate with original signatures. Complete the balance sheet for Election B or D.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file it separately from the income tax return. The instructions give: Internal Revenue Service, Deposit Team, M/S 6059, Attn: Specials Desk, Ogden, UT 84201.
Make the check or money order payable to "United States Treasury" with the identifying number and "Form 8621-A" on it. The instructions say the form won't be processed without full payment of line 21.
Page 3 of the form is the IRS copy. A photocopy marked "Taxpayer Copy" goes as the first attachment and is returned after an IRS official signs it. Photocopied signatures aren't accepted.
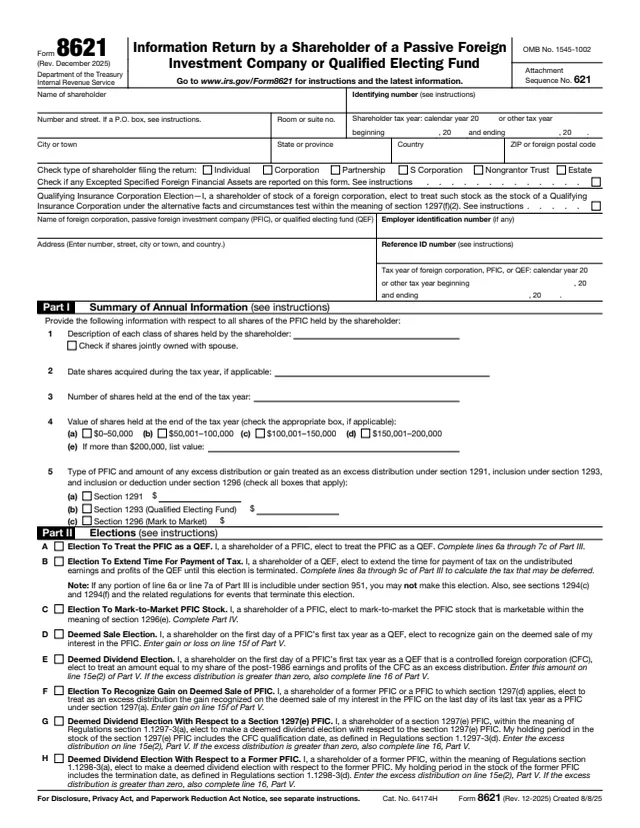
A copy of any Form 8621 filed for a year with an excess distribution, the line 9b statement, and for intangible assets on the balance sheet a written valuation narrative.
Checking more than one election, skipping the attachments named on lines 3, 7 and 9b, sending the closing agreement in one copy, and leaving out full payment of the balance due.
8621
151 fields, 4 pages

5471
437 fields, 6 pages
5471 Sch. J
282 fields, 3 pages

2848
92 fields, 2 pages
The instructions define the shareholder as a U.S. person that is a direct or indirect shareholder of the foreign corporation. Page 1 asks which type of shareholder is filing.
No tool matches that search.
The instructions say a timely purging election is made on Form 8621. Form 8621-A is used only to make a late purging election under section 1298(b)(1).
The instructions say it is late when made more than 3 years after the due date, as extended, of the return for the year that includes the termination date or the CFC qualification date.
No. The form says to file it separately from the income tax return, and the instructions give an IRS address in Ogden, UT 84201.
The instructions say a closing agreement on page 3 is entered into if the election year is a closed tax year. It is filed in duplicate, both with original signatures.
Yes. The instructions say the amount is computed as if the election were timely, plus interest from the election year's return due date, without extensions, to the date the late election is filed.
Yes. The instructions say to enter the other person's information as the shareholder contact and attach Form 2848.