Name, SSN and address
Name and social security number, plus an address block filled in only when the form is filed by itself and not with a tax return. A box marks an amended return.
8915-D
Qualified 2019 Disaster Retirement Plan Distributions and Repayments
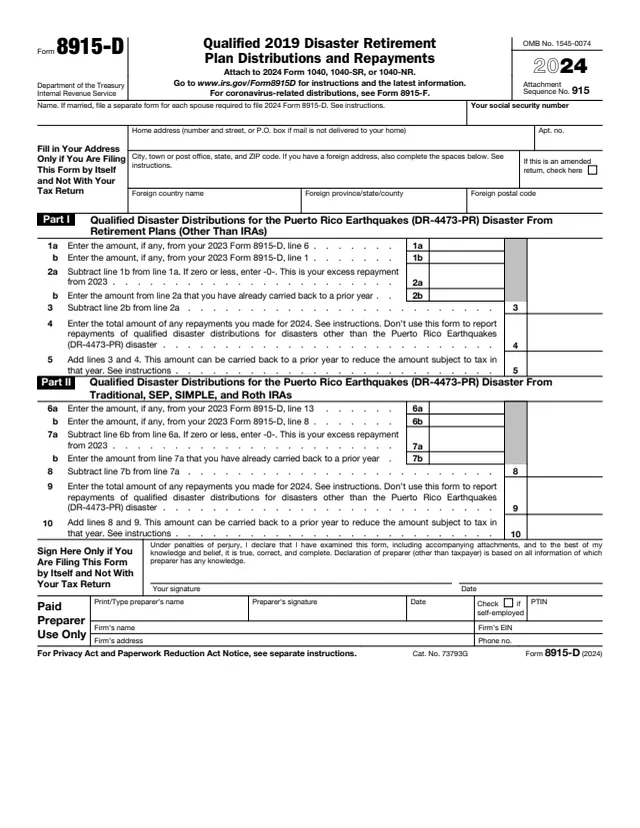
Form 8915-D is titled Qualified 2019 Disaster Retirement Plan Distributions and Repayments. The instructions say 2024 Form 8915-D is used to report repayments made in 2024 of qualified disaster distributions for the 2019 Puerto Rico Earthquakes (DR-4473-PR) disaster. This page covers the 2024 form.
The instructions say the repayment period for a qualified 2019 disaster distribution ends 3 years and 1 day after the distribution was received, and that the only qualified 2019 disaster distributions that could be repaid in 2024 are those made in 2021 for that disaster. Repayments reported on the 2024 form can reduce the income reported on a 2021, 2022 or 2023 return, as applicable.
Coronavirus-related distributions and qualified 2021 and later disasters are covered by Form 8915-F instead. You can fill out the form free in your browser on this page and download the result without an account.
Name and social security number, plus an address block filled in only when the form is filed by itself and not with a tax return. A box marks an amended return.
Lines 1a to 5 bring forward amounts from the 2023 Form 8915-D, figure any excess repayment from 2023 and add repayments made for 2024.
Lines 6a to 10 do the same for traditional, SEP, SIMPLE and Roth IRAs.
The total of the remaining excess and 2024 repayments. The form says this amount can be carried back to a prior year to reduce the amount subject to tax in that year.
A signature area used only when the form is filed by itself and not with a tax return, and a paid preparer section.
The instructions say to write "Puerto Rico Earthquakes (DR-4473-PR)" at the top of page 1 of the 2024 Form 8915-D.
Part I is completed for 2024 repayments of amounts from line 10 of the 2021 Form 8915-D. Enter amounts from lines 6 and 1 of the 2023 form, subtract for line 2a, enter on line 2b any part already carried back, and subtract for line 3.
Enter repayments made in 2024 of qualified disaster distributions made in 2021 for the disaster. The instructions say to include only repayments made within the 3-year repayment period and not repayments of nontaxable amounts.
Part II is completed for 2024 repayments of amounts from line 26 of the 2021 Form 8915-D. It uses lines 13 and 8 of the 2023 form and follows the same steps as Part I.
Add the lines as the form shows. For a carryback, the instructions name the line of the 2021, 2022 or 2023 Form 8915-D to use and a sentence to write on the dotted line beside it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to file it with 2024 Form 1040, 1040-SR or 1040-NR. When no income tax return is required, it goes to the IRS by itself at the same time and place that return would otherwise be filed.
The instructions say an amount paid more than 3 years and 1 day after the distribution was received cannot be treated as a repayment, and a repayment cannot be more than the original distribution.
The instructions list distributions received as a beneficiary (other than a surviving spouse), required minimum distributions, and certain series of substantially equal periodic payments from plans other than IRAs.
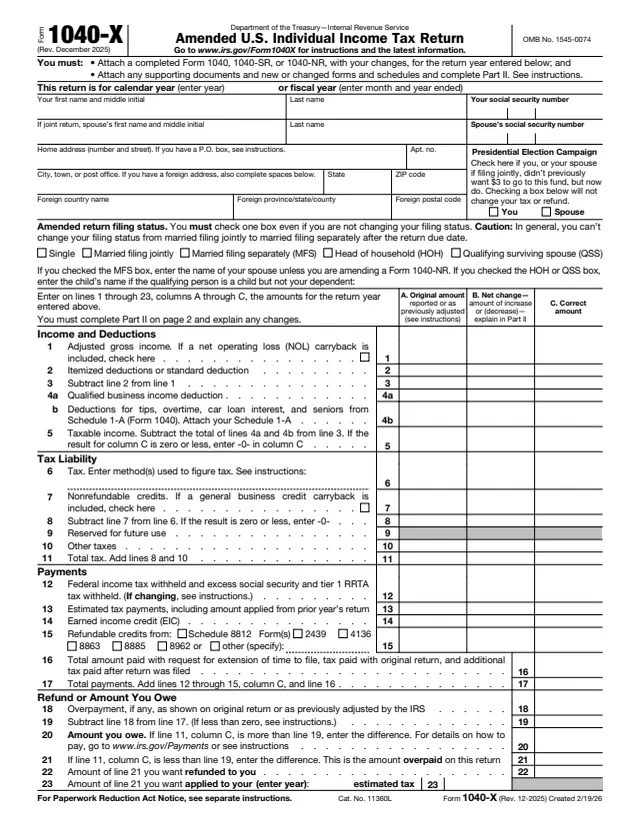
The instructions say an amended return may be needed depending on when a repayment is made. They point to Form 1040-X, generally filed within 3 years after the original return was filed or within 2 years after the tax was paid, whichever is later.
The instructions say these distributions aren't subject to the additional 10% tax (or the 25% additional tax for certain distributions from SIMPLE IRAs) on early distributions.
8915-F
101 fields, 4 pages
8915-B
30 fields, 1 page
1040-X
166 fields, 2 pages

1040
199 fields, 2 pages
1040-SR
200 fields, 4 pages
1040-NR
171 fields, 2 pages
The form is filed by the individual who made the repayment, with an individual income tax return or by itself.
No tool matches that search.
The instructions say it reports 2024 repayments of qualified disaster distributions for the 2019 Puerto Rico Earthquakes (DR-4473-PR) disaster.
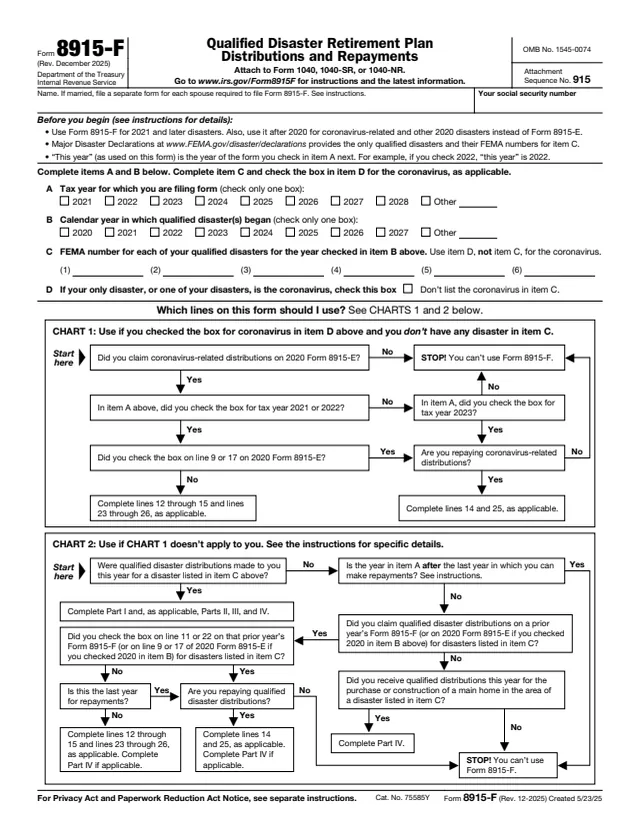
The instructions say 2023 was the last year in which a coronavirus-related distribution could be repaid, and those repayments were reported on Form 8915-F.
The instructions say it is generally included in income in equal amounts over 3 years, unless the entire distribution was elected to be included in the year of the distribution.
The instructions say repaid amounts are treated as a trustee-to-trustee transfer and are not included in income, and a repayment to an IRA is not considered a rollover for the one-rollover-per-year limitation.
Yes, when no income tax return is required. The instructions say to fill in the address on page 1, sign the form and send it at the time and place the return would otherwise be filed.
The form says the amount on line 5 or line 10 can be carried back to a prior year to reduce the amount subject to tax in that year, which may involve an amended return.