Items A to D and the charts
The tax year, the year the disaster began, up to six FEMA numbers and a coronavirus box, followed by Charts 1 and 2 that show which lines to complete.
8915-F
Qualified Disaster Retirement Plan Distributions and Repayments
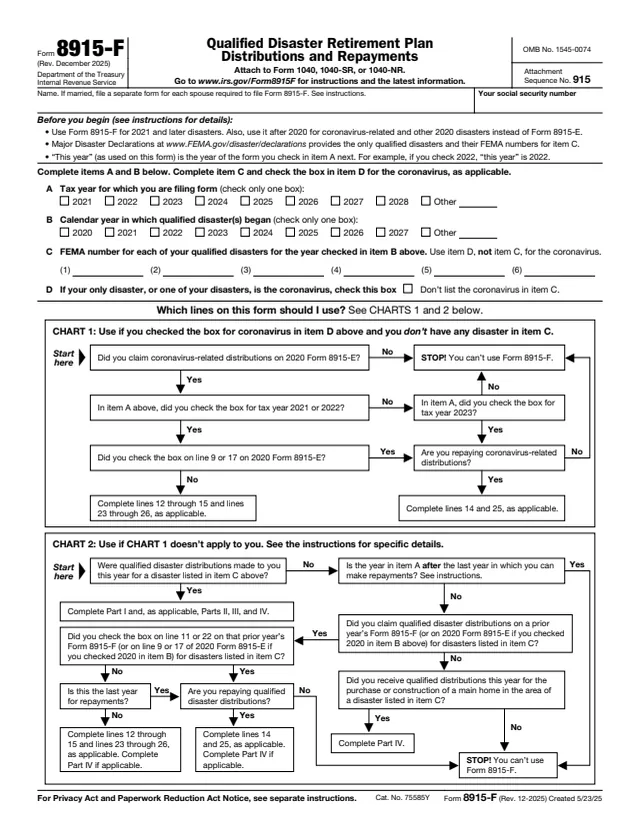
Form 8915-F is the IRS form used to report qualified disaster distributions from retirement plans and IRAs, the income from those distributions and any repayments. The About page says it is for people who were adversely impacted by the coronavirus or affected by a qualified 2020 or later disaster, and that it replaces Form 8915-E beginning in 2021. The instructions call it a forever form: the same Form 8915-F is used for each year of reporting, and the boxes checked in items A and B show the tax year and the year the disaster began.
The form is attached to the individual's Form 1040, 1040-SR or 1040-NR. The instructions say a qualified disaster distribution is generally included in income in equal amounts over 3 years, unless the taxpayer elects to include all of it in the year of the distribution, and that these distributions aren't subject to the additional 10% tax (or the 25% additional tax for certain SIMPLE IRA distributions) on early distributions.
This page hosts the December 2025 revision. You can fill it out free in your browser on this page and download the result without an account.
The tax year, the year the disaster began, up to six FEMA numbers and a coronavirus box, followed by Charts 1 and 2 that show which lines to complete.
A disaster table and lines 1a to 7 for the available amount, distributions this year from plans, traditional IRAs and Roth IRAs, the qualified disaster distributions and the taxable remainder.
Lines 8 to 15 for the taxable amount, the election on line 11, income from prior years, repayments and the amount that goes on line 5b of the return.
Lines 16 to 26 for IRA distributions, the link to Form 8606, the election on line 22, income from prior years, repayments and the amount that goes on line 4b.
A disaster table with ending dates and lines 27 to 32 for qualified distributions for the purchase or construction of a main home, repayments and the taxable amount.
On a joint return, the instructions say to enter only the name and SSN of the spouse whose information is reported. Check one box in item A for the tax year and one in item B for the calendar year the disaster began.
Enter the FEMA number of each qualified disaster from Major Disaster Declarations at www.FEMA.gov/disaster/declarations. The coronavirus goes in item D, not item C.
Chart 1 is for the coronavirus with no disaster in item C; Chart 2 covers everything else. Each chart ends at the lines to complete, or at a box that says the form can't be used.
The form uses $22,000 per disaster for 2021 and later disasters and $100,000 for 2020 disasters. Allocate distributions in column (b) so they do not exceed the available amount on line 1e.
The taxable amount is spread over 3 years unless the box is checked to include it all this year. The form ties the two elections together: checking the box on line 11 or 22 means checking it on the other line too.
Worksheets 3 and 5 in the instructions figure repayments for lines 14 and 25. The instructions say a repayment is made within 3 years from the day after the distribution was received and can't exceed the original distribution.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach it to Form 1040, 1040-SR or 1040-NR for the year checked in item A. The instructions give the example of a 2025 Form 8915-F (2024 disasters) filed with the 2025 return.
The instructions say Form 8915-F can be completed electronically and e-filed with the tax return, and that the IRS recommends electronic filing whenever possible.
The instructions say the form is filed with the relevant original or amended return before the time for filing that return has expired. Some carrybacks of repayments use an amended return.
The instructions say the limit is $22,000 per disaster for qualified 2021 and later disasters. It was $100,000, but that was for qualified 2020 disasters.
Amounts paid later than 3 years and 1 day after the distribution was received can't be repayments. For Part IV home distributions, the instructions say the repayment period is much shorter than 3 years.
When Worksheets 2 to 5 from the instructions are used, the form says to attach them to the back of Form 8915-F.
8606
45 fields, 2 pages
8915-D
30 fields, 1 page
8915-B
30 fields, 1 page
1099-R
257 fields, 9 pages
5329
75 fields, 3 pages
1040-X
166 fields, 2 pages
The instructions say to file it for the year checked in item A if any of the following apply for the disasters listed in items C and D.
No tool matches that search.
The About page says it replaces Form 8915-E beginning in 2021. The instructions say 2020 Form 8915-E is still used for qualified 2020 disaster distributions made in 2020.
The instructions say $22,000 per disaster for qualified 2021 and later disasters. The $100,000 limit applied to qualified 2020 disasters.
Generally no. The instructions say it is included in income in equal amounts over 3 years, starting with the year of the distribution, unless the taxpayer elects to include all of it in that year.
The instructions say qualified disaster distributions aren't subject to the additional 10% tax, or the 25% additional tax for certain traditional SIMPLE and Roth SIMPLE IRA distributions, on early distributions.
The form says Major Disaster Declarations at www.FEMA.gov/disaster/declarations provides the only qualified disasters and their FEMA numbers for item C.
No. The instructions say that if both spouses are required to file Form 8915-F, a separate form is filed for each of them.
The instructions say additional alphabetical Forms 8915, such as Form 8915-G or Form 8915-H, will not be issued. The same Form 8915-F is used for later years.