Employer information
The employer identification number (EIN), the name (not the trade name) and the calendar year.
941 Sch. B
Report of Tax Liability for Semiweekly Schedule Depositors
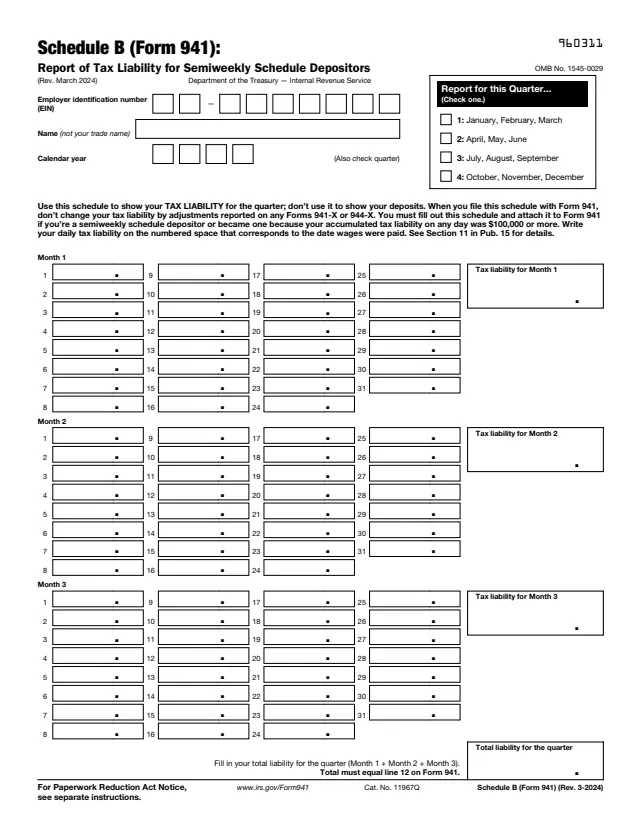
Schedule B (Form 941), Report of Tax Liability for Semiweekly Schedule Depositors, is an attachment to Form 941, Employer's QUARTERLY Federal Tax Return. The form says it shows the employer's tax liability for the quarter, not its deposits, and that each day's liability goes on the numbered space that matches the date wages were paid.
The instructions say the liability includes the federal income tax withheld from employees' pay and both the employer and employee share of social security and Medicare taxes. The IRS uses Schedule B to determine whether federal employment tax liabilities were deposited on time. The instructions say that if a semiweekly schedule depositor doesn't properly complete and file it with Form 941, the IRS may propose an "averaged" failure-to-deposit (FTD) penalty.
The schedule is one page: the employer's EIN, name, calendar year and quarter, then three months of 31 daily spaces each and a total for the quarter. The PDF can be filled out free in the browser on this page and downloaded without an account.
The employer identification number (EIN), the name (not the trade name) and the calendar year.
Four boxes, one per quarter: January to March, April to June, July to September and October to December. One box is checked.
Thirty-one numbered spaces for the days of the first month of the quarter, and a box for the tax liability for Month 1.
The same 31 daily spaces and a monthly total box for the second and third months of the quarter.
Month 1 plus Month 2 plus Month 3. The form says the total equals line 12 on Form 941.
Enter the EIN and name. The instructions say they exactly match the name and EIN the IRS assigned to the business and those on the attached Form 941 or 941-X.
Enter the calendar year and check the box for the quarter. The instructions say the quarter checked matches the quarter checked on Form 941 or 941-X.
Enter the tax liability on the line for the date wages were paid, not the date liabilities accrued or deposits were made. In the instructions' example, wages paid on January 6 go on line 6 of Month 1.
The instructions say semiweekly depositors account for the qualified small business payroll tax credit for increasing research activities claimed on Form 941, line 11, and don't reduce a daily liability below zero.
Add each month's entries for its monthly total, then add the three months. The form says the total for the quarter equals line 12 on Form 941.
File the schedule with Form 941 for the same quarter. The instructions say to check the semiweekly schedule depositor box in Part 2 of Form 941.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say Schedule B is filed with Form 941, so its due date is the same as the due date for that Form 941. In some situations it is filed with Form 941-X.
The form says not to change the tax liability by adjustments reported on any Forms 941-X or 944-X when filing Schedule B with Form 941.
After an FTD penalty assessment for an error that doesn't change the quarter's total, the instructions describe an amended Schedule B with "Amended" written at the top, filed at the address in the penalty notice.
The instructions say an amended Schedule B is filed with a late Form 941-X that shows a tax increase, and can be filed with Form 941-X for a tax decrease when an FTD penalty was assessed.
The instructions say not to use Schedule B to show federal tax deposits, because the IRS gets deposit data from electronic funds transfers.
941
116 fields, 3 pages
941-X
352 fields, 6 pages
945-A
748 fields, 2 pages
944
114 fields, 3 pages
8974
107 fields, 1 page
6765
270 fields, 4 pages
Schedule B is completed by employers that file Form 941 and are semiweekly schedule depositors. Employees do not fill it out.
No tool matches that search.
The instructions say semiweekly schedule depositors file it: employers that reported more than $50,000 of employment taxes in the lookback period or accumulated a tax liability of $100,000 or more on any given day in the current or prior calendar year.
No. The form says it shows the tax liability for the quarter, not deposits, and the instructions say the IRS gets deposit data from electronic funds transfers.
The date wages were paid. The instructions say entries go in the spaces for the dates wages were paid, not the date payroll liabilities were accrued or deposits were made.
No. The instructions say not to file it as an attachment to Form 944. A semiweekly schedule depositor that reports a tax liability with Form 944 uses Form 945-A.
The instructions say not to complete Schedule B if the tax liability on Form 941, line 12, is less than $2,500 during the quarter.
When an FTD penalty was assessed, the instructions describe filing an amended Schedule B marked "Amended" at the address in the penalty notice. The IRS then refigures the penalty.