Header
EIN, legal and trade names, address, the return being corrected (941 or 941-SS), the quarter and calendar year, the date the errors were discovered, and the aggregate filer boxes.
941-X
Adjusted Employer's Quarterly Federal Tax Return or Claim for Refund (Spanish Version)
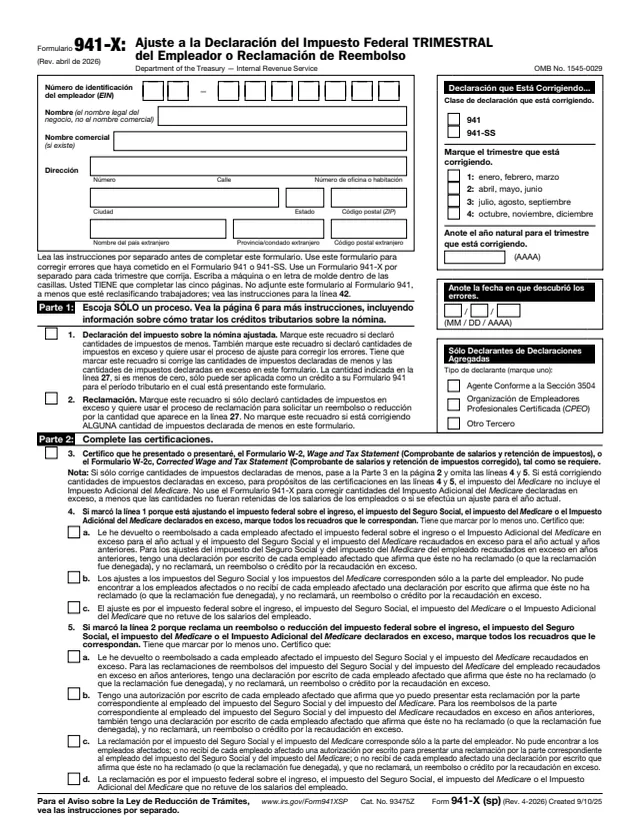
Form 941-X (sp) is the Spanish version of Form 941-X, Adjusted Employer's QUARTERLY Federal Tax Return or Claim for Refund. The PDF is in Spanish, under the title "Ajuste a la Declaración del Impuesto Federal TRIMESTRAL del Empleador o Reclamación de Reembolso". The English Instructions for Form 941-X say Form 941-X or Form 941-X (sp) is used to correct a Form 941 or Form 941 (sp), respectively, filed for the first quarter of 2024 or later quarters.
The form says it corrects errors made on Form 941 or 941-SS. It asks the employer to choose one process, an adjusted return or a claim, to certify how Forms W-2 and W-2c and affected employees were handled, to enter corrections line by line in four columns, and to explain them. It says to use a separate Form 941-X for each quarter being corrected and to complete all five pages.
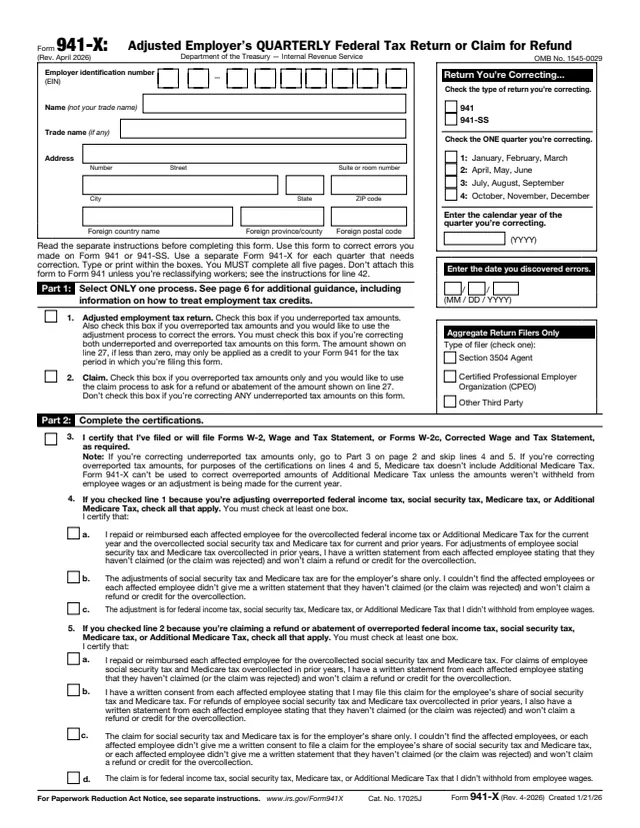
The English edition, Form 941-X, carries the same April 2026 revision. The PDF can be filled out free in the browser on this page and downloaded without an account.
EIN, legal and trade names, address, the return being corrected (941 or 941-SS), the quarter and calendar year, the date the errors were discovered, and the aggregate filer boxes.
Line 1 is the adjusted employment tax return. Line 2 is the claim for a refund or abatement of the amount on line 27.
Line 3 certifies that Forms W-2 or W-2c have been or will be filed. Lines 4 and 5 hold boxes about repaying employees, their written statements and the employer's share.
Lines 6 to 40 on pages 2 to 4, each tied to a Form 941 line, with columns for the corrected total, the amount originally reported, the difference and the tax correction.
Line 41 for corrections with both underreported and overreported amounts, line 42 for reclassified workers, and line 43 for a detailed explanation.
The signature, printed name, title, date and daytime phone, the paid preparer section, and a page 6 chart titled "¿Qué proceso debe usar?" (Which process should you use?).
Enter the EIN, names and address, check 941 or 941-SS, check the quarter, and enter the year (AAAA) and the discovery date (MM/DD/AAAA). Pages 2 to 5 repeat the name, EIN, quarter and year.
Check line 1 or line 2. The form says line 1 is checked when correcting both underreported and overreported amounts, and line 2 is not checked if any underreported amount is corrected.
Check line 3. The form says to skip lines 4 and 5 when correcting only underreported amounts. For overreported amounts, at least one box on line 4 or line 5 is checked.
On each line that changes, enter the corrected total, the amount originally reported or as previously corrected, and the difference, with a minus sign if negative. Line 8 multiplies by 0.124, or 0.062 for the employer share only.
Line 23 combines column 4 of lines 7 to 22, and line 27 combines lines 23 to 26c. Check lines 41 and 42 if they apply, then explain on line 43 how the corrections were determined.
The signer prints their name and title, signs, dates and adds the best daytime phone. A paid preparer completes the section below.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
To the IRS. The English instructions encourage electronic filing. For paper, their state chart lists Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0005 or Ogden, UT 84201-0005, and Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 with no legal residence or principal place of business in any state.
The form says a line 27 amount above zero is owed and is paid by the time the return is filed. It points to the instructions for how to pay.
With line 1 checked, the amount is credited to Form 941 for the period in which this form is filed. With line 2 checked, it is the amount to be refunded or abated.
The page 6 chart says that within 90 days before the period of limitations for credit or refund expires, overreported amounts are corrected only through the claim process.
The form says not to attach it to Form 941 unless reclassifying workers, as described in the instructions for line 42.
941-X
352 fields, 6 pages
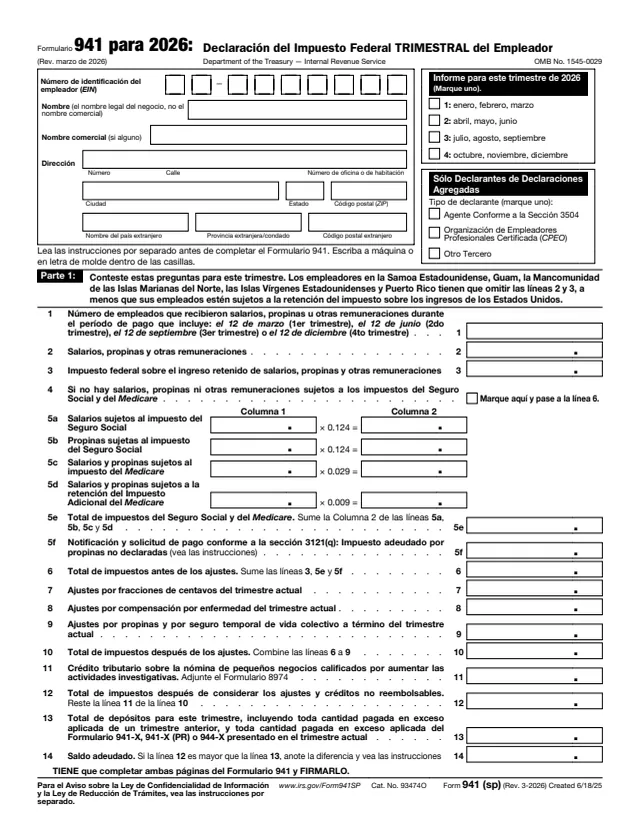
941
120 fields, 3 pages
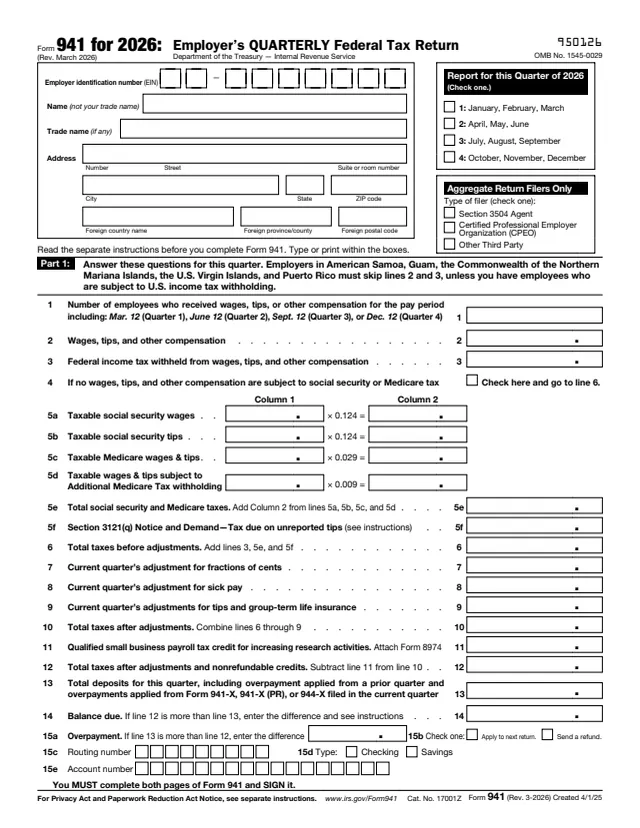
941
116 fields, 3 pages
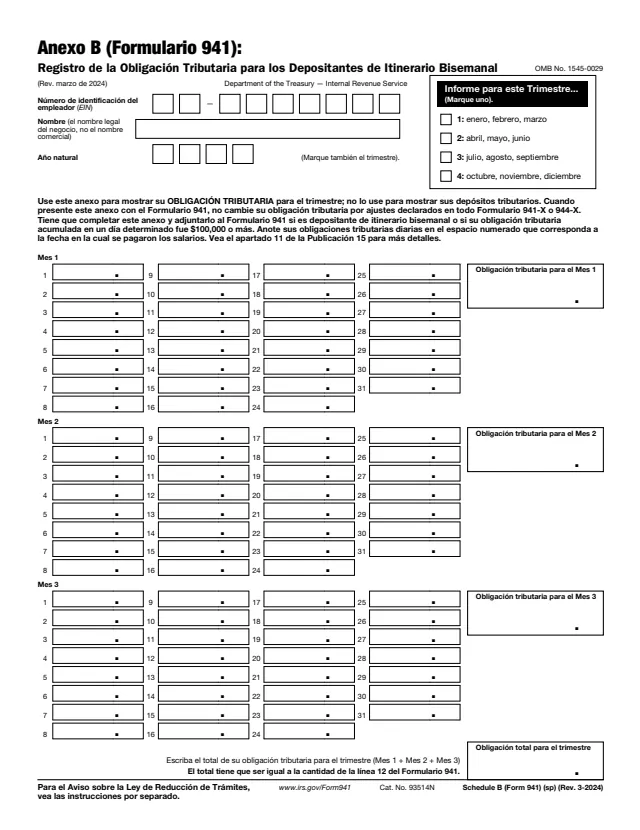
941 Sch. B
212 fields, 1 page
W-2c
540 fields, 9 pages
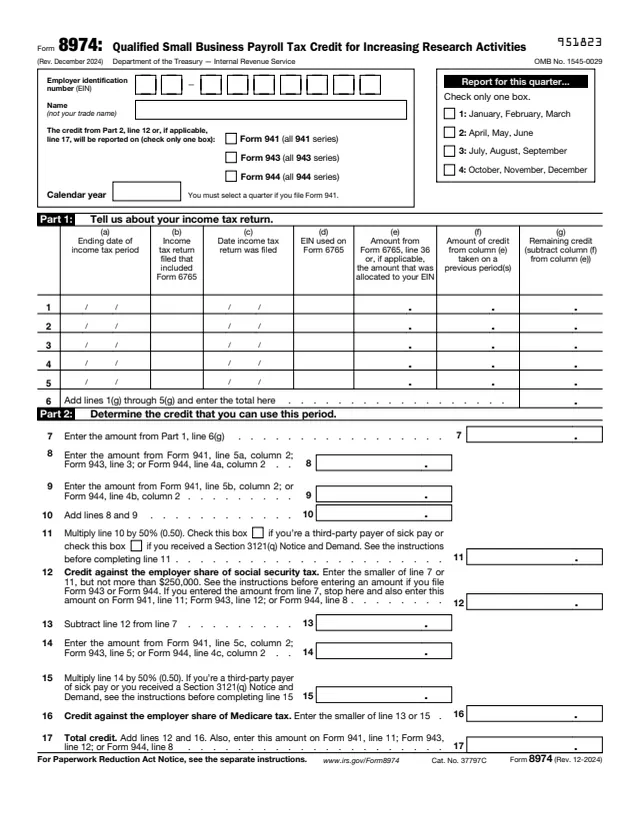
8974
107 fields, 1 page
The employer that filed the quarterly return, or a third party filing an aggregate return, completes it and sends it to the IRS. Employees do not file it.
No tool matches that search.
The PDF is in Spanish. The IRS lists it as the Spanish Version of Form 941-X. This page describes it in English.
Yes. Form 941-X is the English edition. The IRS lists both at the April 2026 revision.
The form says Form 941 or 941-SS. The English instructions say Form 941-X (sp) corrects a Form 941 (sp) filed for the first quarter of 2024 or later, and that a Form 941-PR for the fourth quarter of 2023 or earlier is corrected on Form 941-X (PR).
The form says to read the separate instructions first and prints www.irs.gov/Form941XSP. This page links the IRS Instructions for Form 941-X, which are in English.
No. The form says to use a separate Form 941-X for each quarter being corrected.
Line 1 is the adjustment process, where a negative total is credited to Form 941. Line 2 is the claim process, used only for overreported amounts, to ask for a refund or abatement.
Yes. The PDF can be filled out in the browser on this page and downloaded without an account.