Part I: excess benefit transactions
Line 1 lists each disqualified person, the relationship, a description and whether it was corrected. Line 2 is the section 4958 tax incurred and line 3 the amount the organization reimbursed.
990 Sch. L
Transactions With Interested Persons
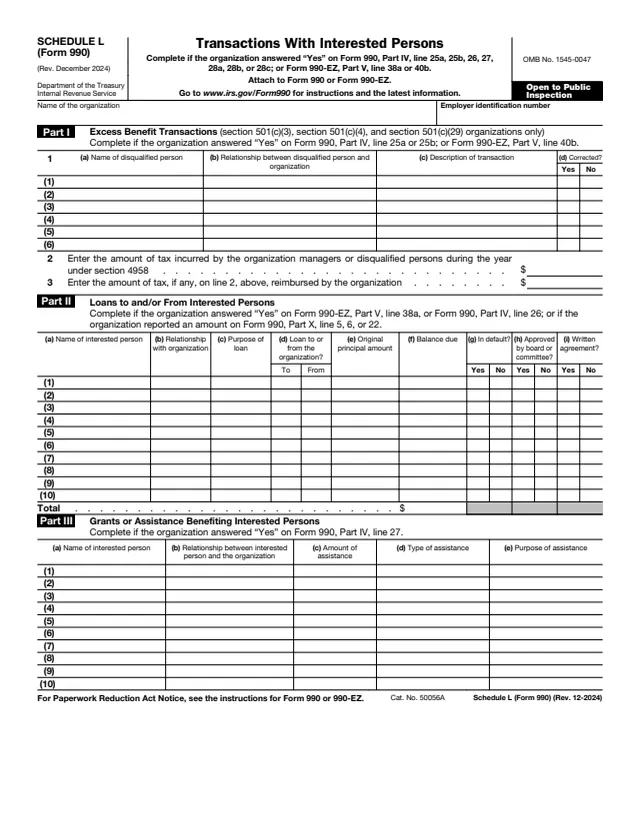
Schedule L (Form 990), Transactions With Interested Persons, is attached to Form 990 or Form 990-EZ. The IRS page says organizations that file those returns use it to give information on certain financial transactions or arrangements between the organization and disqualified persons under section 4958 or other interested persons. It is also used to determine whether a member of the governing body is an independent member.
The schedule has five parts: excess benefit transactions, loans to or from interested persons, grants or assistance benefiting interested persons, business transactions involving interested persons, and supplemental information. An organization completes only the parts tied to the questions it answered Yes on its return.
The form is marked Open to Public Inspection. The instructions say this revision is a continuous-use form for tax year 2024 and later years until a new revision is issued. You can fill out Schedule L free in your browser on this page and download it without an account.
Line 1 lists each disqualified person, the relationship, a description and whether it was corrected. Line 2 is the section 4958 tax incurred and line 3 the amount the organization reimbursed.
Up to 10 rows: name, relationship, purpose, to or from the organization, original principal, balance due, in default, approved by board or committee, and written agreement, plus a total.
Up to 10 rows: name of the interested person, relationship, amount of assistance, type of assistance and purpose of assistance.
Up to 10 rows on page 2: name, relationship, amount of transaction, description, and whether the deal shares the organization's revenues.
Free space to explain answers to other questions on Schedule L, identifying the part and line each response supports.
Enter the name of the organization and its employer identification number, the same as on the Form 990 or 990-EZ it is attached to.
In each part, column (a) names the person and column (b) gives the relationship, such as officer or family member of director. The instructions say to write substantial contributor or related to substantial contributor instead of a name when that is the only link.
Describe each excess benefit transaction, regardless of amount, and whether it was corrected. Line 2 is the section 4958 excise tax incurred unless abated. Organization managers who knowingly took part are named in Part V.
Report each loan outstanding at the end of the tax year, regardless of amount. The instructions list exceptions such as advances under an accountable plan and pledges receivable. For Form 990 filers, the column (f) total matches the Part X balance sheet lines.
Report each grant or assistance to an interested person during the tax year, regardless of amount. The instructions say schools group each type of financial aid on separate lines and leave columns (a) and (b) blank.
Report business transactions above the thresholds in the instructions, for example all payments to one interested person over $100,000, or compensation over $10,000 to a family member of a listed officer. Transactions may be listed one by one or added together.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Schedule L to Form 990 or Form 990-EZ. It is not filed by itself.
The form is marked Open to Public Inspection.
The instructions say each reportable transaction is reported in only one part of Schedule L.
The instructions say a transaction need not be reported if, after a reasonable effort, the organization cannot get enough information to conclude it is reportable. An annual questionnaire to likely interested persons is given as an example.
Parts I to IV can be duplicated if more space is needed, and Part V can be used to explain a transaction.
The instructions say Form 4720 is filed to report and pay the tax on excess benefit transactions reported in Part I.
990
1,075 fields, 12 pages
990-EZ
325 fields, 4 pages
4720
666 fields, 10 pages
990 Sch. J
281 fields, 3 pages
990 Sch. B
201 fields, 4 pages
990 Sch. O
3 fields, 1 page
The organization that files Form 990 or Form 990-EZ completes the schedule and attaches it to that return. The instructions include a chart that ties each part to a Yes answer on the return.
No tool matches that search.
An organization that files Form 990 or Form 990-EZ and answered Yes to certain questions on that return. It attaches the schedule to the return.
For Part I, a disqualified person under section 4958. For Parts II to IV, the instructions list current and former officers, directors, trustees and key employees, creators or founders, substantial contributors, their family members and 35% controlled entities, among others.
The instructions say Parts I, II and III report all transactions regardless of amount. Part IV has its own reporting thresholds, such as payments over $100,000 to one interested person during the year.
When a person is an interested person only as a substantial contributor or someone related to one, the instructions say to enter substantial contributor or related to substantial contributor instead of the name.
The form is marked Open to Public Inspection.
Rev. December 2024. The instructions say it is a continuous-use form for tax year 2024 and later years until a superseding revision is issued.