Part I: Accumulation Distribution in 2025
Lines 1 to 5 take amounts from Form 1041, Schedule B, lines 10, 7 and 9 and figure the accumulation distribution for 2025.
1041
Accumulation Distribution for Certain Complex Trusts
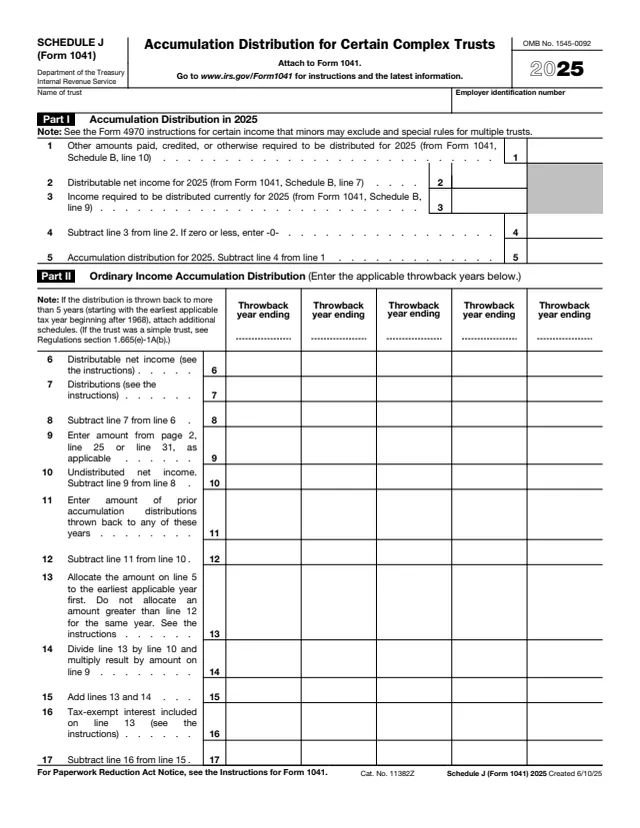
Schedule J (Form 1041) reports an accumulation distribution for certain complex trusts. The instructions say to use it for a domestic complex trust that was previously treated at any time as a foreign trust, or that was created before March 1, 1984, unless that trust would not be aggregated with other trusts under the rules of section 643(f) if that section applied to the trust. The form says to attach it to Form 1041.
The instructions define an accumulation distribution as the excess of amounts properly paid, credited, or required to be distributed (other than income required to be distributed currently) over the trust's distributable net income (DNI) reduced by income required to be distributed currently. The schedule throws that distribution back to earlier years, figures the taxes imposed on undistributed net income for those years, and allocates the amounts to each beneficiary, who uses Form 4970.
You can fill out Schedule J (Form 1041) free in your browser on this page and download it without an account.
Lines 1 to 5 take amounts from Form 1041, Schedule B, lines 10, 7 and 9 and figure the accumulation distribution for 2025.
Lines 6 to 17, in one column per throwback year, figure undistributed net income and allocate the line 5 amount to the earliest applicable year first.
Lines 18 to 25 figure the tax on undistributed net income for each throwback year. Lines 26 to 31 are used only if the trust elected the alternative tax on long-term capital gain.
The beneficiary's name, identifying number and address, and lines 32 to 37 with this beneficiary's share of lines 13, 14 and 16 for each throwback year.
The form has five throwback year columns. It says to attach additional schedules if the distribution is thrown back to more than 5 years.
Enter amounts from Form 1041, Schedule B, for 2025: line 10 on line 1, line 7 on line 2 and line 9 on line 3.
Subtract line 3 from line 2, entering -0- if zero or less, then subtract line 4 from line 1 to get the accumulation distribution for 2025.
Enter the applicable year at the top of each column. The instructions give a table of the earlier Form 1041 lines that hold DNI and distributions; for 1997 to 2024 they are Schedule B, lines 7 and 11.
Allocate the accumulation distribution to the earliest applicable year first, but not more than the amount on line 12 for any throwback year.
For each throwback year, enter the regular tax, the trust's share of net short-term and long-term gain and taxable income from the earlier return. For 1988 to 2024, the regular tax comes from Form 1041, Schedule G, line 1a.
Complete Part IV for each beneficiary. If more than one beneficiary shares the distribution, attach another copy of Schedule J with Part IV completed for each additional beneficiary.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1041. The instructions say calendar year estates and trusts file Form 1041 by April 15, 2026, and fiscal year ones by the 15th day of the 4th month after the tax year ends.
The instructions list Kansas City, MO and Ogden, UT addresses that depend on the state and on whether a check or money order is enclosed, and P.O. Box 409101, Ogden, UT 84409 for a foreign country or U.S. territory.
The instructions say Form 7004 applies for an automatic 5½-month extension of time to file the estate or trust return.
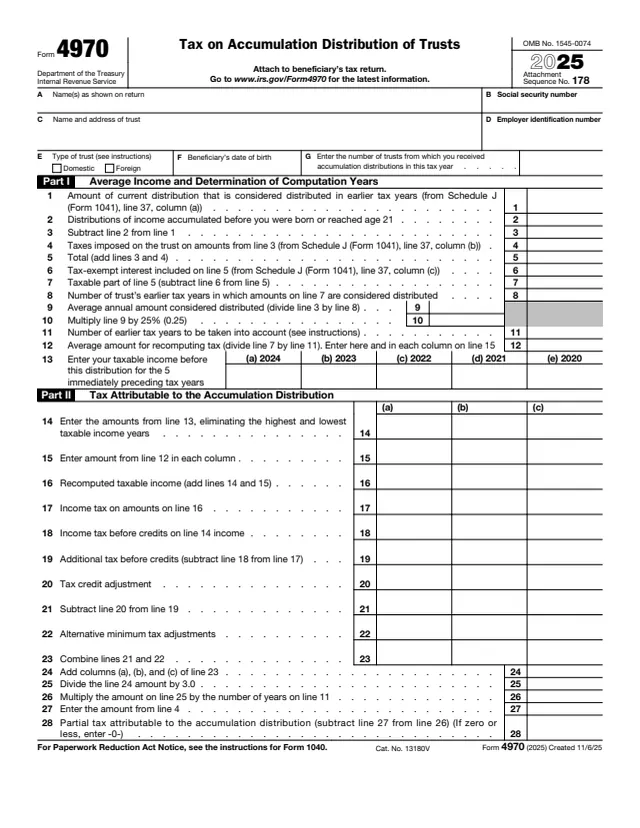
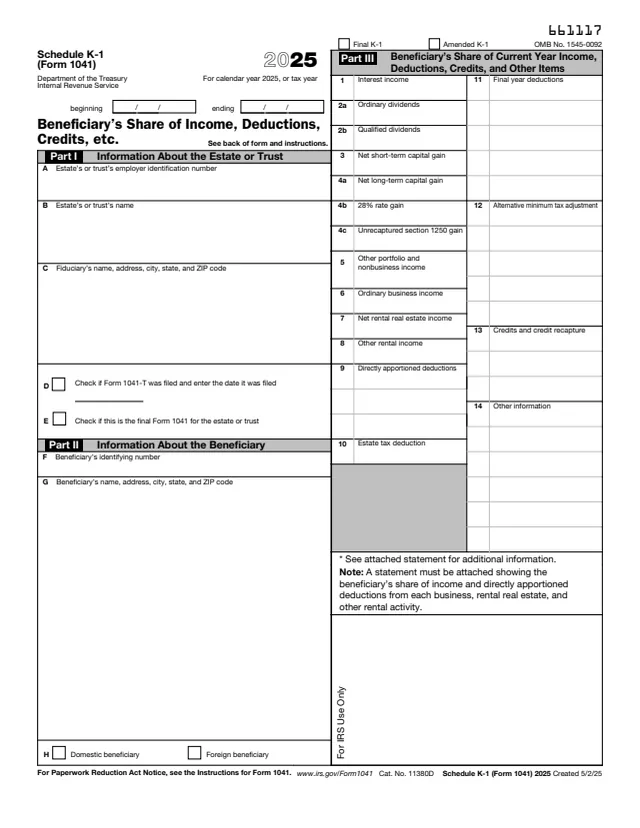
Give each beneficiary a copy of their Part IV information, so they can complete Form 4970.
If the beneficiary is a nonresident alien individual or a foreign corporation, the instructions point to section 667(e) about keeping the character of the amounts distributed to determine U.S. withholding tax.

1041
173 fields, 3 pages
4970
63 fields, 2 pages
1041
74 fields, 2 pages
1041
87 fields, 2 pages
1041
85 fields, 3 pages

7004
26 fields, 1 page
The trustee completes it and files it with the trust's Form 1041. Each beneficiary receives their own Part IV information.
No tool matches that search.
Domestic complex trusts that were previously treated at any time as foreign trusts, and certain domestic complex trusts created before March 1, 1984.
The instructions define it as the excess of amounts properly paid, credited, or required to be distributed (other than income required to be distributed currently) over the trust's DNI reduced by income required to be distributed currently.
An earlier tax year the distribution is thrown back to. The instructions say it goes first to the earliest preceding tax year with undistributed net income, then to the next earliest years.
The trustee gives each beneficiary their Part IV information, and the beneficiary uses Form 4970 to figure the tax on the distribution.
The form says to attach additional schedules. The instructions say to use another Schedule J, completing Parts II and III for each additional throwback year.
With Form 1041. For calendar year estates and trusts, the instructions say Form 1041 is due by April 15, 2026.