Header and category boxes
Calendar or other tax year, name, identifying number, boxes a to g for the category of income, and lines h and i for the country code of a sanctioned country (box e) or treaty country (box f).
1116 Sch. C
Foreign Tax Redeterminations
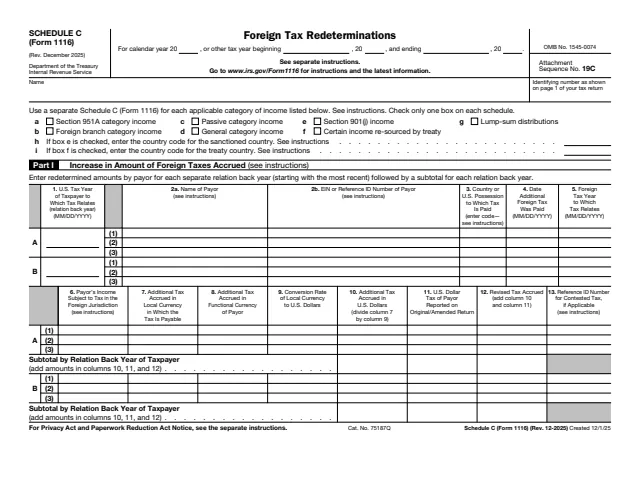
Schedule C (Form 1116), Foreign Tax Redeterminations, is a three-page schedule of Form 1116, Foreign Tax Credit (Individual, Estate, or Trust). It records changes to foreign taxes for the U.S. tax years to which those taxes relate, which the form calls relation back years: an increase in foreign taxes accrued in Part I and a decrease in foreign taxes paid or accrued in Part II, each entered by payor.
Part III shows, for each relation back year, the redetermined foreign taxes against the amounts on the original or amended return, and the foreign tax credit (FTC) claimed before and after the redetermination. Part IV shows the change in U.S. tax liability. Part V is annual reporting for contested foreign taxes for which an election under Regulations section 1.905-1(d)(4) was made to claim a provisional foreign tax credit.
The form says to use a separate Schedule C (Form 1116) for each applicable category of income and to check only one box on each schedule. It does not print its instructions: it says "See separate instructions" and points to www.irs.gov/Form1116. The PDF can be filled out free in the browser on this page and downloaded without an account.
Calendar or other tax year, name, identifying number, boxes a to g for the category of income, and lines h and i for the country code of a sanctioned country (box e) or treaty country (box f).
Columns 1 to 13 cover the relation back year, payor name and EIN or reference ID, country code, dates, payor's income, additional tax in local and functional currency, conversion rate, U.S. dollar amounts and revised tax accrued, with a subtotal per year.
The same layout for tax refunded or deemed refunded. Column 12 subtracts column 10 from column 11, and column 13 is a box to check if the section 905(c)(2) two-year rule applies.
For each relation back year: redetermined foreign taxes, foreign taxes per the original or amended return, and the FTC claimed per that return and after redetermination.
For each relation back year or affected tax year: total redetermined U.S. tax liability, total U.S. tax liability per the original or amended return, and the difference.
Up to five rows with the relation back year, payor, reference ID, country code, amount provisionally claimed, whether the contest is ongoing or resolved, the date resolved, and any tax refunded or additional tax paid.
Enter the tax year, the name and the identifying number shown on page 1 of the tax return. Check only one category box. If box e or f is checked, enter the country code on line h or i.
The form says to enter redetermined amounts by payor for each separate relation back year, starting with the most recent, followed by a subtotal for each year. Column 10 divides column 7 by column 9, and column 12 adds columns 10 and 11.
Enter refunded or deemed refunded amounts the same way, by payor and relation back year. Column 10 divides column 7 by column 9, and column 12 subtracts column 10 from column 11.
For each relation back year, enter the redetermined foreign taxes, the foreign taxes per the original or amended return, and the FTC claimed before and after the redetermination.
Enter the total redetermined U.S. tax liability and the total per the original or amended return for each affected year, then subtract column 3 from column 2.
For each contested tax with a provisional credit election, enter the year, payor, reference ID, country code and amount claimed, check ongoing or resolved, and add the resolution date and any refund or additional tax.
The schedule's line rules are in the separate instructions at www.irs.gov/Form1116. The steps below follow what the form itself prints.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule belongs to Form 1116 and identifies the filer by the name and identifying number shown on page 1 of the tax return. It carries Attachment Sequence No. 19C.
The form says "See separate instructions" and to go to www.irs.gov/Form1116 for instructions and the latest information.
The form says to use a separate Schedule C (Form 1116) for each applicable category of income and to check only one box on each schedule.
Dates are entered as MM/DD/YYYY. Country or U.S. possession columns take a code, and the form says to see the instructions for it.
The schedule asks for the name and the identifying number as shown on page 1 of the tax return, so it is completed by the taxpayer filing Form 1116. It does not itself list who must file; that is in the separate instructions.
No tool matches that search.
The form uses it for the U.S. tax year of the taxpayer to which the foreign tax relates. Amounts are entered and subtotaled by relation back year, starting with the most recent.
No. The form says to use a separate Schedule C (Form 1116) for each applicable category of income and to check only one box on each schedule.
Part I reports an increase in foreign taxes accrued. Part II reports a decrease in foreign taxes paid or accrued, such as tax refunded or deemed refunded.
The form says that beginning with the 2023 tax year, taxpayers enter each contested foreign tax liability for which they previously elected under Regulations section 1.905-1(d)(4) to claim a provisional foreign tax credit.
The schedule does not print them. It says "See separate instructions" and points to www.irs.gov/Form1116.