Part I: Home office expenses
Lines 1a to 12 start from total expenses on the home office books, adjust them to U.S. tax principles, remove interest and bad debt expense, and identify expenses definitely related solely to ECI or non-ECI.
1120-F
Deductions Allocated to Effectively Connected Income Under Regulations Section 1.861-8
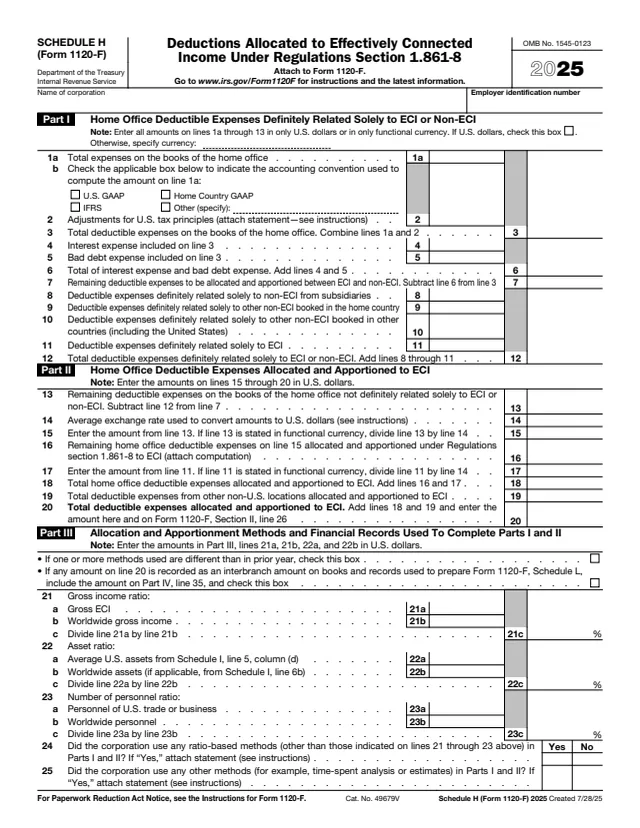
Schedule H (Form 1120-F), Deductions Allocated to Effectively Connected Income Under Regulations Section 1.861-8, is the 2025 schedule a foreign corporation that files Form 1120-F uses to report its deductible expenses allocated and apportioned between effectively connected income (ECI) and non-ECI under Regulations sections 1.861-8 and 1.861-17 and Temporary Regulations section 1.861-8T.
The instructions say Schedule H covers expenses other than interest expense and bad debt expense. Interest expense is allocated under Regulations section 1.882-5 and reported on Schedule I (Form 1120-F), and bad debt expense allocated to ECI goes directly on Form 1120-F, Section II, line 15. The Schedule H result is included on Form 1120-F, Section II, line 26, and, for banks only, on Schedule M-3 (Form 1120-F), Part III, line 31.
The schedule says to attach it to Form 1120-F. You can fill out the PDF free in your browser on this page and download it without an account.
Lines 1a to 12 start from total expenses on the home office books, adjust them to U.S. tax principles, remove interest and bad debt expense, and identify expenses definitely related solely to ECI or non-ECI.
Lines 13 to 20 convert the remaining amounts to U.S. dollars and total the home office and other non-U.S. expenses allocated and apportioned to ECI.
Check boxes for new methods and interbranch amounts, the gross income, asset and number of personnel ratios on lines 21 to 23, and Yes or No questions on other methods on lines 24 and 25.
Lines 26a to 28 ask Yes or No whether audited or non-audited financial statements, home office cost accounting reports, or other records were used in Parts I and II.
Lines 29 to 41 allocate and apportion expenses on the books used to prepare Form 1120-F, Schedule L, reconciled in columns (a) ECI, (b) non-ECI and (c) total.
Check the box if Part I is in U.S. dollars, or specify the functional currency. Enter total home office expenses on line 1a and check the accounting convention on line 1b: U.S. GAAP, home country GAAP, IFRS or other.
Enter adjustments for U.S. tax principles on line 2 and attach a statement by category. Enter interest expense on line 4 and bad debt expense on line 5. Line 7 is what remains to allocate and apportion.
Enter expenses definitely related solely to non-ECI from subsidiaries, booked in the home country, and booked in other countries on lines 8 to 10, and those definitely related solely to ECI on line 11.
If Part I is in a functional currency, enter the average exchange rate on line 14, rounded to at least five places. Attach a computation for line 16 and a statement by location for line 19. Line 20 goes to Form 1120-F, Section II, line 26.
The instructions say the gross income ratio on line 21 is completed whether or not it was used. Report lines 22 and 23 as the instructions direct, attach statements for other methods on lines 24 and 25, and answer lines 26a to 28.
Enter expenses on the Schedule L books, adjust them, remove interest, bad debt and other special items on lines 32a to 35, and reconcile line 37 between ECI and non-ECI. Line 41, column (c), equals line 37.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The schedule says to attach it to Form 1120-F and points to www.irs.gov/Form1120F for instructions and the latest information. It prints no separate deadline or mailing address.
Line 20 goes on Form 1120-F, Section II, line 26. The form says line 41, column (a), is the total of the deductions on Form 1120-F, Section II, lines 12, 13, 14, 16, 17, 19 through 24, and 27.
The form asks for an attached statement or computation with lines 2, 16, 24, 25, 28, 30, 34 and 35, and the instructions add a statement by location for line 19.
Interest expense is reported on Schedule I (Form 1120-F). Bad debt expense allocated to ECI goes directly on Form 1120-F, Section II, line 15.
The instructions say the line 14 exchange rate is rounded to at least five places, and to more places if fewer would materially distort the rate or the U.S. dollar amount.
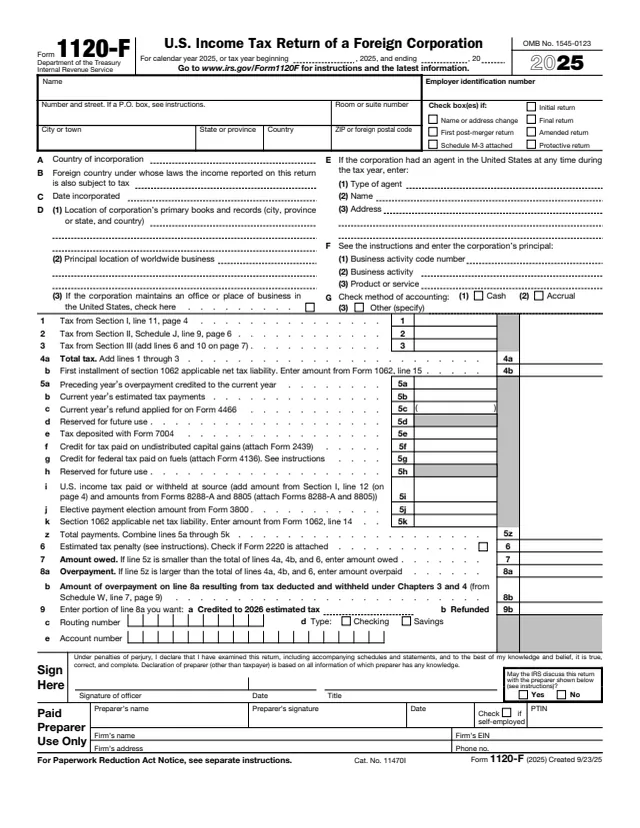
1120-F
527 fields, 9 pages
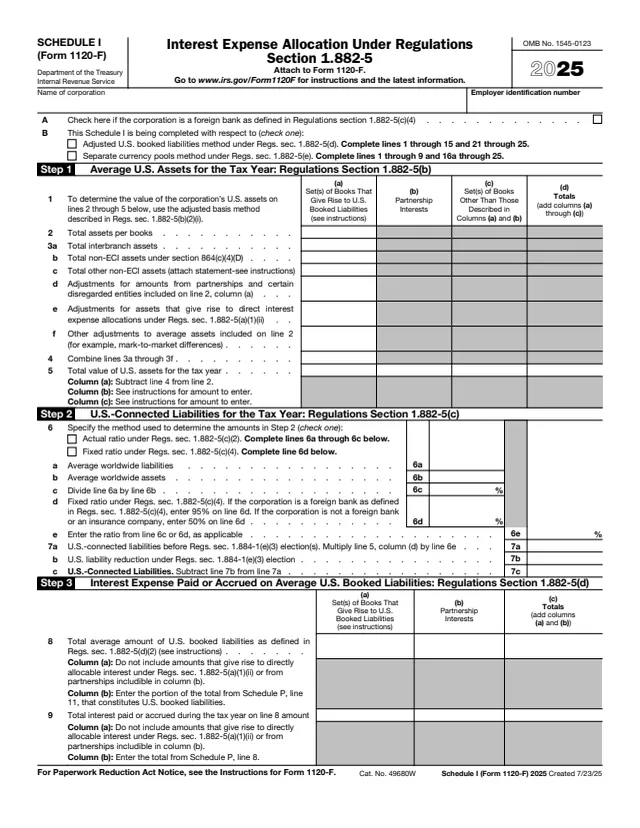
1120-F
113 fields, 3 pages
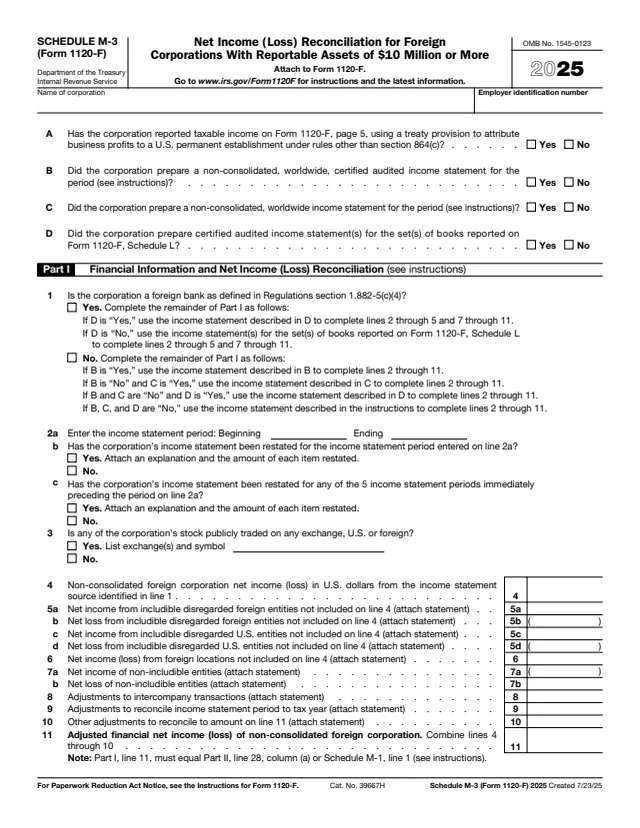
1120-F
439 fields, 4 pages
8833
41 fields, 5 pages
1065
2,862 fields, 21 pages
1120-F
173 fields, 3 pages
The schedule is completed by a foreign corporation and attached to its Form 1120-F. It asks for the name of the corporation and its employer identification number.
No tool matches that search.
The instructions say any foreign corporation required to file Form 1120-F that is, or is treated as, engaged in a U.S. trade or business during the tax year, and any foreign corporation that is a partner in a partnership with deductions allocated to ECI.
No. The instructions say interest expense is allocated under Regulations section 1.882-5 and reported on Schedule I (Form 1120-F).
Line 20 goes on Form 1120-F, Section II, line 26, and, for banks only, on Schedule M-3 (Form 1120-F), Part III, line 31.
Yes. The form says lines 1a through 13 are entered in only U.S. dollars or in only functional currency, with the currency named in the Part I heading. Lines 15 through 20 are in U.S. dollars.
The instructions say it need not be completed or attached to a protective Form 1120-F filed under Regulations section 1.882-4(a)(3)(vi).
The instructions say the gross income ratio on line 21 is completed whether or not the corporation used that method.