Header and items A and B
Corporation name and EIN, the foreign bank check box, and the choice between the adjusted U.S. booked liabilities method and the separate currency pools method.
1120-F
Interest Expense Allocation Under Regulations Section 1.882-5
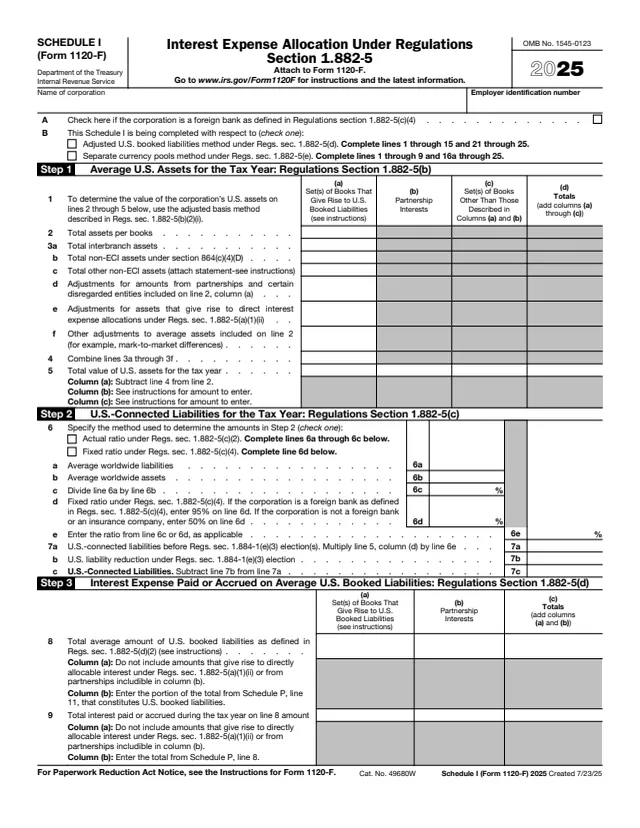
Schedule I (Form 1120-F) is the 2025 schedule a foreign corporation uses to report the amount of interest expense allocable to effectively connected income (ECI) and the deductible amount of that allocation for the tax year under section 882(c) and Regulations section 1.882-5.
The instructions say the schedule discloses the basic calculations for the year and identifies the elections the corporation uses under Regulations sections 1.882-5(a)(7) and (d)(5) and under the branch profits tax rules of Regulations section 1.884-1(e)(3). It follows a three-step formula: average U.S. assets (Step 1), U.S.-connected liabilities (Step 2) and interest expense under either the adjusted U.S. booked liabilities method or the separate currency pools method (Step 3). A summary on page 3 carries the deductible amount to Form 1120-F, Section II, line 18.
The form says to attach it to Form 1120-F. You can fill out Schedule I free in your browser on this page and download it without an account.
Corporation name and EIN, the foreign bank check box, and the choice between the adjusted U.S. booked liabilities method and the separate currency pools method.
Average U.S. assets for the tax year in four columns: books that give rise to U.S. booked liabilities, partnership interests, other books, and totals.
U.S.-connected liabilities, using either the actual ratio (lines 6a to 6c) or the fixed ratio (line 6d), less any liability reduction election on line 7b.
Average U.S. booked liabilities and the interest paid or accrued on them, with a column for partnership interests from Schedule P (Form 1120-F).
Step 3 under the adjusted U.S. booked liabilities method (lines 10 to 15) or under the separate currency pools method by currency (lines 16a to 20).
Allocated interest, direct allocations, deferrals and disallowances on lines 24a to 24g, and the total interest expense deduction on line 25.
Check item A if the corporation is a foreign bank. In item B check one method. The form says the adjusted U.S. booked liabilities method uses lines 1 through 15 and 21 through 25, and the separate currency pools method uses lines 1 through 9 and 16a through 25.
Value U.S. assets with the adjusted basis method. The instructions say large banks and dealers in securities average at least monthly, and other taxpayers at least semiannually (beginning, middle, and end of the tax year).
Check actual ratio or fixed ratio on line 6. The form says a foreign bank enters 95% on line 6d, and a corporation that is not a foreign bank or an insurance company enters 50%. Line 7a multiplies line 5, column (d) by line 6e.
Enter average U.S. booked liabilities and the interest on them. The form says column (b) takes the U.S. booked part of Schedule P, line 11, and the total from Schedule P, line 8.
Under the booked liabilities method, complete lines 10 through 13 if line 7c is greater than line 8, column (c), or lines 14a and 14b if it is not. Under the currency pools method, fill lines 16a through 20 for each currency.
Line 22 includes the total from Schedule P, line 7. The instructions say lines 24a to 24d are entered as negative amounts and 24e and 24f as positive. Line 25 also goes on Form 1120-F, Section II, line 18.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1120-F. It is not filed on its own.
The form asks for an attached statement for lines 3c, 24a, 24b, 24d and 24e, and for Form 8990 with line 24c.
The instructions say no interest expense allocation elections may be made on an amended return, and the choice of method is generally kept for a minimum 5-year period.
The form says the amount on line 25 may not exceed the total interest expense paid or accrued by the foreign corporation.
The instructions say line 24g goes to Form 1120-F, Section III, Part II, line 7b, line 23 to line 7c, and amounts also tie to Schedule M-3 (Form 1120-F), Part III.
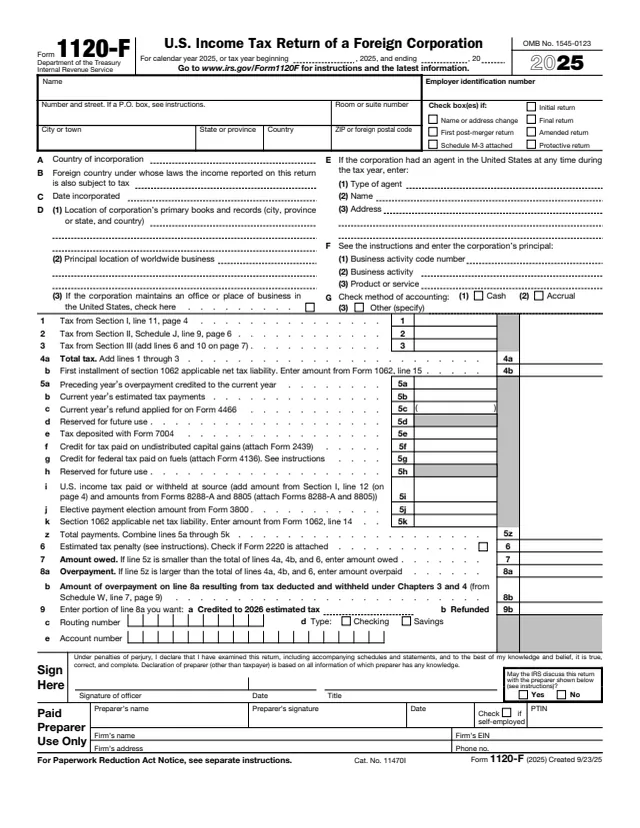
1120-F
527 fields, 9 pages
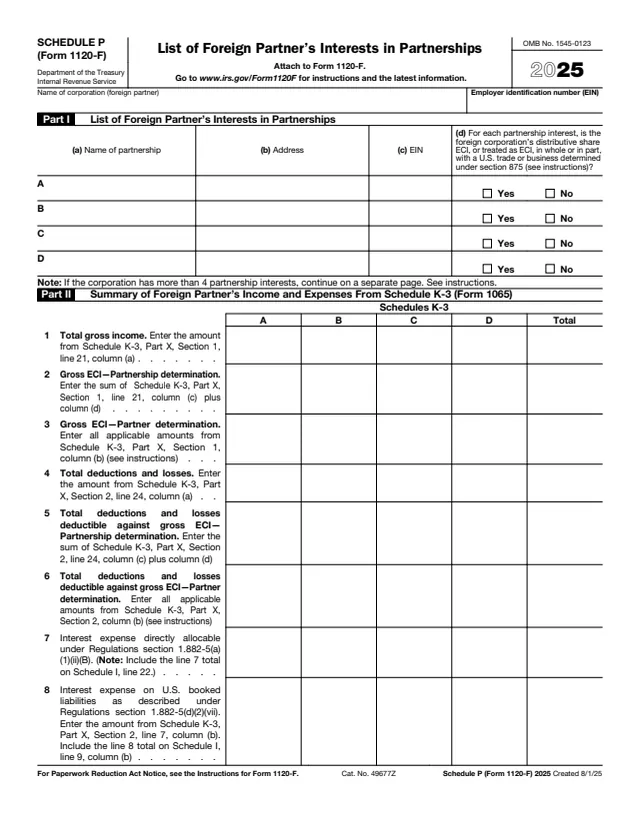
1120-F
173 fields, 3 pages
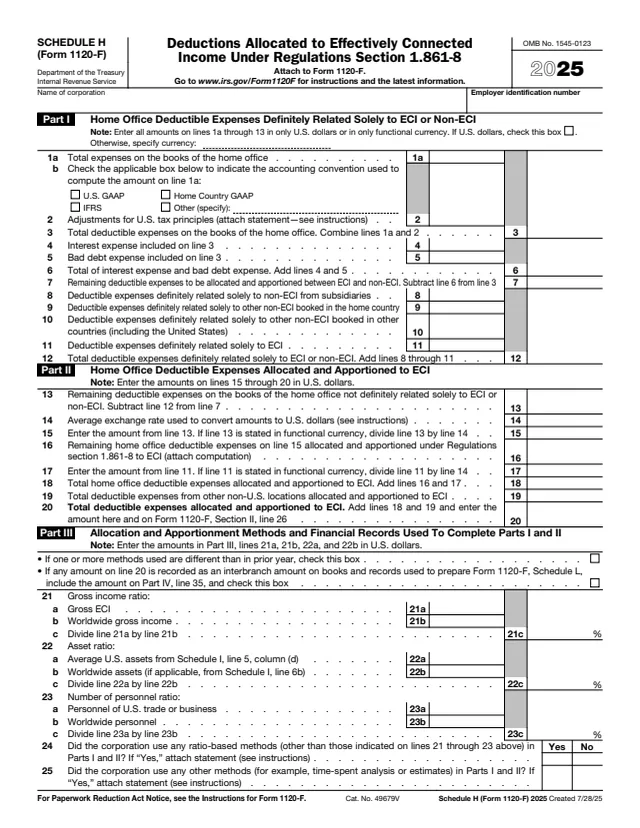
1120-F
77 fields, 2 pages
1120-F
439 fields, 4 pages
8990
134 fields, 3 pages
8833
41 fields, 5 pages
The instructions say all foreign corporations that have interest expense allocable to ECI under section 882(c) complete Schedule I, whether the allocated amount is deductible this year, deferred or permanently disallowed. It is a corporate schedule, not a form for individuals.
No tool matches that search.
The amount of interest expense allocable to ECI and the deductible amount of that allocation for the tax year under section 882(c) and Regulations section 1.882-5.
The instructions say all foreign corporations that have interest expense allocable to ECI under section 882(c). It is attached to the corporation's Form 1120-F.
The adjusted U.S. booked liabilities method on lines 10 through 15 and the separate currency pools method on lines 16a through 20. The instructions say they cannot both apply in the same year.
The fixed ratio. The form says 95% for a foreign bank as defined in Regulations section 1.882-5(c)(4), and 50% for a corporation that is not a foreign bank or an insurance company.
The form says to enter it on Form 1120-F, Section II, line 18.
No. The instructions say no interest expense allocation elections may be made on an amended return under Regulations section 1.882-5(a)(7).