Part I: partnership list
Name, address and EIN of each partnership, rows A to D, and column (d) asking whether the share is ECI with a U.S. trade or business under section 875.
1120-F
List of Foreign Partner's Interests in Partnerships
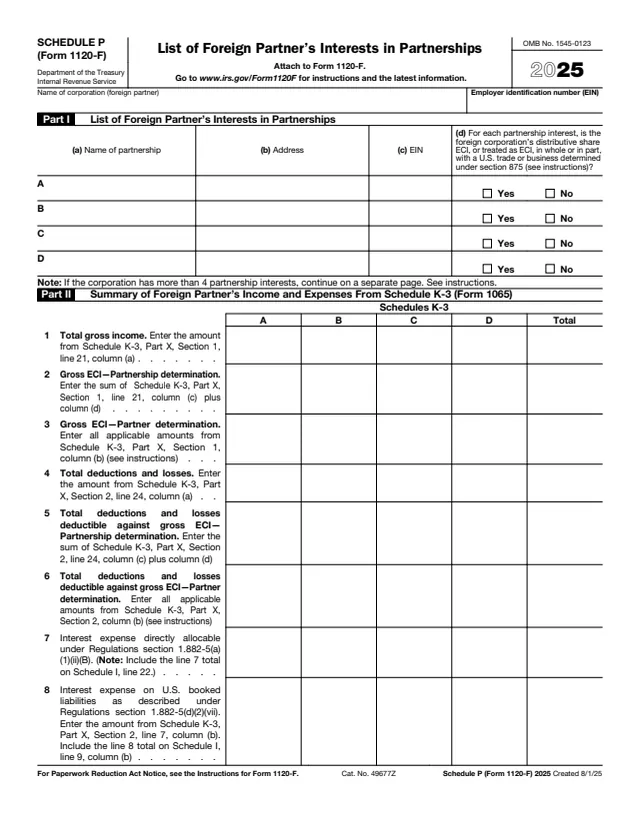
Schedule P (Form 1120-F) is the 2025 schedule a foreign corporation uses to identify and reconcile its directly held partnership interests with its distributive shares of partnership effectively connected income (ECI), and its effectively connected outside tax basis in each interest.
The instructions say it is also used to report a foreign corporate partner's transfer of an interest in a partnership, and the gain or loss on the transfer, when the partnership is engaged in a trade or business within the United States or holds U.S. real property interests (sections 864(c)(8) and 897(g)). Most amounts come from the Schedule K-3 (Form 1065) the partnership issues, and several totals carry over to Schedule I (Form 1120-F).
The form says to attach it to Form 1120-F. You can fill out Schedule P free in your browser on this page and download it without an account.
Name, address and EIN of each partnership, rows A to D, and column (d) asking whether the share is ECI with a U.S. trade or business under section 875.
Summary of the partner's income and expenses from Schedule K-3 (Form 1065), Part X, including directly allocable interest and interest on U.S. booked liabilities.
Average outside basis under Regulations sections 1.882-5(b) and 1.884-1(d)(3), the part allocable to ECI, and the income or asset method box.
Each partnership interest transferred during the tax year, with the Part I row letter, percentage or units transferred, date acquired and date transferred.
Gain or loss on each transfer: amount realized, outside basis, ordinary and capital pieces, recognized effectively connected gain or loss, and section 897(g) gain or loss.
List each directly owned partnership interest with ECI. The instructions say not to include disregarded entities, and to check Yes in column (d) when the corporation is engaged in a U.S. business through the partnership's activities.
Copy the amounts from Schedule K-3 (Form 1065), Part X. The form says to include the line 7 total on Schedule I, line 22, and the line 8 total on Schedule I, line 9, column (b).
Enter the average section 705 outside basis, adjust it for liabilities on lines 10a and 10b, and carry line 13 to Schedule I, line 5, column (b). On line 14 check the income or asset method.
Use a separate line for each interest transferred, and for each acquisition date. The instructions say to enter -0- when a distribution leaves the ownership interest unchanged.
Enter the amount realized and outside basis, then lines 4, 6, 7 and 10 from Schedule K-3 (Form 1065), Part XIII. If no Part XIII arrived, the instructions say to contact the partnership.
The instructions say line 8 goes to Form 4797, Part II, line 10, and line 9 goes to Form 8949 with "From Schedule P (Form 1120-F)" in column (a).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach it to Form 1120-F. The instructions point to the Instructions for Form 1120-F for the time, place, and manner of filing the return.
The instructions say to report extra interests on attached sheets in the same size and format, and to include them in the Total column.
The form says line 7 goes to Schedule I (Form 1120-F), line 22; line 8 to line 9, column (b); part of line 11 to line 8, column (b); and line 13 generally to line 5, column (b).
If a treaty-based position applies to any amount in Part V, the instructions say to attach Form 8833 to Form 1120-F with a detailed explanation.
The instructions say that, unless an exception applies, the transferee withholds tax on the amount realized and reports it on Form 8288-A.
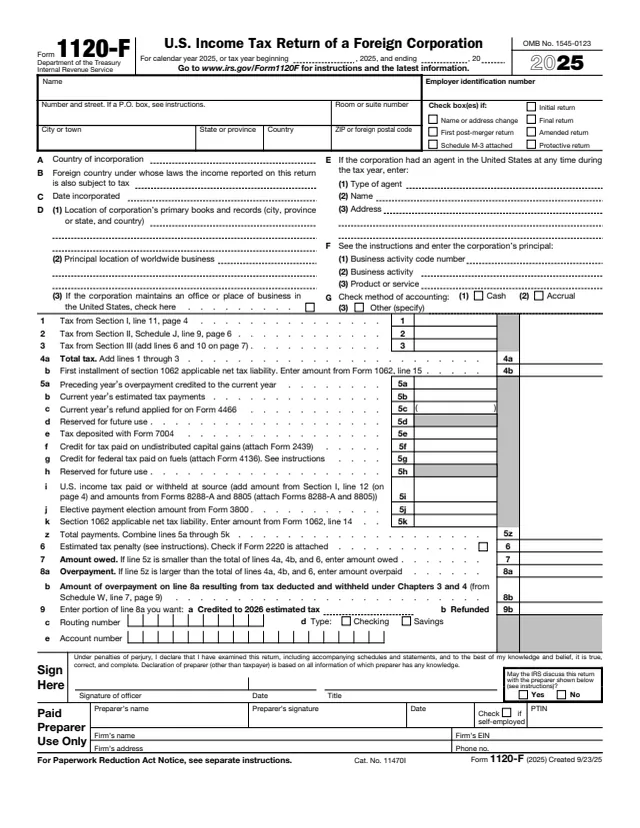
1120-F
527 fields, 9 pages
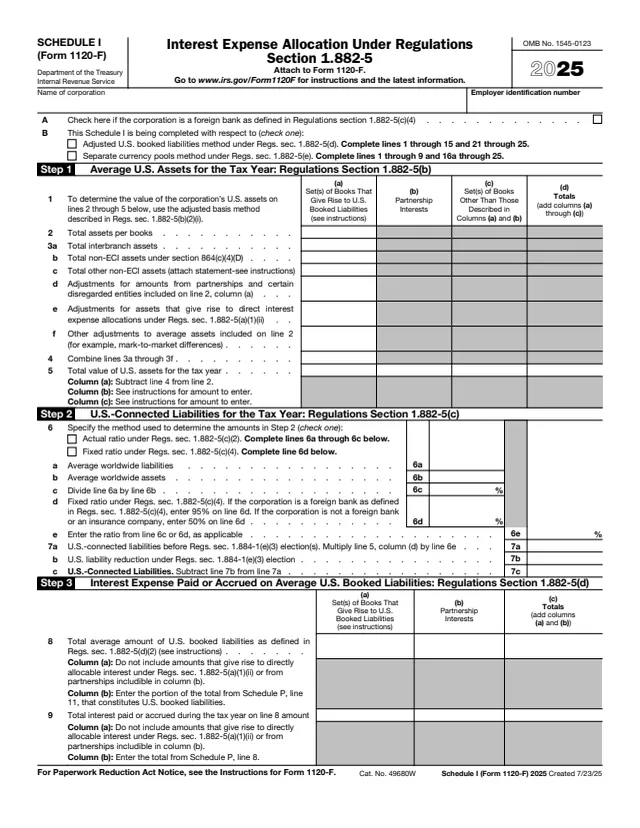
1120-F
113 fields, 3 pages
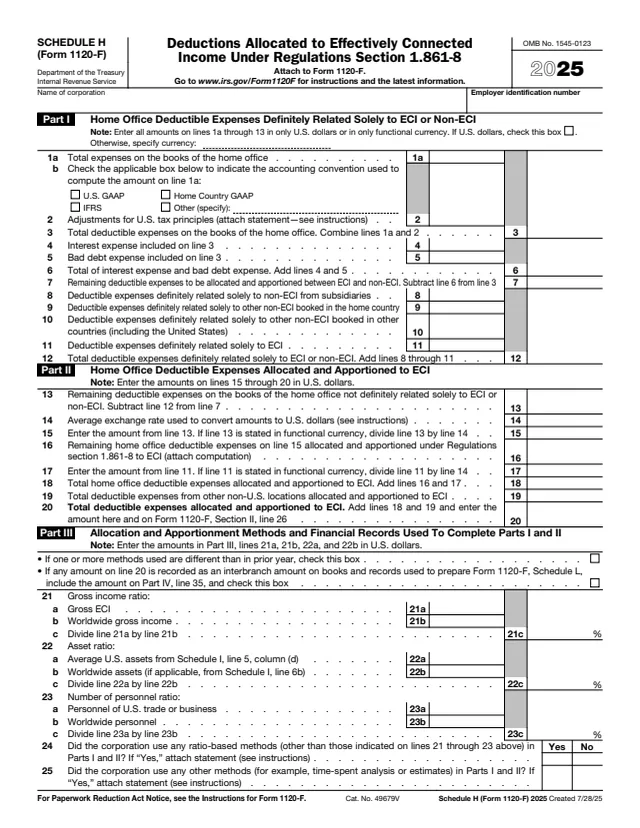
1120-F
77 fields, 2 pages
8949
202 fields, 2 pages
4797
182 fields, 2 pages
8288-A
60 fields, 5 pages
The instructions say a foreign corporation engaged directly or indirectly in a trade or business within the United States completes Schedule P for its directly owned partnership interests that have gross ECI, or expenses allocable to gross ECI, reported on Schedule K-3 (Form 1065). It is a corporate schedule, not a form for individuals.
No tool matches that search.
To identify and reconcile a foreign corporation's directly held partnership interests with its shares of partnership ECI and outside basis, and to report transfers of certain partnership interests.
Mostly from the Schedule K-3 (Form 1065) the partnership issues: Part X for Parts II and III, and Part XIII for Part V.
The form says to continue on a separate page. The instructions say to use the same size and format and to include the extra interests in the Total column.
The instructions say not to report indirectly owned lower-tier partnership interests unless the corporation also owns a direct interest in that partnership.
Only if the foreign corporation transferred a partnership interest subject to section 864(c)(8) or 897(g), according to the instructions.
The instructions say the corporation will need to contact the partnership to get the information for lines 4, 6, 7 and 10 of Part V.