Part I, lines 1 to 3
Whether a certified audited or other non-tax-basis income statement was prepared, the income statement period, and whether the income statement was restated for that period or the five periods before it.
1120-S Sch. M-3
Net Income (Loss) Reconciliation for S Corporations With Total Assets of $10 Million or More
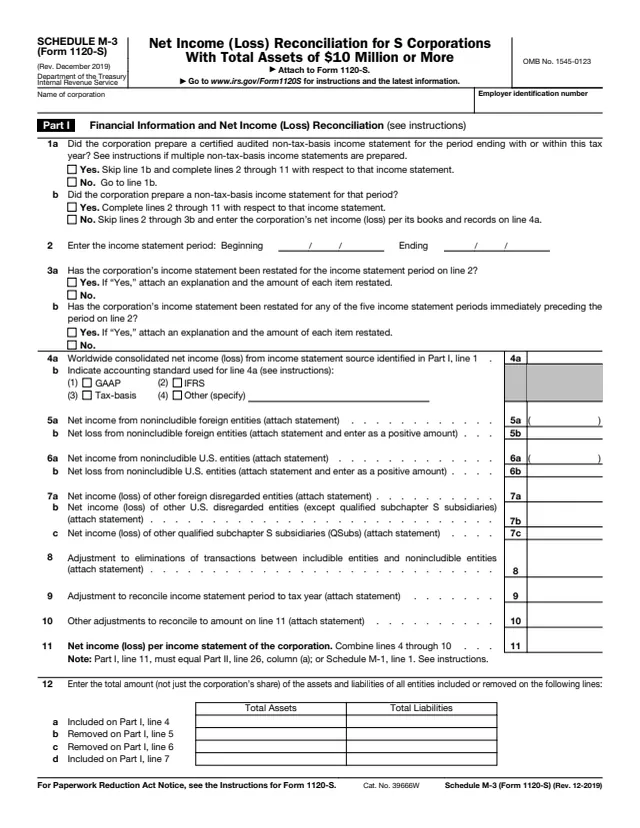
Schedule M-3 (Form 1120-S) is the Net Income (Loss) Reconciliation for S Corporations With Total Assets of $10 Million or More. The instructions say Part I asks questions about the corporation's financial statements and reconciles worldwide net income (loss) to income (loss) per the income statement of the corporation, and Parts II and III reconcile that amount to total income (loss) on Form 1120-S, Schedule K, line 18.
The S corporation completes it and attaches it to Form 1120-S. The instructions say a corporation filing Form 1120-S that reports total assets on Schedule L of $10 million or more at the end of its tax year files it, and a corporation that is not required to may file it voluntarily instead of Schedule M-1.
The current revision is dated December 2019, and the instructions say they will no longer be updated annually unless necessary. You can fill it out free in your browser on this page and download the result without an account.
Whether a certified audited or other non-tax-basis income statement was prepared, the income statement period, and whether the income statement was restated for that period or the five periods before it.
Worldwide consolidated net income (loss) and the accounting standard used, removals for nonincludible foreign and U.S. entities, disregarded entities and QSubs, adjustments, and net income (loss) per income statement on line 11.
Total assets and total liabilities of all entities included or removed on Part I, lines 4, 5, 6 and 7, not just the corporation's share.
Lines 1 to 26 for items such as equity method income, foreign dividends, partnership income, interest income, cost of goods sold, section 481(a) adjustments and gains or losses on asset dispositions.
Lines 1 to 32 for items such as income tax expense, equity-based compensation, meals and entertainment, fines and penalties, charitable contributions, goodwill, depreciation, bad debt and interest expense.
Column (a) is the amount per income statement, (b) the temporary difference, (c) the permanent difference and (d) the amount per tax return.
Check Yes on line 1a if a certified audited non-tax-basis income statement was prepared; otherwise answer line 1b. If none was prepared, the form says to skip lines 2 through 3b and enter net income (loss) per books and records on line 4a.
Report worldwide consolidated net income (loss) from the income statement source identified on line 1, and check the accounting standard used: GAAP, IFRS, tax-basis or other.
Remove nonincludible foreign and U.S. entities on lines 5 and 6, include disregarded entities and QSubs on line 7, and adjust on lines 8 to 10. The form says line 11 equals Part II, line 26, column (a), or Schedule M-1, line 1.
The instructions say line 12 is completed by all corporations that file Schedule M-3, and every asset and liability amount on lines 12a to 12d is reported as a positive number.
Report the income statement amount in column (a) and the tax return amount in column (d), and split any difference into temporary (b) and permanent (c). If it cannot be determined whether a difference will reverse, the instructions say to use column (c).
Part III, line 32 carries to Part II, line 24. The form says Part II, line 26, column (a) equals Part I, line 11, and column (d) equals Form 1120-S, Schedule K, line 18.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says "Attach to Form 1120-S." The box on Form 1120-S, item C is checked to show Schedule M-3 is attached.
The instructions say a corporation filing Schedule M-3 files Form 1120-S and all attachments at Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0013.
Lines marked attach statement need a supporting statement, and the instructions ask for a detailed description of each item and adjustment on Part II, line 22 and Part III, line 31.
Part II, line 15 comes from Form 8916-A, line 8. The instructions say a corporation under $50 million in assets, or a voluntary filer, is not required to file Form 8916-A but may do so.
The instructions say amounts from a reportable transaction, such as one disclosed on Form 8886, are reported on Part II, line 10.

1120-S
390 fields, 5 pages
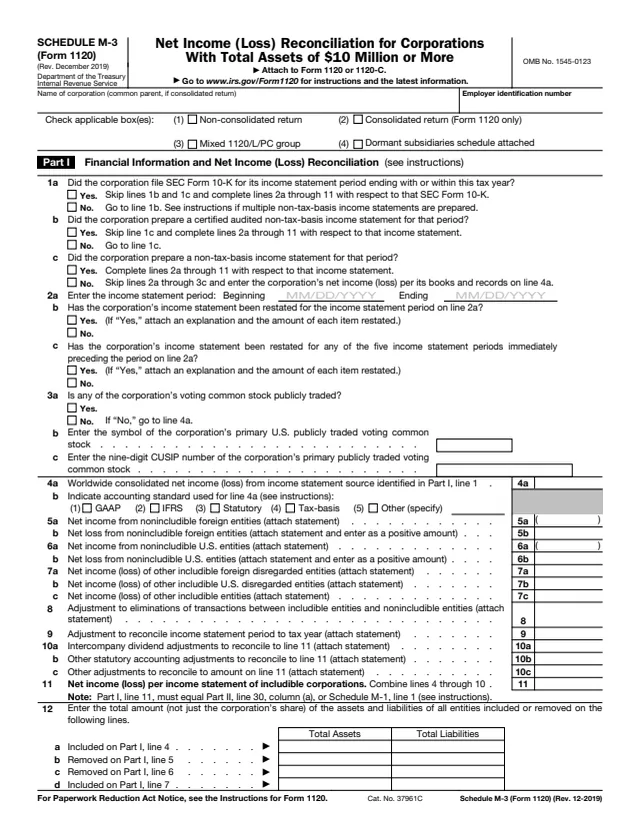
1120 Sch. M-3
380 fields, 3 pages
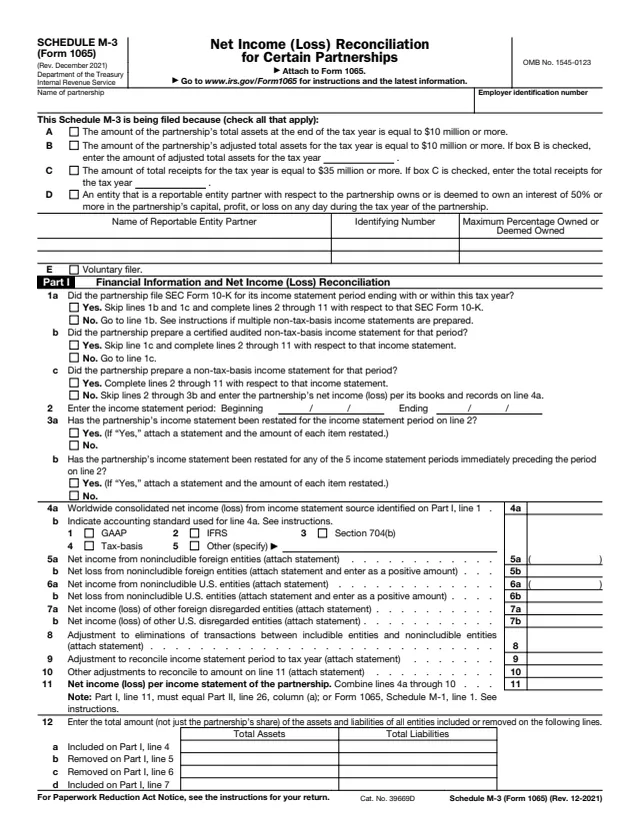
1065 Sch. M-3
316 fields, 3 pages
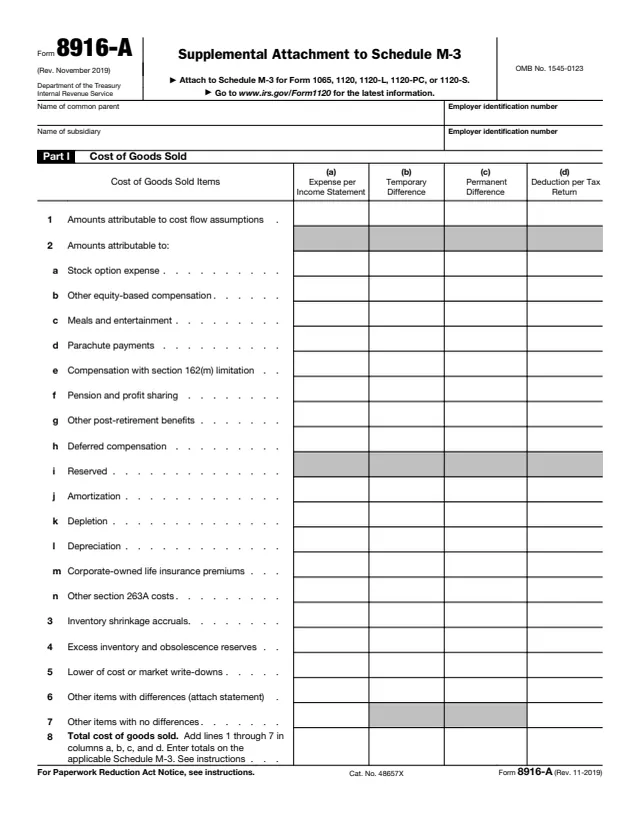
8916-A
140 fields, 4 pages
8886
98 fields, 2 pages
1120-S
53 fields, 2 pages
An S corporation completes it and attaches it to its Form 1120-S. It is a business schedule, not one an individual files.
No tool matches that search.
No. The instructions say it is filed by a corporation reporting total assets of $10 million or more on Schedule L at the end of the tax year. Others file Schedule M-1 or may file Schedule M-3 voluntarily.
The instructions say a required filer with less than $50 million in assets, or a voluntary filer, may complete Part I and then Schedule M-1. Line 1 of Schedule M-1 then equals Part I, line 11.
Column (b) holds temporary differences and column (c) permanent ones. The instructions say that under GAAP a temporary difference generally affects a deferred tax asset or liability.
The form says to check No on lines 1a and 1b, skip lines 2 through 3b, and enter net income (loss) per the corporation's books and records on line 4a.
The instructions say that, due to the generally unchanging nature of Schedule M-3 (Form 1120-S), they will no longer be updated annually unless necessary.
The form says Part I, line 11 equals Part II, line 26, column (a), and column (d) of that line equals Form 1120-S, Schedule K, line 18.