Part I: general information
The trust's name and EIN, the trustee or designated filer's name, number and address, the surviving spouse's name, TIN and status, and the decedent's name, SSN and date of death.
706-QDT
U.S. Estate Tax Return for Qualified Domestic Trusts
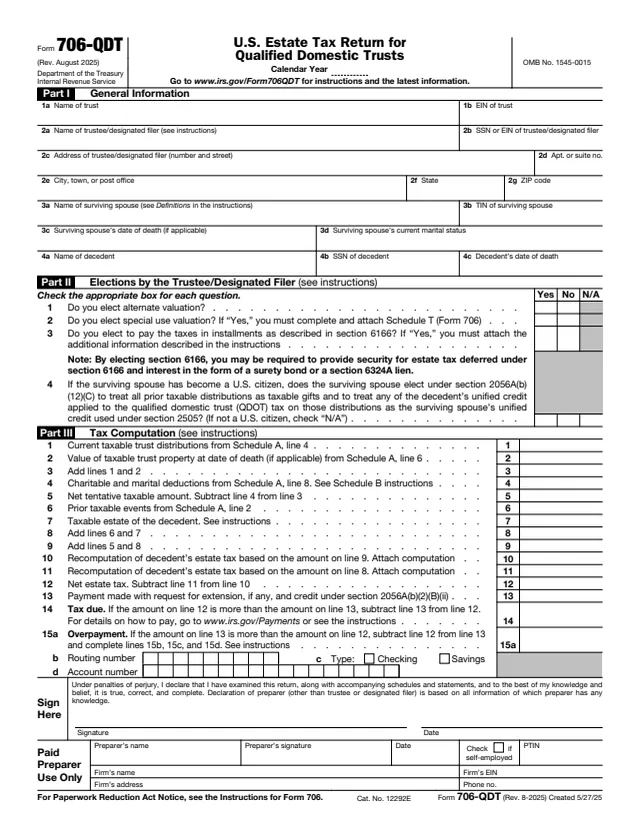
Form 706-QDT is the estate tax return for a qualified domestic trust (QDOT). The About page says the trustee or designated filer uses it to figure and report the estate tax due on certain distributions from the QDOT, the value of the property remaining in the QDOT on the date of the surviving spouse's death, and the corpus portion of certain annuity payments.
The instructions say the QDOT rules apply only in those situations where a decedent's surviving spouse is not a U.S. citizen. They also say the form can be used to notify the IRS that the trust is exempt from future filing because the surviving spouse has become a U.S. citizen and meets the line 4 requirements.
The return is filed by the trust's trustee or a designated filer, not by the surviving spouse. You can fill out the PDF free in your browser on this page and download the result without an account.
The trust's name and EIN, the trustee or designated filer's name, number and address, the surviving spouse's name, TIN and status, and the decedent's name, SSN and date of death.
Four Yes, No or N/A questions: alternate valuation, special use valuation with Schedule T (Form 706), installment payments under section 6166, and the spousal election under section 2056A(b)(12)(C).
Lines 1 to 15 bring in taxable distributions, property at death, deductions and prior taxable events, recompute the decedent's estate tax, and show the tax due or an overpayment with direct deposit fields.
A table that summarizes prior and current year taxable distributions, property remaining in the QDOTs at the surviving spouse's death, and marital and charitable deductions for multiple trusts.
Completed by the trustee for each trust: general information, taxable distributions with any hardship exemption claimed, and taxable property in the trust at the surviving spouse's death.
Marital and charitable deductions for property that remained in the QDOT at the surviving spouse's death and was includible in the surviving spouse's gross estate.
Enter the trust's name and EIN. The instructions say all trusts filing Form 706-QDT have an EIN, and to write "Applied for" on line 1b if it has not arrived. Line 4a is the decedent on whose estate tax return the QDOT election was made.
Answer each election question. The instructions say alternate valuation, once made, is irrevocable, and a special use valuation election needs Schedule T (Form 706) and its attachments filed with this return.
Report each current year distribution of corpus with its date, description and value. The instructions say value is fair market value on the date of distribution. Enter any hardship exemption in column (f).
List all property remaining in the QDOT at the surviving spouse's death, including corpus and undistributed income. The instructions say to make no entry in Parts IV and V unless Part III has one.
Carry the Schedule B totals to Schedule A, then to Part III. For lines 10 and 11, the instructions say to use the same revision of Form 706 or Form 706-NA the executor filed for the decedent's estate.
The trustee or designated filer signs under penalties of perjury. If the trustee files and more than one trustee is listed, the instructions say all listed trustees verify the return.
The instructions set an order: Part I, Part II, Schedule B (or the Schedules B from each trustee), Schedule A, then Part III.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say the return for distributions is generally due on or after January 1 but not later than April 15 of the year following any calendar year with a taxable event or a hardship distribution.
A return filed because of the surviving spouse's death is due within 9 months following the date of death. If the trust ceases to qualify as a QDOT, it is due within 9 months of that date.
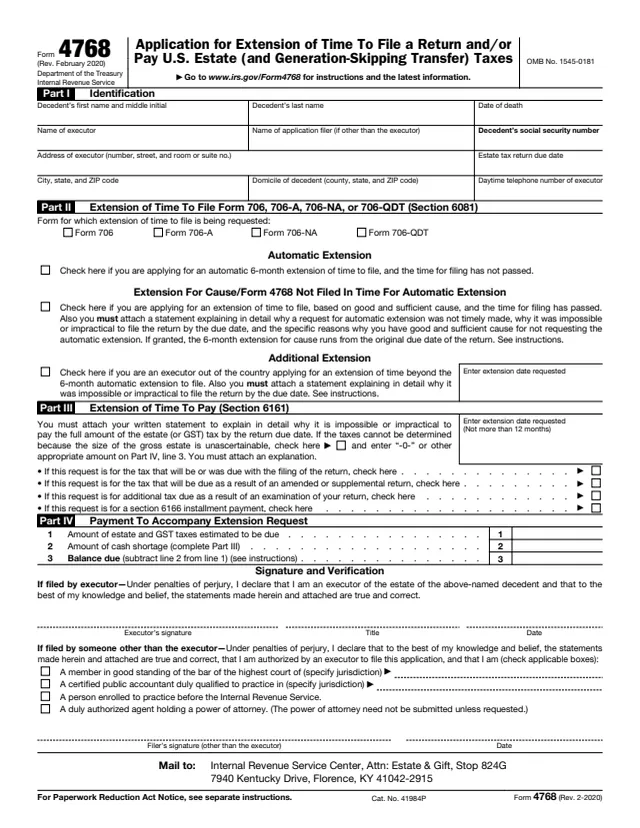
Form 4768 applies for an automatic 6-month extension of time to file. Check the "Form 706-QDT" box in Part II of Form 4768. The instructions say an extension of time to file does not extend the time to pay.
Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999. With a private delivery service: Internal Revenue Submission Processing Center, 333 W. Pershing, Kansas City, MO 64108.
A copy of the trust instrument goes with the first Form 706-QDT filed for the trust. A return filed due to the surviving spouse's death includes a copy of the death certificate.
Make the check payable to "United States Treasury" and write the surviving spouse's SSN (or ITIN) and "Form 706-QDT" on it. The instructions also list EFTPS and same-day wire.

706
316 fields, 5 pages
706-NA
259 fields, 3 pages
706-A
464 fields, 5 pages
706 Sch. T
858 fields, 8 pages
4768
35 fields, 1 page

2848
92 fields, 2 pages
The instructions say either the trustee or the designated filer files Form 706-QDT for any year in which the QDOT has a taxable event or makes a distribution on account of hardship.
No tool matches that search.
The instructions describe a QDOT as a trust that qualifies for the estate tax marital deduction under section 2056, requires at least one trustee to be a U.S. citizen or domestic corporation, and for which the executor made the QDOT election on the decedent's estate tax return.
The instructions list distributions of income to the surviving spouse and distributions on account of hardship as exceptions to the taxable distributions made before the spouse's death.
If the decedent's executor designated a filer, that designated filer files one return for all of the QDOTs, using a Schedule B from each trustee.
The instructions say the QDOT tax will not apply to later distributions if certain conditions are met, and to file a final Form 706-QDT to notify the IRS. Line 4 holds an election for spouses who do not meet those conditions.
No. The instructions say an extension of time to file does not extend the time to pay the tax.
The instructions say to file another Form 706-QDT with "Supplemental Information" across the top of page 1, a statement of what changed and a copy of the original return.