Header and Part I: type of election
The decedent's name and Social Security number as they appear on Form 706, then two boxes: line 1 for a protective election and line 2 for a regular election.
706 Sch. T
Section 2032A Property Valuation
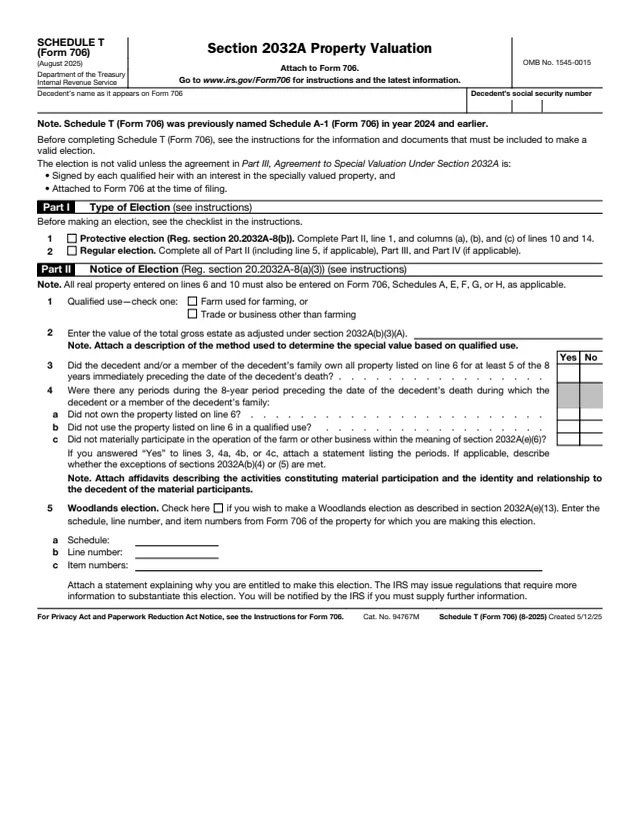
Schedule T (Form 706) is the schedule an estate attaches to Form 706 to support the election under section 2032A. The About page says it is used "to make an election to value certain farm and closely held business property at special value." The Instructions for Form 706 say the election itself is made by checking "Yes" on Form 706, Part III, line 2, and Schedule T reports the additional information that supports it.
The form notes that Schedule T (Form 706) was previously named Schedule A-1 (Form 706) in year 2024 and earlier. It says the election is not valid unless the agreement in Part III is signed by each qualified heir with an interest in the specially valued property and attached to Form 706 at the time of filing.
For decedents dying in 2026, the instructions say the total value of property valued under section 2032A may not be decreased from fair market value by more than $1,460,000. You can fill out the schedule free in your browser on this page and download the result without an account.
The decedent's name and Social Security number as they appear on Form 706, then two boxes: line 1 for a protective election and line 2 for a regular election.
The qualified use (farm or a trade or business other than farming), the adjusted value of the gross estate, Yes/No questions on ownership, use and material participation in the 8 years before death, and the woodlands election.
Three tables: real property to be specially valued (line 6), real property in a qualified use but not specially valued (line 10), and personal property in a qualified use (line 14), each with totals.
Name, address, identifying number, relationship to the decedent, fair market value and special-use value for each party who received any interest in the specially valued property.
The agreement under section 2032A, the heirs' consent to personal liability under section 2032A(c), the designation of an agent and the signatures of all qualified heirs and other interested parties.
Extra lines for the names and signatures of qualified heirs and other interested parties when Part III runs out of space.
Enter the decedent's name and SSN, then check line 1 or line 2 in Part I. The form says a protective election completes Part II, line 1, and columns (a), (b) and (c) of lines 10 and 14. A regular election completes all of Part II, Part III and Part IV if applicable.
Check one qualified use, enter the adjusted value of the gross estate and answer lines 3 and 4. The form asks for a description of the valuation method, a statement listing any periods for a Yes answer, and affidavits on material participation.
Identify each item on lines 6, 10 and 14 by its Form 706 schedule, line number and item number. The form says real property on lines 6 and 10 also goes on Form 706, Schedules A, E, F, G or H, and asks for legal descriptions and copies of appraisals.
List every party who received any interest in the specially valued property. The form asks for a computation of the GST tax savings for each skip person listed, and the instructions explain how to figure it with Schedule R (Form 706) worksheets.
In Part III, list all qualified heirs and other parties, name the agent, and collect a signature from every qualified heir and other interested party. Use Part IV if more space is needed.
The Instructions for Form 706 include a Checklist for Section 2032A Election covering the notice of election and the agreement. They say the checklist is for your use only and is not filed with the return.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Attach Schedule T to Form 706. The instructions give the Form 706 address as Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999. The About page points to Filing estate and gift tax returns for the latest address.
The instructions say Form 706 is filed within 9 months after the date of the decedent's death, and Form 4768 applies for an automatic 6-month extension of time to file. The election may be made on a late-filed return so long as it's the first return filed.
If the estate qualifies based on values as finally determined, the instructions say a supplemental Form 706 with a complete section 2032A election is filed within 60 days after the date of this determination.
The agreement says that after a disposition or cessation of qualified use, each qualified heir agrees to file Form 706-A and pay any additional estate and GST taxes due within 6 months.
The agreement says a lien will be created and recorded under section 6324B on the property for the adjusted tax differences defined in section 2032A(c)(2)(C).

706
316 fields, 5 pages
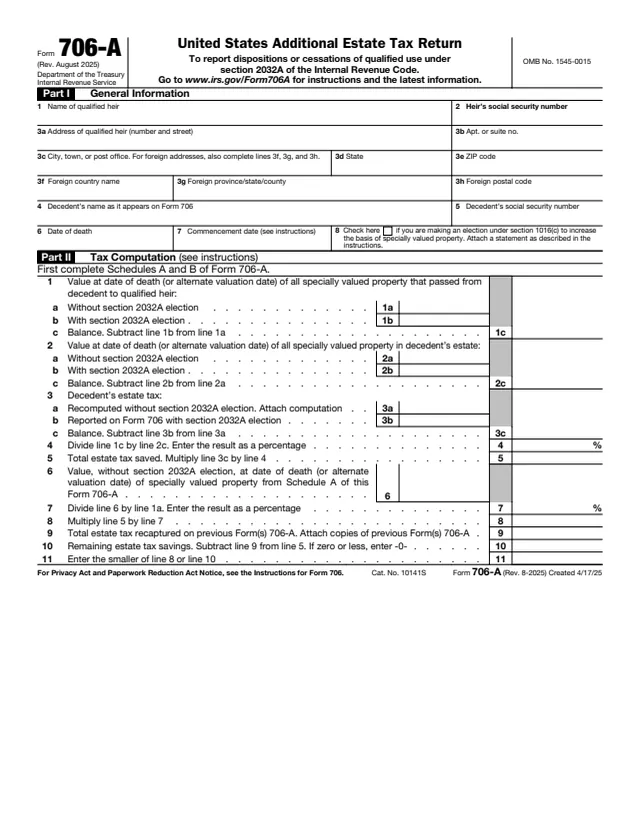
706-A
464 fields, 5 pages
706 Sch. A
223 fields, 2 pages
706 Sch. E
265 fields, 2 pages
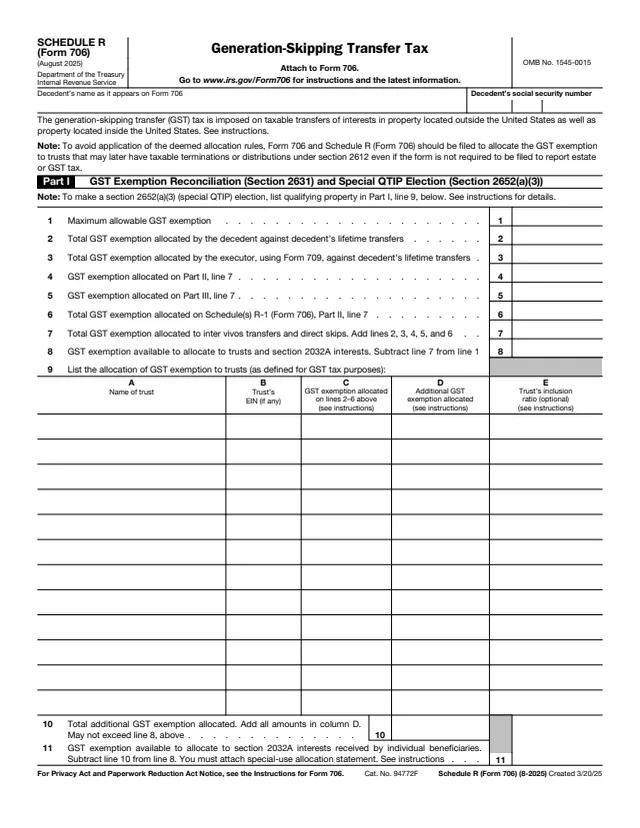
706 Sch. R
216 fields, 3 pages
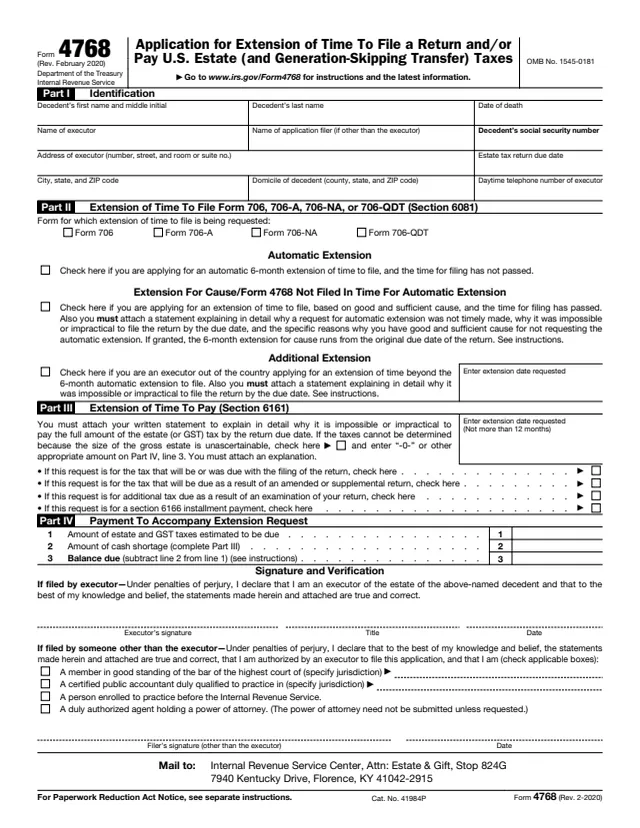
4768
35 fields, 1 page
The schedule is prepared for the estate and filed with the estate tax return. Several people sign it.
No tool matches that search.
The form says Schedule T (Form 706) was previously named Schedule A-1 (Form 706) in year 2024 and earlier. The instructions say the functionality of the schedule is the same.
Every qualified heir with an interest in the specially valued property and every other person with an interest in it signs Part III, along with the agent the parties designate.
The instructions describe it as an election whose use depends on final values meeting the section 2032A requirements. It completes only Part II, line 1, and columns (a), (b) and (c) of lines 10 and 14.
The instructions say the total value of property valued under section 2032A may not be decreased from fair market value by more than $1,460,000 for decedents dying in 2026.
No. The form says Schedule T (Form 706) must be filed with Form 706, and the agreement in Part III must be attached at the time of filing.
The agreement says each qualified heir agrees to file Form 706-A and pay any additional estate and GST taxes due within 6 months of the disposition or cessation of qualified use.