Part I, lines 1 to 4: trust and decedent
The name of the trust and its EIN, the decedent's name and SSN, and the Service Center where Form 706 was filed.
706 Sch. R-1
Generation-Skipping Transfer Tax
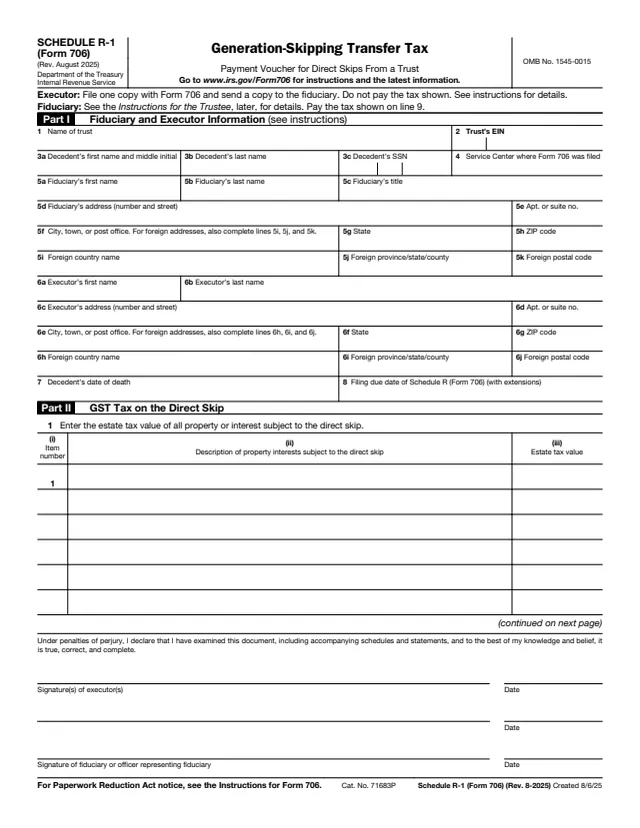
Schedule R-1 (Form 706), Generation-Skipping Transfer Tax, carries the subtitle "Payment Voucher for Direct Skips From a Trust." It is a schedule of Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return. The IRS describes it as the schedule used to figure the generation-skipping transfer (GST) tax that is payable by certain trusts that are includible in the gross estate.
The instructions say that under section 2603(a)(2), the GST tax on direct skips from a trust is paid by the trustee and not by the estate, and that Schedule R-1 serves as a notification from the executor to the trustee that a GST tax is due. The executor completes the schedule, files one copy with Form 706 and sends a copy to the fiduciary. The form tells the executor not to pay the tax shown, and tells the fiduciary to pay the tax shown on line 9.
You can fill out Schedule R-1 free in your browser on this page and download it without an account.
The name of the trust and its EIN, the decedent's name and SSN, and the Service Center where Form 706 was filed.
The fiduciary's name, title and address on lines 5a to 5k, and the executor's name and address on lines 6a to 6j, with foreign address fields.
The decedent's date of death and the filing due date of Schedule R (Form 706), with extensions.
A table with an item number, a description of each property interest subject to the direct skip and its estate tax value. Page 2 continues the table.
Totals of the estate tax value, charges borne by the property, the tentative maximum direct skip, the GST exemption allocated and the GST tax due from the fiduciary.
Signature lines for the executor or executors and for the fiduciary or an officer representing the fiduciary, each with a date, under penalties of perjury.
Enter the trust, decedent, fiduciary and executor details. On line 8, the instructions say to enter the due date of Form 706, and that copies go to the fiduciary before that date.
List each property interest subject to the direct skip with its estate tax value. The instructions say alternate or special-use values are used if those elections were made.
Add column (iii), add totals from any extra Part II pages, subtract estate taxes, state death taxes and other charges borne by the property, and enter the tentative maximum direct skip on line 6.
Enter the GST exemption allocated, no more than line 6. The instructions say an entry here constitutes a Notice of Allocation of the decedent's GST exemption to the trust.
Subtract line 7 from line 6, then divide line 8 by 3.5. If the property will not bear the GST tax, the instructions say to multiply line 9 by 40% (0.40).
The executor signs in the same manner as Form 706. The trustee signs the copy received from the executor before filing it.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions say to attach to Form 706 one copy of each Schedule R-1 prepared and to send a copy of each to the fiduciary.
The Instructions for the Trustee say to mail the signed copy to the Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999.
The form says all payments to the federal government are to be processed electronically and points to www.irs.gov/Payments. Payment can be made through EFTPS, which the form calls a free service of the Department of the Treasury.
The form says the GST tax is due and payable 9 months after the decedent's date of death, and interest is owed on any GST tax not paid by that date.
The form says the trustee has an automatic extension to file and pay by 2 months after the due date (with extensions) for filing the decedent's Schedule R. Interest is charged, but no penalties.
The form says EFTPS payments count as timely when completed no later than 8 p.m. Eastern time the day before the due date, and are scheduled in advance.

706
316 fields, 5 pages
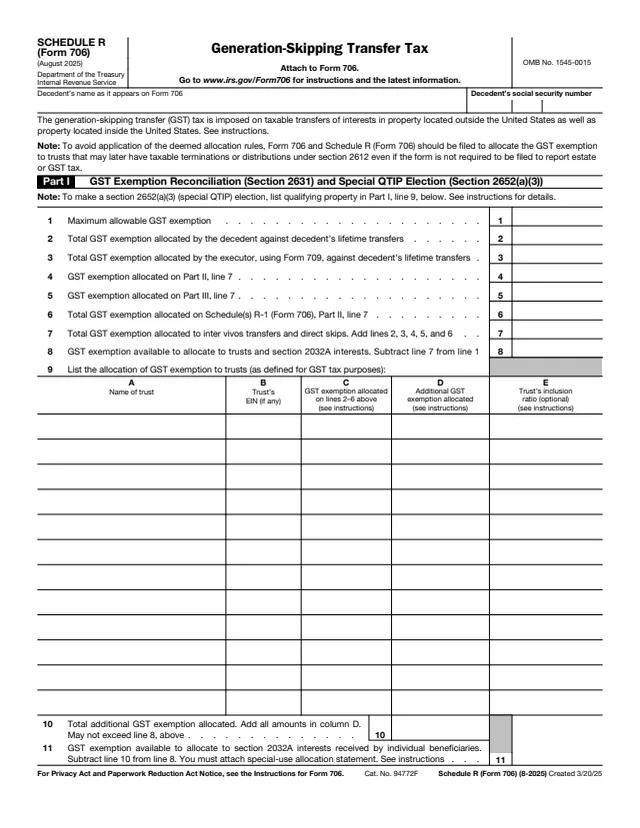
706 Sch. R
216 fields, 3 pages
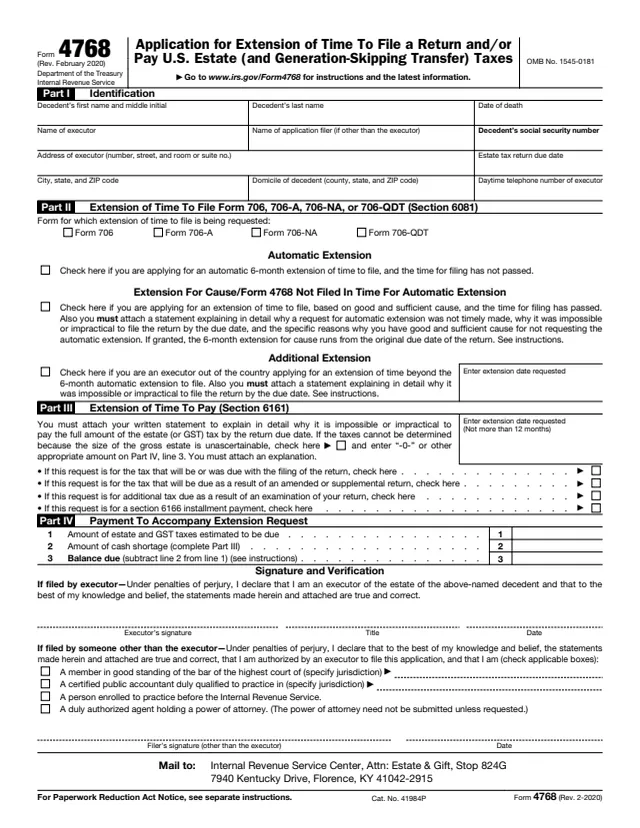
4768
35 fields, 1 page
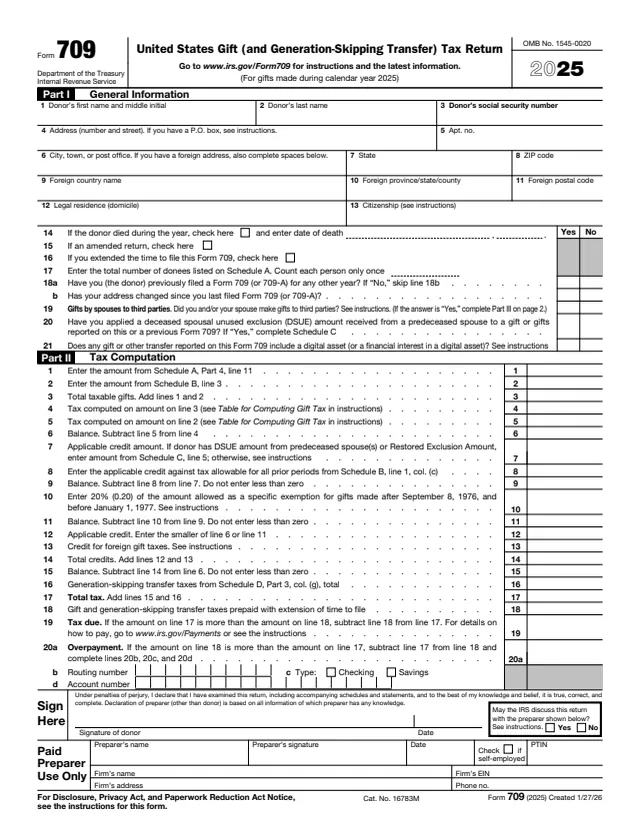
709
1,851 fields, 10 pages
706-NA
259 fields, 3 pages

2848
92 fields, 2 pages
The form is completed by the executor of a decedent's estate and then paid and signed by the trustee of the trust. It is not a form an individual files for their own taxes.
No tool matches that search.
The trustee of the trust. The instructions say that under section 2603(a)(2) the GST tax on direct skips from a trust is paid by the trustee and not by the estate, and the form tells the executor not to pay the tax shown.
The IRS says Schedule R figures the GST tax payable by the estate, and Schedule R-1 figures the GST tax payable by certain trusts that are includible in the gross estate.
The form says to divide line 8 by 3.5. The instructions say that if the property interests on line 2 will not bear the GST tax, line 9 is multiplied by 40% (0.40).
The Instructions for the Trustee say to mail the signed copy to the Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999, and to keep a second copy for the trustee's records.
The form says 9 months after the decedent's date of death, with an automatic extension to 2 months after the due date (with extensions) for filing the decedent's Schedule R. Interest applies under the extension, but no penalties.
Yes. The instructions say an entry on line 7 constitutes a Notice of Allocation of the decedent's GST exemption to the trust. Any additional allocation is made on Schedule R (Form 706), Part I.