Header
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
706 Sch. R
Generation-Skipping Transfer Tax
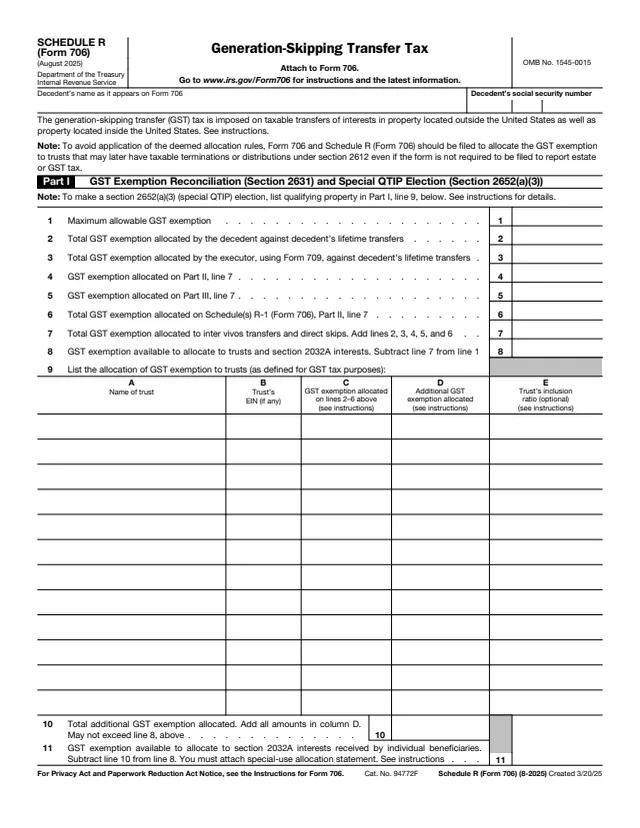
Schedule R (Form 706), Generation-Skipping Transfer Tax, is a schedule of Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return. The IRS says it is used to figure the generation-skipping transfer (GST) tax that is payable by the estate. The form says "Attach to Form 706."
The instructions say the GST tax reported on Form 706 is imposed only on direct skips occurring at death: transfers subject to the estate tax, of an interest in property, to a skip person. Schedule R also reconciles the decedent's GST exemption in Part I, where the executor can allocate the remaining exemption to trusts. The instructions say that once made, the allocation is irrevocable.
You can fill out Schedule R free in your browser on this page and download it without an account.
The decedent's name as it appears on Form 706 and the decedent's Social Security number.
The maximum allowable GST exemption, the amounts already allocated to lifetime transfers and to direct skips, and the exemption still available to allocate to trusts and section 2032A interests.
A table of trusts with columns for the name, EIN, exemption already allocated, additional exemption allocated and an optional inclusion ratio, then totals and the amount left for section 2032A interests.
Direct skips where the property transferred bears the GST tax: skip person, property and estate tax value, then charges, exemption allocated and the tax on line 9, carried to Form 706.
The same layout for direct skips where the property transferred does not bear the GST tax. Line 9 multiplies line 8 by 40% (0.40) and goes to Part II, line 10.
The instructions say the first step is to find the property interests includible in the gross estate by completing Schedules A through I of Form 706, then to decide who the skip persons are.
The instructions say you will usually enter all direct skips on Part II. A transfer goes on Part III only if the will or trust instrument directs, by specific reference, that the GST tax is not paid from the transferred property.
List each skip person, the property interest and its estate tax value. The instructions say alternate or special-use values are used if those elections were made. Subtract taxes and charges borne by the property.
Enter the GST exemption allocated, no more than line 6. In Part II, divide line 8 by 3.5. In Part III, multiply line 8 by 40% (0.40) and carry it to Part II, line 10.
The instructions say to complete Parts II and III and Schedule R-1 (Form 706) before lines 4, 5 and 6. Line 8 is the exemption still available after line 7.
List each trust to receive exemption. The instructions say line 9 is a Notice of Allocation, column E is optional, and line 11 needs an attached special-use allocation statement.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Schedule R to Form 706. Part II, line 11 is entered on Form 706, Part II, line 19.
The instructions give Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999. The About page points to Filing estate and gift tax returns for the latest filing address.
The instructions say Form 706 is filed within 9 months after the date of the decedent's death. Form 4768 is used to apply for an automatic 6-month extension of time to file.
The instructions say the current GST exemption is $15,000,000 and give a table of earlier amounts by year of transfer.
The instructions say the allocation is irrevocable once made, and any exemption not allocated is allocated under the deemed allocation rules of section 2632(e).

706
316 fields, 5 pages
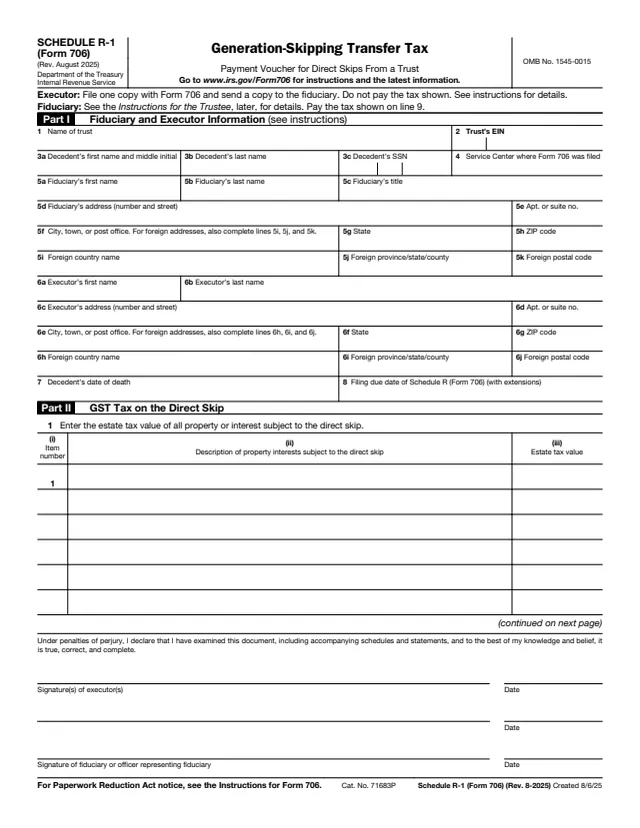
706 Sch. R-1
121 fields, 3 pages
709
1,851 fields, 10 pages
4768
35 fields, 1 page
706 Sch. T
858 fields, 8 pages
706-NA
259 fields, 3 pages
The executor of a decedent's estate completes Schedule R and attaches it to Form 706. It is not a form an individual files for their own taxes.
No tool matches that search.
The IRS says Schedule R figures the GST tax payable by the estate, and Schedule R-1 (Form 706) figures the GST tax payable by certain trusts that are includible in the gross estate.
The instructions say that for Form 706 a direct skip is a transfer that is subject to the estate tax, of an interest in property, and to a skip person. All three requirements have to be met.
The form says to divide line 8 by 3.5. In Part III, where the property does not bear the tax, the form says to multiply line 8 by 40% (0.40).
The instructions say that once made, the allocation is irrevocable. Exemption that is not allocated is allocated by the IRS under the deemed allocation rules.
No. The instructions say the executor is not required to make an entry in column E. A worksheet is provided to help figure a trust's inclusion ratio for the trustee.
The form notes that Form 706 and Schedule R should be filed to allocate the GST exemption to trusts that may later have taxable terminations or distributions, to avoid the deemed allocation rules.