Part I: Reporting Authority
Lines 1 to 7: issuer's name and EIN, address, the officer, employee or designated contact the IRS may call, and a telephone number. Line 5 is for IRS use only.
8038-GC
Information Return for Small Tax-Exempt Governmental Bond Issues, Leases, and Installment Sales
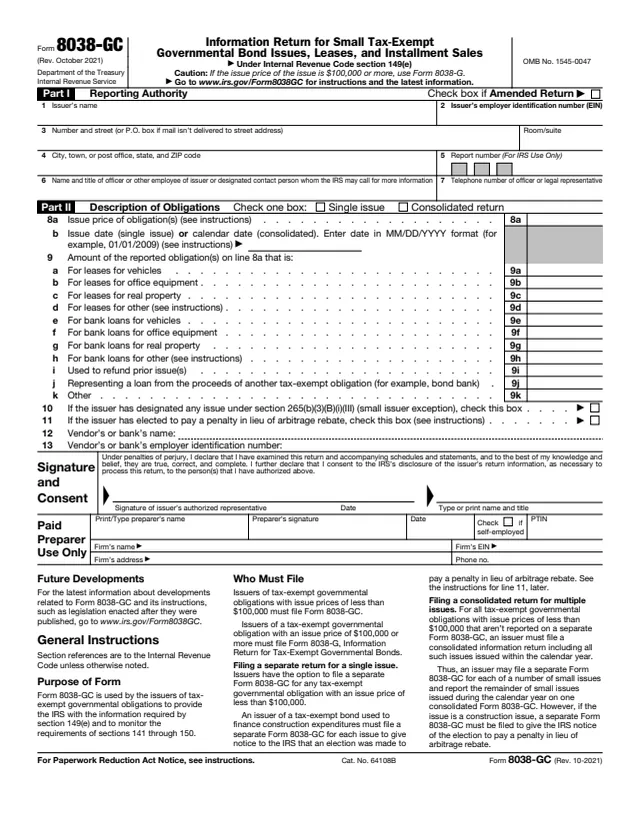
Form 8038-GC is the Information Return for Small Tax-Exempt Governmental Bond Issues, Leases, and Installment Sales, filed under Internal Revenue Code section 149(e). The instructions say issuers of tax-exempt governmental obligations use it to give the IRS the information required by section 149(e) and to monitor the requirements of sections 141 through 150.
The form says issuers of tax-exempt governmental obligations with issue prices of less than $100,000 file Form 8038-GC, and an issue price of $100,000 or more goes on Form 8038-G. An issuer can file one form per issue or one consolidated return for all small issues in a calendar year. Line 9 breaks the amount into leases and bank loans for vehicles, office equipment, real property and other items.
The filer is the issuer, which for a lease or installment sale is the lessee or purchaser. The instructions are printed on the form itself. This page hosts the October 2021 revision. You can fill out the PDF free in your browser on this page and download it without an account.
Lines 1 to 7: issuer's name and EIN, address, the officer, employee or designated contact the IRS may call, and a telephone number. Line 5 is for IRS use only.
A check box at the top of Part II says whether the form covers one issue or is a consolidated return for the calendar year.
The issue price of the obligations, and the issue date for a single issue or the calendar date for a consolidated return.
Leases and bank loans for vehicles, office equipment, real property and other items, amounts used to refund prior issues, loans from another tax-exempt obligation such as a bond bank, and other.
Boxes for the small issuer exception and the election to pay a penalty in lieu of arbitrage rebate, then the vendor's or bank's name and employer identification number.
The issuer's authorized representative signs and consents to disclosure of return information to any contact named on the form. A paid preparer area follows.
Enter the name of the entity issuing the obligations and its EIN. On lines 3 and 4 enter the issuer's address or that of the contact on line 6; the IRS uses it for all written communications about the return. Leave line 5 empty.
Check single issue or consolidated return. Line 8b takes the issue date for a single issue, or the first day of the calendar year for a consolidated return, in MM/DD/YYYY format.
Enter the issue price. The instructions say that when issued for cash it is generally the price at which a substantial amount of the obligations are sold to the public.
Lines 9a to 9d are for leases or installment purchases where property other than cash is exchanged, and 9e to 9h for bank loans. Lines 9d and 9h name the type of item or loan. Line 9k holds any amount not on lines 9a to 9j.
Check line 10 if any issue is designated under the small issuer exception, and line 11 if a construction issue made the irrevocable election to pay a penalty in lieu of arbitrage rebate. No penalty is paid with this form.
Enter the vendor's or bank's name and EIN, attaching a schedule if there are several. The issuer's authorized representative signs and writes a name and title.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to file Form 8038-GC and any attachments with the Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201.
On or before the 15th day of the 2nd calendar month after the close of the calendar quarter in which the issue is issued.
On or before February 15 of the calendar year following the year in which the issue is issued.
Relief may be granted under section 3 of Rev. Proc. 2002-48 if the late filing is not due to willful neglect. Write the request at the top and attach a letter saying why the form was late. Bond, lease or installment sale documents are not submitted.
If the address changes after the return is filed, the instructions point to Form 8822, Change of Address.
Arbitrage rebate and any penalty in lieu of arbitrage rebate are paid with Form 8038-T, not with Form 8038-GC.
8038-G
72 fields, 2 pages
8038
137 fields, 3 pages
8038-T
60 fields, 1 page
SS-4
89 fields, 2 pages
8822
25 fields, 2 pages
The form says issuers of tax-exempt governmental obligations with issue prices of less than $100,000 file it.
No tool matches that search.
The form says issuers of tax-exempt governmental obligations with issue prices of less than $100,000 file Form 8038-GC. An issue price of $100,000 or more goes on Form 8038-G.
Yes. The instructions say small issues not reported on a separate form go on one consolidated Form 8038-GC for the calendar year, due February 15 of the following year.
The instructions say a construction issue needs its own Form 8038-GC to give the IRS notice of the election to pay a penalty in lieu of arbitrage rebate.
The instructions give acquiring a police car, a fire truck or telephone equipment through a series of monthly payments as an example of a municipal lease reported on lines 9a to 9d.
They are printed on the form itself, starting on page 1 and running through page 3.
The form gives Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201.