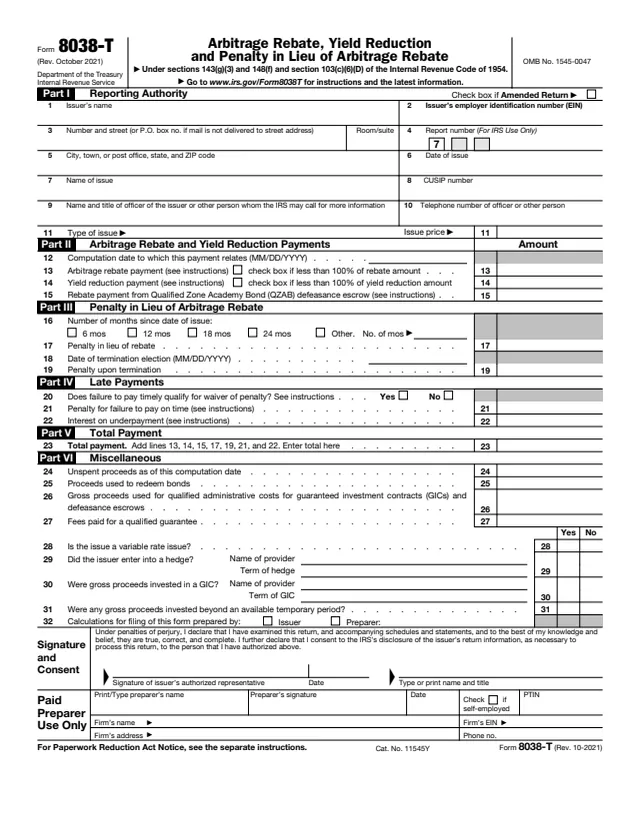
Part I: Reporting Authority, lines 1 to 11
Issuer's name, EIN and address, a report number for IRS use only, date of issue, name of issue, CUSIP number, a contact person and phone number, type of issue and issue price, and an amended return box.
8038-T
Arbitrage Rebate, Yield Reduction and Penalty in Lieu of Arbitrage Rebate
Form 8038-T, Arbitrage Rebate, Yield Reduction and Penalty in Lieu of Arbitrage Rebate, is filed by bond issuers, not by individuals. The About page explains that under section 148(f), interest on a state or local bond is not tax-exempt unless the issuer rebates to the United States arbitrage profits earned from investing bond proceeds in higher yielding nonpurpose investments, and that issuers of tax-exempt bonds and other bonds subject to section 148 use this form to make arbitrage rebate and related payments.
The instructions say the form is also used for payments of investment earnings on amounts in a defeasance escrow for Qualified Zone Academy Bonds (QZABs), and, for qualified mortgage bonds and qualified veterans' mortgage bonds, only when the issuer elected to pay the rebate to the United States. A separate Form 8038-T is used for each issue.
The form is signed by an authorized representative of the issuer and sent with a check or money order for the total payment. You can fill out Form 8038-T free in your browser on this page and download it without an account.
Issuer's name, EIN and address, a report number for IRS use only, date of issue, name of issue, CUSIP number, a contact person and phone number, type of issue and issue price, and an amended return box.
The computation date, the arbitrage rebate payment, the yield reduction payment, each with a box if less than 100%, and a rebate payment from a QZAB defeasance escrow.
Boxes for 6, 12, 18 or 24 months since the date of issue or another number of months, the penalty in lieu of rebate, the date of a termination election, and the penalty upon termination.
A yes or no question on whether a late payment qualifies for waiver of penalty, the penalty for failure to pay on time, interest on underpayment, and the total payment on line 23.
Unspent proceeds, proceeds used to redeem bonds, qualified administrative costs, guarantee fees, and questions on variable rates, hedges, GICs, investments beyond a temporary period, and who prepared the calculations.
Signature, date, and printed name and title of the issuer's authorized representative, with a Paid Preparer Use Only area.
Enter the same information as on the initial Form 8038, 8038-B, 8038-G, 8038-GC or 8038-TC for the issue, with any changes such as a new address. Leave line 4 blank; it is for IRS use only.
Enter the type of issue and total issue price from the initial filing. For bonds reported on Form 8038-GC, the instructions say to enter "small governmental bond".
Enter the computation date on line 12. The instructions say a rebate installment, added to the future value of earlier payments, equals at least 90% of the rebate amount, and a final payment brings it to 100%.
Complete Part III only if an election under section 148(f)(4)(C)(vii) was made on or before the issue date. Check the box for the months since issue, and file a separate Form 8038-T for each 6-month spending period.
For a waiver of penalty, attach an explanation of why the failure was not due to willful neglect. Line 22 interest uses the underpayment rate under section 6621, and late interest goes on line 22 only.
Add lines 13, 14, 15, 17, 19, 21 and 22 on line 23. Answer lines 24 to 32, then have an authorized representative of the issuer sign, date and print a name and title.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The instructions give Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0027. Certain IRS-designated private delivery services can be used; see IRS.gov/PDS.
Enclose a check or money order for the line 23 total made payable to the "United States Treasury", with the issuer's name, address, EIN, "Form 8038-T" and the date on it.
The instructions say rebate payments are due within 60 days after each computation date, computation dates occur at least once every 5 years, and the final payment is due within 60 days after the issue is discharged.
Penalty in lieu of arbitrage rebate payments are paid within 90 days of the end of the applicable spending period. Yield reduction payments are payable at the same time as arbitrage rebate payments.
The instructions say a late payment may cause bonds to be treated as never having been tax-exempt, unless the failure is not due to willful neglect and the issuer promptly pays a penalty of 50% (governmental and qualified 501(c)(3) bonds) or 100% of the unpaid rebate, plus interest.
Check the Amended Return box, give all the information from the original return plus the corrections, and attach an explanation of the reason for the amended return.
8038
137 fields, 3 pages
8038-G
72 fields, 2 pages
8038-GC
35 fields, 3 pages
8038-B
92 fields, 2 pages
8038-TC
225 fields, 5 pages
8038-R
40 fields, 3 pages
The instructions say issuers of tax-exempt bonds and any other bonds subject to section 148 file it. Line 1 is the governmental entity that issued the bonds.
No tool matches that search.
Issuers of tax-exempt bonds and other bonds subject to section 148. The instructions say line 1 is the governmental entity that issued the bonds, not the entity that benefits from the financing.
No. The instructions say to use a separate Form 8038-T for each issue, and a separate form for each 6-month spending period in Part III.
The instructions say within 60 days after each computation date, with the final payment due within 60 days after the issue is discharged.
The instructions say the penalty is generally waived if the rebate amount plus interest is paid within 180 days of discovery of the failure, and point to Rev. Proc. 2005-40.
The instructions point to Form 8038-R, Request for Recovery of Overpayments Under Arbitrage Rebate Provisions, and Regulations section 1.148-3(i).
An authorized representative of the issuer signs, dates and prints a name and title. A paid preparer also signs, while the instructions say an issuer's regular full-time employee who prepares it does not sign as preparer.