Header and columns A to D
The corporation's name and EIN, then four columns, one for each vessel or aircraft.
1120-F Sch. V
List of Vessels or Aircraft, Operators, and Owners
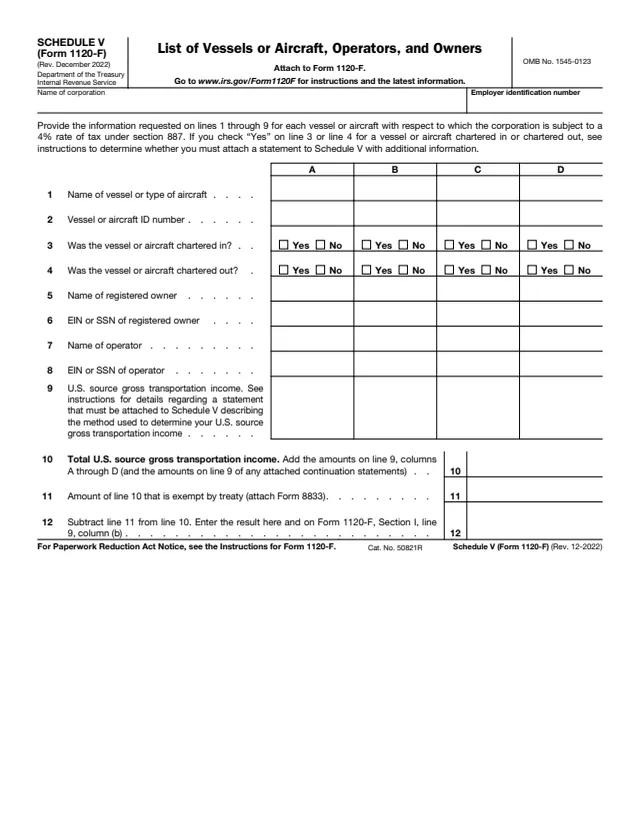
Schedule V (Form 1120-F), List of Vessels or Aircraft, Operators, and Owners, is filed by a foreign corporation. The IRS says it reports basic information for each vessel or aircraft with respect to which the corporation is subject to the 4% rate of tax on U.S. source gross transportation income (USSGTI) under section 887.
For each vessel or aircraft, the schedule asks for its name or type, its ID number, whether it was chartered in or out, the registered owner and the operator, and the USSGTI derived from it. The totals flow to Form 1120-F, Section I. The schedule is attached to Form 1120-F, U.S. Income Tax Return of a Foreign Corporation, and the instructions say all information must be in English and all amounts in U.S. dollars.
You can fill out the PDF free in your browser on this page and download it without an account.
The corporation's name and EIN, then four columns, one for each vessel or aircraft.
The name of the vessel or type of aircraft, and its ID number.
Yes or no boxes for whether the vessel or aircraft was chartered in and whether it was chartered out.
The registered owner's name and EIN or SSN, and the operator's name and EIN or SSN.
The U.S. source gross transportation income for each column, with a statement describing the method used to determine it.
Total USSGTI, the part exempt by treaty, and the net amount carried to Form 1120-F, Section I, line 9, column (b).
Use one column per vessel or aircraft subject to the 4% tax. The instructions say a corporation with USSGTI from more than four vessels or aircraft attaches continuation statements in the same size and format as Schedule V.
Enter the name of the vessel or type of aircraft. On line 2, enter the Lloyd's register number for a vessel or the registration number for an aircraft.
Answer yes or no. For a yes on line 3 by an operator under a bareboat lease, the instructions list the lessor's name and address and the lease terms to attach. For a yes on line 4 by a bareboat lessor, they list the country of registration, each lessee, the lease term, days under lease and the USSGTI method.
Enter the registered owner and the operator with their EIN or SSN. The instructions say to write "Same as filer above" when the filer is the owner or operator, and "Not known" on lines 6 to 8 when the information is unknown.
Enter the USSGTI derived from each vessel or aircraft and attach a statement describing the method used. The instructions give example methods, such as a ratio of days of travel to or from the United States, and say an allocation based on the lessee-operator's net income is not considered reasonable.
Add line 9 across the columns and any continuation statements. Enter any treaty-exempt amount on line 11 with Form 8833 attached. Subtract and enter line 12 here and on Form 1120-F, Section I, line 9, column (b).
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Schedule V is attached to the foreign corporation's Form 1120-F. The instructions refer to the Instructions for Form 1120-F for the time, place and manner of filing.
The instructions say all information reported on Schedule V must be in English and all amounts stated in U.S. dollars.
A statement describing the method used to determine the USSGTI from each vessel or aircraft is attached to Schedule V.
Yes answers on line 3 or line 4 can call for added charter details, as listed in the instructions for those lines.
Form 8833, Treaty-Based Return Position Disclosure Under Section 6114 or 7701(b), goes with any treaty-exempt amount on line 11.
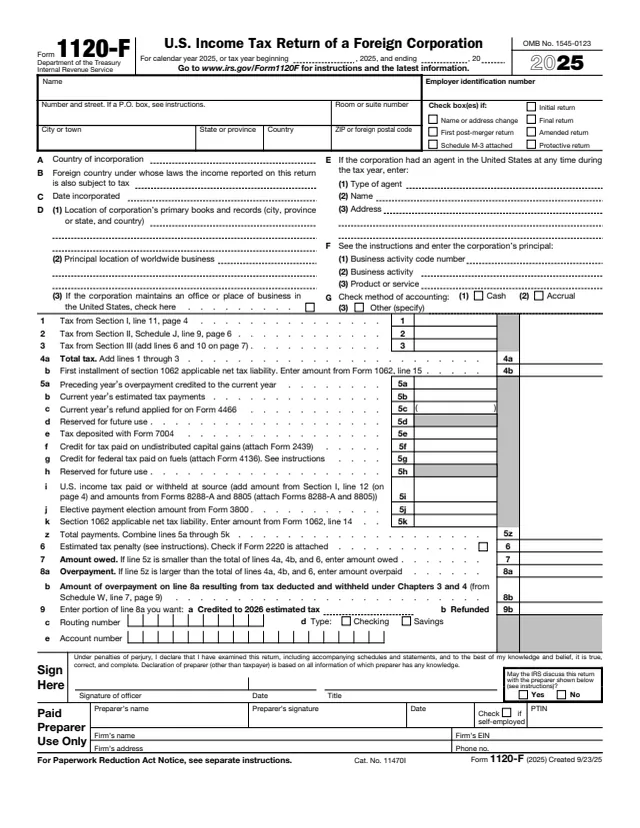
1120-F
527 fields, 9 pages
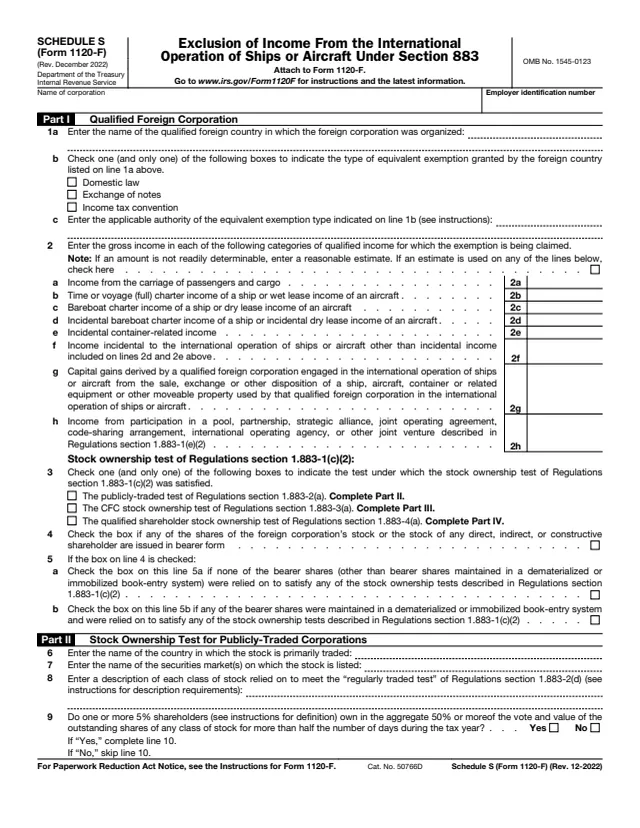
1120-F Sch. S
68 fields, 2 pages
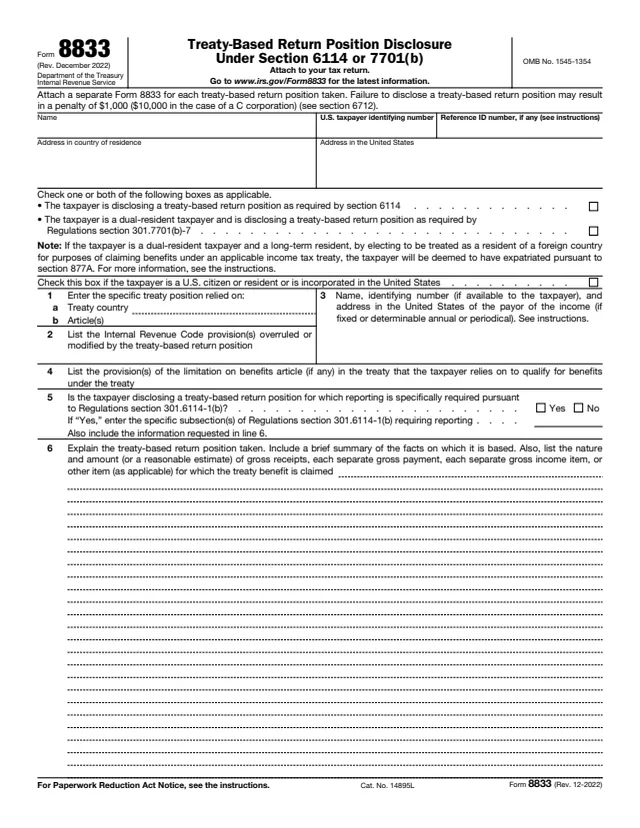
8833
41 fields, 5 pages
1120-F
77 fields, 2 pages
1120-F
113 fields, 3 pages
1120-F
173 fields, 3 pages
The instructions say foreign corporations that are subject to the 4% tax on their USSGTI under section 887 complete it.
No tool matches that search.
The instructions say foreign corporations that are subject to the 4% tax on their U.S. source gross transportation income under section 887.
The instructions define it as gross income, without reduction for deductions or losses, that is transportation income under section 863(c)(3), to the extent it is treated as from U.S. sources under section 863(c)(2)(A).
The instructions say income from the use, hiring or leasing of a vessel or aircraft, or from services directly related to that use. Income from disposing of vessels, containers or aircraft is not included.
The instructions say to attach continuation statements using the same size and format as Schedule V.
The Lloyd's register number for a vessel, or the registration number for an aircraft.
The schedule says to enter it on Form 1120-F, Section I, line 9, column (b).